

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lithium Metal Market to hit USD 7.29B by 2032 at 16% CAGR

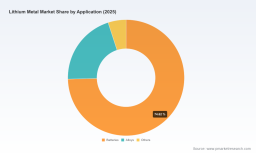
Lithium Metal Market 2026: Strategic Imperatives for Executive Decision‑Making
As the lithium metal market moves from niche R&D to commercial scale, corporate leaders face a compressed decision window in 2026: commit to localized capacity, select technology partners, or prioritize recycling and feedstock flexibility. Our PW Consulting market study—anchored on a 2025 base year and projecting through 2032—shows the market expanding at a compound annual growth rate (CAGR) of 16.0% across the 2026–2032 forecast window. That trajectory takes the global market from an estimated USD 2.6 Billion in 2025 to roughly USD 7.3 Billion by 2032, a transformation that will reorder supply chains, pricing structures and strategic positioning for battery and materials players.
Lithium Metal Market
Why 2026 Is a Strategic Inflection Point
Three forces converge in 2026 to make this a decisive year for lithium metal strategy:
Lithium Metal Market
- Technology transitions: Lithium-metal anodes, ultra-thin foils, and lithium‑metal alloys are moving from lab demoes into pilot and early commercial deployments. These technology choices are path‑dependent—early supply and IP commitments shape cost and secure customer pipelines for years.
- Supply‑side consolidation and localization: A concentrated supplier landscape means procurement, offtake and alliance decisions materially affect access to capacity and tariff exposure. Market concentration metrics indicate a small number of firms capture a substantial share of the market, intensifying strategic rivalry and creating access risks for buyers that delay commitment.
- Regulation and logistics tightening: Updated international transport guidance for lithium metal batteries—issued in early 2026—alters packaging, state‑of‑charge and shipping workflows, impacting time‑to‑market economics for new programs.
Key Dynamics Shaping Executive Choices in 2026
- Demand composition and application dynamics: Rapid adoption in high‑energy applications (advanced EVs, aviation eVTOL, and certain portable energy markets) is driving volume and premium pricing for battery‑grade materials. Buyers must weigh which end markets will scale fastest and which will reward higher material performance versus cost.
- Material and price volatility: Raw material price signals remain volatile in 2026. Recent market data indicated mid‑year adjustments in lithium carbonate pricing, reflecting inventory corrections and demand rebalancing. Procurement strategies should plan for both short‑cycle price swings and multi‑year step changes tied to new capacity online.
- Vertical integration vs. specialized suppliers: Players that integrate upstream (brine to metal) or downstream (cell/module) benefit from margin capture and supply security, but at the cost of heavier capital commitments and technical integration risk. Third‑party specialized suppliers that scale rapidly and secure offtake can command premium pricing and strategic leverage.
- Recycling and circularity: Advances in refining and electrochemical recycling are already reshaping feedstock economics. Commercial agreements for recycled material can act as strategic hedges—reducing exposure to feedstock swings while supporting ESG targets.
- Regulatory compliance and logistics: The IATA updates for lithium metal in 2026 introduce new classification flowcharts and adjusted state‑of‑charge rules for packed equipment. These changes have immediate implications for airline freight, cross‑border movements and insurance costs—factors that are frequently underestimated in project economics.
Competitive Landscape — What the Leading Players Signal
The market is characterized by a handful of focused technology leaders and vertically integrated newcomers, each pursuing different points along the value chain. Key companies tracked in our study illustrate the strategic diversity that buyers and investors must navigate:
Lithium Metal Market
- Albemarle Corporation (Charlotte, NC) — Leveraging ultra‑thin lithium metal anodes aimed at high‑energy solid‑state and lithium‑metal battery architectures. Their approach signals a play for premium anode supply to OEMs moving to next‑generation chemistries.
- Ganfeng Lithium Group (Jiangxi, China) — Investing in high‑purity metal production using oil‑free vacuum melting and low‑temperature distillation. Their capabilities point to scale‑oriented supply plays, with an emphasis on purity and production continuity.
- Pure Lithium Corporation (Charlestown, MA) — Pursuing vertical integration from brine to battery, and recently securing IP protection in key markets. Vertical integration provides margin capture and supply assurance—advantages for industrial scale OEM partners seeking predictable delivery.
- Lyten Inc. (San Jose, CA) — Recently launched U.S. production of battery‑grade alloys and foils, emphasizing tariff‑free localized supply chains. Localization reduces geopolitical risk and shortens qualification cycles for defense and aviation customers.
- Aqua Metals, Inc. (Reno, NV) — Advancing recycling‑centric supply through AquaRefining™ and signing multi‑year supply agreements, signaling growing commercial acceptance of recycled feedstock as a strategic input.
- Soelect (Greensboro, NC) and Elevated Materials (U.S.) — Developing advanced composite anodes and ultra‑thin films; partnerships and scale‑up progress point to the emergence of specialist material providers targeting commercial battery programs.
- Cuberg (U.S.) — Focused on lithium‑metal cell technology for aviation and other ultra‑safe, high‑energy applications, illustrating the attractiveness of niche, high‑value end markets where performance trumps commodity pricing pressures.
Recent corporate moves—U.S. production launch, patent grants, multi‑year supply agreements and commercialization MOUs—underline two strategic currents: (1) rapid deployment of localized capacity to avoid tariff and logistic risk, and (2) an increasing role for recycling and partnership ecosystems to accelerate commercial adoption. Our market concentration analysis also highlights that the top tier of producers command a substantial portion of supply, making early bilateral offtake and alliance agreements powerful levers for market entrants.
What the PW Consulting Report Delivers — Practical, Transaction‑Ready Analysis
This study is structured to support boardroom decisions and investment committees in 2026. Highlights include:
- Market sizing and growth pathways: A transparent historical series (2020–2025) and a detailed forecast (2026–2032) with scenario variants reflecting differing technology adoption and policy outcomes.
- Supply chain maps and capacity timelines: GIS‑level supplier footprints, tariff and logistics overlays, and capacity ramp schedules to stress‑test sourcing strategies.
- Commercial playbooks: Negotiation frameworks for offtake, term sheets, joint‑ventures, and technology licensing templates tailored to lithium metal materials and cell integration.
- Technology and IP risk matrix: Comparative assessments of anode approaches, alloy/foil vs. pure metal tradeoffs, and a roadmap for technical validation milestones that purchasers should require.
- Regulatory and logistics playbook: Actionable compliance checklists for shippers and OEMs reflecting the 2026 IATA guidance changes, and an analysis of time‑to‑market impacts by transport mode.
- Return and sensitivity models: Capex/Opex casework, break‑even horizons under alternate price scenarios, and balance sheet impacts for vertical integration versus long‑term procurement contracts.
2026 Executive Playbook — Six Immediate Moves
- Secure staged offtake and option agreements now. Use staged volume takebacks and price collars to limit exposure during the rapid growth phase.
- Pursue geographic diversification and localized contracts for strategic volumes. Where national security or tariff risk is material (e.g., defense, aviation), prioritize localized supply with clear qualification timelines.
- Accelerate partnerships with recyclers and refiners. Multi‑year recycling agreements can act as both ESG signals and practical feedstock hedges against feedstock price volatility.
- Insist on regulatory testing and logistics contingency in procurement clauses. The 2026 IATA updates change shipping economics—explicit contractual responsibilities for compliance and reroute costs are now standard negotiation items.
- Protect optionality on technology. Structure supplier relationships to allow pivoting across anode chemistries as cell‑level performance and safety data mature.
- Stress‑test investments with multiple price and adoption scenarios. Apply conservative demand ramp assumptions and quantify the value of staged capital deployment.
Conclusion — Use the Window, But Buy Optionality
By 2032 the lithium metal market is set to be multiple times larger than in 2025, driven by performance‑led applications and an evolving supply architecture. But 2026 remains a year where choices are both reversible and consequential: the firms that lock in diversified supply, secure IP through thoughtful partnerships, and design procurement and logistics to the new regulatory baseline will capture disproportionate value. Our full PW Consulting study provides the granular dashboards, supplier scorecards and contract templates that strategy teams need to convert insight into executable programs.
For access to the full dataset, segmented forecasts, proprietary supplier scoring and model templates that underpin these recommendations, contact PW Consulting or visit our report page. The executive summary above is intentionally selective—our objective is to demonstrate the depth of analysis while reserving the detailed segment matrices and financial model that will materially accelerate your 2026 planning and execution.
For detailed analysis of this topic, please visit the official page: Lithium Metal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com