

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Space Tourism Set for 31.5% CAGR, Reaching USD 3,418M by 2032

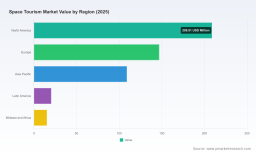
Space Tourism Market 2026 — Strategic Imperatives for Boardrooms and Investor Committees
Executive synopsis
The space tourism sector is transitioning from proof-of-concept to commercial scaling. Our latest PW Consulting market study (base year 2025; historical window 2020–2025; forecast period 2026–2032) quantifies a shift from niche experiments to a rapidly growing commercial market. At the aggregate level the industry reached approximately USD 500 Million (revenue, Million USD unit) in 2025 and, under the central scenario, is projected to expand at a compound annual growth rate (CAGR) of c.31.5% — reaching multi‑billion dollar scale by the early 2030s. For executives making allocation, partnership and go‑to‑market decisions this study crystallizes the timing, scale and near‑term inflection points that will determine winners and losers as the space tourism value chain commercializes.
Space Tourism Market
Why this study matters for 2026 decisions
-
Timing is the strategic variable: 2026 represents the first year in which several commercial programs move from testing into regular flight operations or, conversely, into strategic pauses. That makes 2026 a decision year for capital deployment, capacity commitments, and regulatory engagement.
Space Tourism Market -
Capital efficiency under uncertainty: with a market growing at ~31.5% CAGR, the returns to early movers are material — but so are the risks of overbuilding in specific subsegments. Our study provides scenario‑adjusted IRR and breakeven timelines to inform prudent investment pacing.
Space Tourism Market -
Competitive positioning: the market concentration metrics indicate a materially concentrated top tier (CR3 ~65%; CR5 ~72%), implying that strategic partnerships, offtake agreements and exclusive service features will be decisive in 2026.
Market trajectory and practical implications
Between 2020 and 2025 the sector moved from experimental flights and single‑mission announcements to repeated commercial operations and growing consumer awareness. Aggregate revenues reached roughly USD 500 Million in 2025. Our modeling — built on supply ramp curves, pricing elasticity, regulatory timelines and latent high‑net‑worth demand — shows the market expanding rapidly from 2026 onward, with the total industry value multiplying several times by the end of the forecast window (2032), under a central growth path aligned with the reported CAGR of 31.5%.
For corporate strategists this trajectory implies three operational imperatives: (1) modular capital commitments that scale with validated demand, (2) flexible contracts to manage launch cadence and crew training, and (3) layered revenue models that combine core ticketing with adjunct products (mission filming, premium payloads, research partnerships).
What the PW Consulting report delivers — operational and boardroom tools
-
Transparent market sizing and forecasting model: downloadable Excel model with scenario toggles (base/pessimistic/optimistic), demand elasticity inputs, and configurable launch cadence assumptions.
-
Investment readiness checklist: capex/opex template, break‑even analysis, and supplier qualification criteria tailored to suborbital and orbital operations.
-
Go‑to‑market playbooks: segmented approaches for OEMs, launch operators, tour operators, and hospitality brands seeking to enter or expand in space tourism.
-
Regulatory and compliance roadmap: a step‑by‑step guide to meeting NASA commercial crew standards, FAA human‑rated certification touchpoints, and practical templates for engagement with national space authorities.
-
Partnership and M&A heatmap: strategic partnership archetypes, valuation sensitivities and priority targets (operator, training, terrestrial hospitality) for quick execution.
-
Scenario intelligence and sensitivity: stress tests across pricing, launch frequency, and regulatory delays to quantify downside exposures and capital buffer needs.
Competitive landscape — what the top players are signalling
The competitive set includes dedicated suborbital operators, orbital vehicle providers, mission integrators and boutique brokers. The top three firms account for a substantial portion of the current commercially addressable market, and the top five show a higher combined share, reflecting early vertical integration and brand advantages.
-
Blue Origin (Kent, WA) has historically anchored suborbital offerings focused on brief weightless experiences. In January 2026 the company announced a strategic pause in New Shepard tourist flights for at least two years to reallocate resources toward human lunar capabilities. This move creates short‑term supply rebalancing in the suborbital tier and forces potential customers and partners to consider alternative suborbital suppliers or orbital experiences.
-
Virgin Galactic (Los Angeles, CA) continues to pursue its Delta‑class spaceplane route. As of April 2026, ground testing for Delta production systems is underway, with commercial flights targeted for late 2026. Execution risk is practical — specialized aerospace labor and passenger‑experience engineering drive production pacing — but successful deployment would expand suborbital capacity and diversify consumer offerings.
-
SpaceX (Hawthorne, CA) has leveraged Crew Dragon orbital capability and recent NASA commercial crew certifications to enable private orbital missions and ISS visits. SpaceX’s cost structures and reusability roadmap present a disruptive upside for orbital tourism, particularly for high‑value, longer‑duration experiences.
-
Axiom Space (Houston, TX) operates at the junction of mission integration and orbital tourism. Selected by NASA for a private astronaut mission (early 2027) and expanding regionally with a Japanese subsidiary (June 2026), Axiom is converting institutional relationships into a commercial pipeline for ISS and similar orbital services. Their model is instructive for firms seeking to convert governmental procurement channels into commercial demand.
-
Space Adventures (Washington, DC) continues as a market broker for orbital missions, leveraging bespoke mission packaging and premium customer servicing. Brokers remain vital in matching high‑net‑worth demand with available flight opportunities, particularly while primary operators scale capacity.
Regulatory, infrastructure and labor dynamics
Regulation is both a constraint and a moat. Updated NASA standards for private astronaut flights, FAA human‑rated certification regimes, and national licensing processes collectively set a high barrier to entry for safe, repeatable human spaceflight. Recent policy moves emphasize passenger safety and rigorous systems verification — meaning regulatory compliance is now a material line item on project schedules.
Infrastructure concentration — launch sites, integration facilities and mission control capability — will also shape geographic winners and losers. Blue Origin’s decision to pause New Shepard operations has immediate implications for Texas launch site utilization and infrastructure availability. On the production side, the Delta‑class program underscores the premium on specialized aerospace engineering labor and systems integration capability; labor cost and talent scarcity will be differentiating factors for firms ramping to full‑rate production.
Strategic choices for 2026 — actions that create asymmetric advantage
-
De‑risk the supply chain through staged commitments: align capital deployment to validated demand milestones (test flights, regulatory approvals, pre‑sales thresholds) rather than fixed multi‑year capacity builds.
-
Form pragmatic partnerships: prioritize mission integrators and brokers for demand aggregation, and pursue selective equity or offtake arrangements with operators to secure capacity without full manufacturing exposure.
-
Differentiate the customer experience: design tiered offerings (training packages, medical screening, experiential add‑ons) to increase per‑mission yield and reduce sensitivity to ticket price competition.
-
Invest in regulatory capability: embed regulatory and safety expertise early in program teams to compress approval timelines and reduce schedule risk.
-
Stress‑test economics against realistic downside scenarios: run sensitivity analyses for flight cadence delays, higher than expected operational costs, and temporary market shocks; retain liquidity buffers accordingly.
How PW Consulting’s study supports execution
Our report is structured to move an executive from awareness to action within weeks, not months. It pairs a transparent market model with playbooks and checklists tailored for board, corporate development and operations teams. Importantly, while this introduction outlines strategic conclusions and high‑level market sizing (base year 2025; historic window 2020–2025; forecast 2026–2032; CAGR ~31.5%), we intentionally withhold granular regional and application split tables and certain proprietary unit‑economics in this public summary. That detailed segmentation — including region, vehicle type and application breakdowns, and our complete financial model — is available in the full report package and the interactive analytics portal.
Next steps for executives
-
Download the full report to access the scenario model, granular segmentation, and company benchmarking matrices that quantify the strategic options outlined above.
-
Book a strategy session with PW Consulting to map your firm’s 18‑month roadmap against demand and regulatory milestones specific to your operating model.
-
Consider pilot partnerships for 2026 that lock in capacity while preserving financial optionality — our deal‑structuring templates make that process replicable and timely.
Space tourism is no longer a speculative footnote: it is an emergent commercial market with clear winners to be made in the next 18–36 months. Use the 2026 decision window deliberately — align capital, partnerships and regulatory engagement now to capture disproportionate value as the market scales.
For detailed analysis of this topic, please visit the official page: Space Tourism Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com