

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: HRSG Market to Hit USD 2,431M by 2032 at 5.82% CAGR; Asia Pacific Leads

HRSG Market 2026: Strategic Preview for Corporate Decision-Makers
Executive snapshot
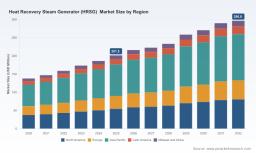
The Heat Recovery Steam Generator (HRSG) market sits at an inflection point in 2026. After expanding from approximately USD 1,400 million in 2020 to an estimated USD 1,650 million in the base year 2025, our market model projects steady, above‑average growth through the 2026–2032 forecast window. At a compound annual growth rate of 5.82%, the global HRSG market is expected to approach roughly USD 2,431 million by 2032. These headline dynamics reflect a mix of new combined‑cycle capacity, retrofit opportunities, and ongoing demand for efficient cogeneration solutions across industrial and utility customers.
Heat Recovery Steam Generator (HRSG) Market
Why this study matters for 2026 decision-making
-
Capital allocation under tightening returns: With decarbonization mandates, volatile fuel markets and tariff-driven material inflation, executives must choose which HRSG projects to greenlight, defer or redesign. Our analysis translates market growth and sensitivity to input costs into concrete CAPEX prioritization rules for 2026 board decisions.
Heat Recovery Steam Generator (HRSG) Market -
Retrofit and modernization as value levers: Mid‑life HRSGs represent a high‑velocity value pool—short outages, measurable thermal efficiency gains, and rapid payback horizons. The report quantifies the thermal uplift and operational upside from targeted modernization strategies and provides a prioritized playbook for plant owners.
Heat Recovery Steam Generator (HRSG) Market -
Supply chain and materials risk: Tariff measures affecting alloy steels, pressure parts and heat‑exchanger modules are increasing delivered costs and delivery risk. We map material exposure across typical HRSG designs and provide hedging and procurement tactics tuned to 2026 market realities.
-
Regulatory and chemistry compliance: Cycle chemistry guidelines and evolving best practices (including moves away from historical AVT(R) regimes and tighter dissolved‑oxygen/pH control targets) materially affect O&M regimes, lifecycle risk and total cost of ownership. The study translates these technical constraints into operating expenditure and outage‑risk scenarios.
-
M&A and partnering signals: Consolidation dynamics and the competitive footprint among OEMs create specific acquisition and JV opportunities for firms seeking scale in component manufacturing, modular assembly or regional aftermarket services. The report identifies strategic entry points and value capture mechanisms.
What the full report delivers — practical, decision‑ready tools
Beyond narrative context, this study is structured to be immediately actionable in the 2026 planning cycle. Key operational modules include:
-
Market modelling suite: a transparent, scenario‑based financial model (base, downside, upside) that links demand drivers, material cost curves, and pricing to regional deployment rates and producer economics.
-
Procurement playbook: vendor selection criteria, contract structures, lead‑time mitigation tactics, and a supplier‑risk heat map tailored to current tariff and logistics pressures.
-
Retrofit and O&M playbooks: standardized checklists for identifying retrofit candidates, outage planning templates that minimize downtime, and chemistry program templates aligned with modern EPRI/IAPWS guidance for corrosion control and waste minimization.
-
Vendor scorecards and negotiation levers: qualitative and quantitative assessments of major OEMs, including manufacturing footprint, proprietary materials use, modularization capabilities, and aftermarket service economics—designed to support RFP evaluation and long‑lead procurement decisions.
-
Risk register and mitigation matrix: scenarios covering raw‑material tariffs, project renegotiation clauses, regulatory shifts in cycle chemistry, and emergent supply interruptions—each mapped to tactical responses for project and enterprise risk owners.
-
Investment decision trees: ROI thresholds, NPV sensitivity tables, and go/no‑go criteria that reflect current financing costs and project risk premia for utility and industrial buyers.
Competitive landscape — who matters and why
The 2026 supplier environment blends entrenched OEM capabilities with specialized niche providers. Market concentration metrics show meaningful clustering among the largest suppliers, creating pockets of supplier leverage but also opening tactical opportunities for differentiated incumbents and nimble challengers.
-
Nooter/Eriksen — A long‑standing specialist in natural circulation HRSGs, with extensive in‑field experience and designs optimized for constructability and shipping constraints. Their depth in code compliance and long operations history makes them a go‑to for bespoke projects requiring rigorous specification management.
-
GE Vernova — Operates as a systems supplier for large combined‑cycle blocks, offering Once‑Through and modular HRSG variants and substantial in‑house pressure part capability across Asian fabrication sites. Recent project activity underscores their role in major utility transitions and large‑scale EPC programmes.
-
Siemens Energy and Mitsubishi Heavy Industries — Both emphasize integrated combined‑cycle performance and advanced thermal efficiency. Their competitive advantage lies in system integration, materials science and large‑scale project delivery for regulated utilities.
-
Babcock & Wilcox and TBWES — Known for retrofit expertise and alloy‑intensive systems used in demanding industrial contexts. They are often preferred when high‑grade metallurgy or complex retrofits are required.
-
Regional and specialized players (e.g., Vogt Power, BIH, NEM Energy, Thermal Tech, and major regional manufacturers) — These firms compete effectively on customization, rapid delivery for smaller units, and niche aftermarket services. They are increasingly important in markets where modular designs and offshore/onshore constraints matter.
Recent market moves in 2024‑2025 provide directional insight: large new‑build combined‑cycle commissions and multi‑block orders (including advanced gas turbine pairings) continue to underpin demand, while targeted retrofit projects demonstrate that modest outages can deliver meaningful thermal efficiency improvements. These signals validate simultaneous investment in both greenfield and brownfield strategies.
Regulatory, materials and chemistry dynamics that shape supply and operations
-
Tariff and materials pressure: Rising duties on imported alloy steels, tubes and fabricated modules have pushed buyers to re‑examine localisation, forward procurement and multi‑sourcing strategies. Design choices (e.g., thinner Grade 91 sections for high‑temperature areas) present trade‑offs between capital intensity and lifecycle corrosion resistance.
-
Cycle chemistry regime shifts: Industry guidance and recent practice have moved away from older AVT(R) feedwater programs toward oxygen‑controlled chemistries and amine‑based pH strategies. Operators must retool chemistry monitoring, blowdown practices and waste handling to maintain reliability and avoid iron transport issues.
-
Knowledge diffusion and EPRI/IAPWS initiatives: Ongoing research into optimized cycle chemistry and reduced chemical cleaning waste is reshaping O&M standards. Adoption of these practices materially reduces unplanned outages and extends component life when implemented correctly.
Strategic imperatives and decision triggers for 2026
-
For corporate strategy teams: Reconcile growth expectations with supplier concentration risks. Use scenario modelling to test the impact of tariff shocks and delayed deliveries on project IRR, and set procurement triggers tied to lead‑time and material cost thresholds.
-
For plant operators: Prioritize retrofit candidates using short‑cycle payback criteria and chemistry program upgrades. Target modernization packages that yield measurable thermal efficiency and emissions benefits within a single outage window.
-
For OEMs and suppliers: Differentiate through modularization, faster site assembly routines and pre‑qualified alloy supply chains. Invest in aftermarket services and remote monitoring offerings to migrate customers from one‑off sales to annuity revenues.
-
For investors and M&A teams: Look for bolt‑on opportunities that expand fabrication capacity in low‑tariff jurisdictions, or that add aftermarket service capabilities. Valuations should incorporate retrofit addressable markets and aftermarket annuity multiples.
How to use this research — from boardroom to site level
This study is designed as a decision‑support toolkit. In the boardroom it informs capital allocation and portfolio rebalancing; in the procurement office it frames RFPs and supplier negotiations; in plant engineering it provides the technical parameters and templates to scope modernization work; and in the investor community it supplies market sizing, concentration and scenario outputs necessary for valuation work.
To preserve strategic value for paying subscribers, granular segmentation breakdowns and detailed vendor‑level scorecards are reserved for the full report. The executive model and high‑level findings presented here are intentionally selective: sufficient to shape 2026 strategy, but designed to prompt direct engagement for transaction‑grade intelligence.
Next steps
-
Use the market model to stress‑test your 2026 capital plan against tariff and material‑cost scenarios.
-
Run a rapid retrofit screening across your asset base using the included outage and ROI templates to identify near‑term value capture opportunities.
-
Engage with our supplier scorecards to refine RFPs and secure better lead‑time protections and material hedges.
For organizations that require transaction‑grade detail—full segmentation, vendor‑by‑vendor financial overlays, and downloadable modelling files—please consult the complete report and accompanying datasets on our publication page. PW Consulting’s HRSG Market study is calibrated to convert market insight into measurable action throughout 2026.
For detailed analysis of this topic, please visit the official page: Heat Recovery Steam Generator (HRSG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com