

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: GaAs Wafer Market to Hit USD 1,900.7M by 2032 at 11.27% CAGR

Gallium Arsenide (GaAs) Wafer Market: A Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a targeted executive preview of our new GaAs Wafer Market study. This briefing is written to help corporate leaders, procurement chiefs, R&D heads, and investment committees align near‑term choices with the structural trajectory of the GaAs value chain. It showcases the analytical depth that underpins our full report while intentionally omitting the granular segment tables and proprietary breakouts—those are available in the full study on our site.
Gallium Arsenide (GaAs) Wafer Market
Market trajectory and what it means for planning
The GaAs wafer market has transitioned from a steady specialty semiconductor niche into a high‑growth platform driven by multi‑domain demand. Our calibrated market model, anchored to a 2025 base year, shows the market expanding from roughly USD 718.5 million in 2020 to about USD 907.6 million in 2025. Under our consensus growth scenarios the market accelerates in the forecast window (2026–2032) at a compound annual growth rate of 11.27%, reaching an estimated USD 1,900.7 million by 2032.
Gallium Arsenide (GaAs) Wafer Market
For decision‑makers these macro facts matter in five practical ways:
Gallium Arsenide (GaAs) Wafer Market
- Timing of capacity investments: an ~11% CAGR across the forecast implies that incremental capacity built in 2026–2028 can still capture outsized demand if lead times and qualifying cycles are managed tightly.
- Pricing leverage and raw‑material pressure: rising end‑market demand combined with supply chain disruptions will support healthier wafer pricing, especially where reclamation and yield improvements lag.
- Supplier strategy differentiation: the market remains sufficiently fragmented that vertical integration, strategic partnerships, or long‑term agreements can deliver material procurement and time‑to‑market advantages.
- Technology payoff horizon: investments in epitaxy, MBE/MBE‑adjacent processes and larger diameter wafers can shift cost curves meaningfully across a multi‑year window.
- M&A and portfolio optimization: the overall growth justifies targeted consolidation plays and bolt‑on acquisitions to capture higher margins in downstream processing or reclaim capabilities.
Drivers, constraints and the new supply‑side reality
Demand drivers are well known: the push to higher‑frequency 5G and beyond, the Wi‑Fi 7 upgrade cycle, satellite and space‑grade RF payloads, advanced optoelectronics, and selective power electronics applications. On the supply side, three dynamics have emerged that materially affect strategic choices in 2026:
- Raw material dynamics: gallium input costs and trade flows are now a first‑order risk. Recent industry reporting indicates a notable year‑over‑year increase in unit values for refined gallium; this has doubled the focus on reclamation, substitution (where feasible), and longer‑term supplier contracts.
- Regulatory flux and trade policy: export controls and temporary export re‑openings have compressed timelines for supplier qualification. For example, a lift in certain export restrictions in late 2025 changed short‑term availability patterns and emphasizes the need for scenario planning across policy states.
- Capacity and technology investments: selective capacity additions and technology expansions (MBE, advanced epitaxy, reclaim & post‑processing) are re‑shaping competitive advantage rather than absolute scale alone. Firms that can shorten qualification windows and stabilize yields will capture more of the incremental market.
These forces combine to make the 2026 planning window especially pivotal: decisions now will influence vendor lock, price exposure, and product roadmaps through 2028—possibly longer given wafer qualification cycle times in RF and optoelectronic supply chains.
Competitive structure: fragmented but strategic
The GaAs wafer industry is best characterized as an expanding, moderately fragmented fabric of specialized producers, substrate specialists, and vertically integrated suppliers. Market concentration measures in our model reflect this: the top three firms account for a modest share of global revenues and the top five remain well below levels associated with highly concentrated markets. Put simply, this is not a top‑heavy oligopoly—scale matters, but specialization and specific capabilities (e.g., MBE, reclaiming, high‑purity growth) frequently trump raw volume.
Key market participants demonstrate diverse strategic postures:
- AXT Inc. (Fremont, CA) — a long‑established supplier of high‑purity GaAs wafers focused on RF, optoelectronics and high‑speed applications. Its positioning emphasizes material quality and customer qualifications in tiered telecom and defense supply chains.
- Freiberger Compound Materials (Freiberg, Germany) — a specialty substrate and compound semiconductor wafer supplier with strengths in microwave and photonic device applications and high‑quality crystal growth services.
- Sumitomo Electric Industries (Osaka, Japan) — an advanced substrate manufacturer supplying semi‑insulating wafers used in 5G and defense projects, reflecting a strategy of high reliability and diversified end‑market penetration.
- IQE plc (Cardiff, UK) — a materials and epitaxy supplier with long‑term channel links to RF and optoelectronics firms; recent commercial agreements underscore its role as a strategic upstream partner.
- WIN Semiconductors (Taoyuan, Taiwan) — a contract manufacturer whose recent phase‑two expansion increased GaAs wafer capacity to capture Wi‑Fi 7 and amplified U.S. demand.
- Wafer World, Inc. (West Palm Beach, FL) — a distributor and processor that bolstered its reclaim and processing stack through acquisition, reflecting a play to capture margin in wafer recovery and post‑processing.
- Xiamen Powerway Advanced Material (Xiamen, China) — a domestic supplier focused on crystal growth and epitaxy services with aggressive capability builds.
- IntelliEPI, Inc. (Allen, TX) — an MBE‑based wafer producer that recently received preliminary CHIPS Act terms to expand production, exemplifying how public funding can de‑risk U.S. substrate capacity additions.
Strategically, this mix means buyers and investors can pursue differentiated plays—partnering with a technology leader for performance wafers, contracting with large fabs for volume, or buying reclaim capability to protect margins.
Recent market signals that require tactical responses in 2026
- Public funding and subsidies: CHIPS‑era support (e.g., preliminary terms for targeted MBE expansion) lowers the hurdle for domestic capacity projects but creates competitive pressure as new capacity comes online.
- Commercial tie‑ups and long‑term contracts: supplier agreements between material producers and device OEMs indicate that securing long‑duration supply can often be more valuable than spot price arbitrage.
- M&A and capability buys: targeted acquisitions—especially in reclaiming and post‑processing—are being employed to shorten supply chains and capture recycling economics, as seen in several recent transactions.
- Raw material import volatility: surges in imports and temporary policy shifts require that procurement frameworks be stress‑tested under multiple trade scenarios and raw‑material price paths.
What the full PW Consulting report delivers (practical, actionable content)
Our full market study is designed as a playbook for 2026 decisions. Highlights include:
- Bottom‑up market sizing and a calibrated model covering 2020–2025 historicals and 2026–2032 forecasts (editable Excel model included).
- Scenario and sensitivity analysis quantifying the financial impact of raw‑material price shocks, export control states, and accelerated technology adoption.
- Supplier heatmaps and a capability index that rank vendors across yield, diameter offerings, reclaim capability, and qualification time.
- Procurement levers and contract templates tuned for wafer markets: multi‑year offtake structures, price‑indexing clauses, and quality acceptance windows.
- Supply‑chain risk matrix and mitigations—covering single‑source risk, logistics congestion, and policy risk scenarios.
- Capex and ROI benchmarks for greenfield and brownfield capacity additions, and an M&A target shortlist for strategic buyers focused on reclaim and epitaxy capabilities.
- Technology roadmap and R&D priorities—so engineering leaders can align wafer specs to device roadmaps and cost targets.
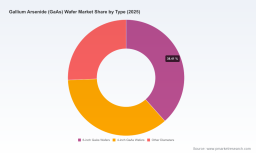
We deliberately withhold the granular regional, type, and application split tables from this preview. Those segment tables, supplier scorecards, and the downloadable model are included in the full report and are essential for supplier selection, investment memos, and procurement negotiations.
Five targeted recommendations for 2026
- Lock preferred supply: initiate 24‑36 month preferred supplier agreements with performance milestones to protect throughput and capex windows.
- Invest selectively in reclaim and yield: short payback opportunities exist for firms that can integrate reclaim workflows or partner with reclaim specialists.
- Hedge raw‑material exposure: combine contracted purchases with physical or financial hedges and diversify sources across regions and alloy routes.
- Prioritize supplier qualification agility: reduce qualification timelines through joint test programs and early access wafer lots to capture share during demand surges.
- Use public funding strategically: pursue subsidies and grants to de‑risk capacity projects in jurisdictions offering matching funds while maintaining commercial discipline on IRR thresholds.
Next steps
If your 2026 operating plan or investment thesis depends on GaAs wafer availability, price stability, or supplier continuity, the full PW Consulting GaAs Wafer Market report provides the operational playbooks, scenario models, and supplier intelligence you need. Our study couples a transparent, bottom‑up market model with commercial‑grade procurement tools and a prioritized action list so leadership teams can translate market dynamics into executable moves.
To access the detailed segment tables, supplier scorecards, and the editable forecast model, visit our report page or contact your PW Consulting client lead. The public preview you’ve just read demonstrates the analytical depth we apply; the full dataset and playbooks are designed to be directly actionable for 2026 boardroom and operating decisions.
For detailed analysis of this topic, please visit the official page: Gallium Arsenide (GaAs) Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com