

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Presbyopia Correction Devices Market to Reach USD 2,064 Million by 2032 (6.5% CAGR)

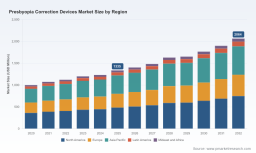
Presbyopia Correction Devices Market — Strategic Outlook for 2026
As demographic shifts and technological innovation converge, the presbyopia correction devices market is entering a decisive phase. PW Consulting’s new market study synthesizes seven years of historical observation with a seven-year forecast to 2032, providing the evidence base that senior executives, product leaders, and investors need to make high-consequence decisions in 2026. The study grounds recommendations in a clear, data-driven trajectory: the global market, which PwC-style benchmarking identifies at approximately USD 1,000 million in 2020, grew to about USD 1,335 million in the base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 6.5% through 2032 — reaching roughly USD 2,064 million by the end of the forecast horizon. These headline numbers frame a market that is large enough to sustain leading platform plays, yet dynamic enough for differentiated entrants to capture value.
Presbyopia Correction Devices Market
Why this study matters for 2026 decisions
-
Timing: 2026 is the inflection point for regulatory and reimbursement shifts, new product approvals, and technology convergence (implantables, fluidics, optics and microelectronics). Executives who align their 18–36 month plans to these inflections will secure first-mover advantages in service lines and distribution.
Presbyopia Correction Devices Market -
Capital allocation: With a mid-single-digit CAGR and projected near-doubling of market size by 2032, investors and corporate development teams must prioritize where to deploy capital — whether in R&D for next-generation implants, M&A to consolidate clinical scale, or commercial investments to build premium access in surgical centers of excellence.
Presbyopia Correction Devices Market -
Risk management: Our study highlights regulatory and reimbursement vectors that can materially shift returns. Companies that pre-emptively model these risks into pricing, evidence generation, and channel strategy convert uncertainty into advantage.
Market trajectory and interpretation
The market’s compound trend is steady and enduring rather than hyper-volatile. Growth is supported by three structural forces: demographic aging of presbyopic cohorts, rising patient willingness to pay for vision-enhancing procedures that reduce dependency on spectacles, and technological diversification (from corneal inlays and scleral approaches to novel implantable lenses and adaptive optical systems). The 6.5% CAGR through 2032 signals an expanding base market where incumbents can scale while new entrants can still secure differentiated positions by focusing on high-value niches and superior clinical outcomes.
Importantly, market concentration is meaningful: the top three players control roughly two-thirds of the market, and the top five capture nearly four-fifths. This concentration creates both entry barriers and strategic openings — incumbents defend scale advantages in distribution and clinical trust, while challengers find routes through technological differentiation, KOL partnerships, and targeted reimbursement strategies.
Dynamics reshaping the ecosystem
-
Regulatory clarity and age-indication shifts: Recent regulatory moves have broadened eligibility windows for certain implantable lenses, expanding addressable populations. Such label expansions materially change market sizing assumptions at the segment level and should be incorporated into near-term launch and clinical trial planning.
-
Reimbursement headwinds: Payer policies remain the single-largest short-term constraint on adoption of premium presbyopia solutions. Many benefit plans exclude coverage of presbyopia-correcting intraocular lenses and certain astigmatism-correcting upgrades, creating a persistent out-of-pocket market dynamic. Additionally, device pass-through or NTIOL designations under procedural reimbursement regimes are pivotal to partial coverage in ambulatory surgical center settings.
-
Clinical evidence is king: Payers and surgical centers are increasingly demanding real-world outcomes, cost-effectiveness analyses, and standardized PROMs (patient-reported outcome measures). Companies that accelerate robust registries and health-economic dossiers will unlock faster payer acceptance and preferential surgical adoption.
-
Channel evolution: The distribution axis is shifting toward coordinated care models — surgical centers of excellence, multi-specialty ophthalmic practices, and subscription-based elective service frameworks. Service-line integration (pre-op imaging, bundled perioperative care, and post-op vision therapy) is becoming a differentiator.
Competitive landscape — what the leaders are doing
The competitive field combines established surgical-device firms, specialist implant developers, and a small cohort pursuing non-implant optical solutions. Three representative organizations illustrate divergent strategic plays:
-
AcuFocus (Irvine, CA) — A focused player with a clinical, implant-driven value proposition. Its Kamra corneal inlay targets near-vision improvement in phakic presbyopes. AcuFocus’s strategy has emphasized clinical evidence, surgeon training, and targeted distribution partnerships to build procedural volume in leading refractive centers.
-
STAAR Surgical (Lake Forest, CA) — Historically known for implantable collamer lenses (ICLs), STAAR has recently extended the age indication for its EVO platform, a regulatory development that broadens the presbyopia-correction opportunity set. STAAR’s playbook blends platform durability, refractive surgery channel penetration, and iterative device enhancements to capture both refractive and presbyopic segments.
-
Laclarée Vision (Lyon, France) — A technology-centric challenger pursuing adaptive, fluid-filled eyeglasses using microfluidic actuators and sensor-driven tuning. This non-surgical approach targets a different value chain — retail optics and consumer-direct channels — and represents a strategic hedge for companies wary of surgical reimbursement constraints.
These examples underline a marketplace of distinct operating models: procedure-led implants, platform ICLs, and consumer-facing adaptive optics. Each model carries different margin structures, clinical adoption curves, and payer interactions.
Strategic implications and recommended actions for 2026
-
Prioritize evidence generation that maps directly to reimbursement levers. Beyond randomized trials, invest in registries, health-economic models, and real-world effectiveness studies that speak to payer decision criteria and ASC reimbursement pathways.
-
Design pricing and contracting strategies around partial coverage realities. Expect a continued out-of-pocket share of demand; structure premium offerings with tiered bundles, financing options, and outcome guarantees to reduce patient friction.
-
Segment go-to-market by clinical route-to-surgeon and patient journey rather than broad geographic buckets. High-return pockets will be defined by surgical center density, KOL influence, and payer mix — the full report maps these pockets to strategic plays.
-
Leverage partnerships and M&A selectively. Target bolt-on acquisitions that close technical gaps (e.g., adaptive optics, imaging analytics) or provide immediate clinical scale in priority markets. The concentration profile favors deals that accelerate access to top-performing surgical networks.
-
Invest in non-surgical adjuncts as hedges. Consumer-facing adaptive optics platforms reduce dependence on surgical reimbursement and can serve as lead-in products that convert spectacle wearers into surgical candidates.
What PW Consulting’s full study delivers (practical, actionable content)
The core study is designed as an operational playbook, not an academic exercise. Key deliverables include:
-
A transparent bottom-up market model from 2020 to 2032, with scenario runs that stress-test regulatory and reimbursement outcomes and supply chain shocks.
-
Detailed competitive profiles, product roadmaps, and clinician adoption curves for leading and emergent players, coupled with deal flow analysis for M&A and licensing opportunities.
-
Commercial playbooks: go-to-market sequencing by channel, pricing and bundling templates, customer segmentation frameworks, and an ASC engagement toolkit.
-
Evidence and payer roadmap: suggested trial designs, registry templates, and HEOR models aligned with CMS and private payer decision-making criteria.
-
Investment-grade risk matrix: quantifies downside scenarios and upside capture levers to inform capital allocation decisions.
Note: this executive overview purposefully highlights strategic insights while reserving segment-level quantitative tables, regional revenue breakdowns, and precise application splits for the full report. Those granular datasets are essential for transaction due diligence, local-market launch planning, and internal forecast integration.
How to use these insights in 2026
-
For corporate strategy teams: map your three-year product and M&A pipeline against the forecast scenarios in the full report to prioritize investments that meet mid-cycle clinical and reimbursement inflection points.
-
For commercial leaders: use the bundled commercial playbooks to accelerate surgeon training, refine patient financing offers, and negotiate ASC access tied to outcome-based metrics.
-
For investors and PE firms: employ the risk-adjusted valuation templates and market-concentration analytics to identify consolidation targets and carve-outs with defensible synergies.
Conclusion and next step
The presbyopia correction devices market in 2026 sits at the intersection of durable demand growth and volatile policy levers. The aggregate market trajectory — a base of approximately USD 1.3 billion in 2025 and a 6.5% CAGR to 2032 — supports both platform-scale strategies and focused disruptive plays. However, the ultimate winners will be those who orchestrate clinical evidence, smart reimbursement strategies, and channel execution simultaneously. PW Consulting’s full report provides the granular datasets, scenario tools, and executable playbooks needed to convert these strategic imperatives into measurable outcomes. For teams preparing 2026 budgets, product launches, or M&A pipelines, the full analysis is the practical next step.
For detailed analysis of this topic, please visit the official page: Presbyopia Correction Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com