

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Sous Vide Market to Reach USD 344.8 Million by 2032

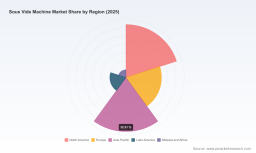
Sous Vide Machine Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Lead Industry Analyst, I present a concise strategic briefing designed to equip executives with the context and decision levers they need as they enter 2026. The sous vide machine market is no longer a niche hobbyist story: it has matured into a clearly expanding equipment category with meaningful commercial and consumer implications. Our base-year assessment (2025) values the global market at USD 215.0 Million. Under the scenarios modeled in this study, the market grows at a compound annual growth rate (CAGR) of 18.1% across the 2026–2032 forecast window — a trajectory that creates both opportunity and strategic urgency for product teams, operators, and investors.
Sous Vide Machine Market
Why this research matters in 2026
-
Momentum now meets complexity. Rapid adoption among premium home cooks, converging appliance functionality, and scaled commercial demand are creating new competitive vectors. Decisions made in 2026 about product architecture, channel strategy, and regulatory readiness will determine who captures the high-growth tail of this cycle.
Sous Vide Machine Market -
Regulatory and packaging constraints are becoming binding operational risks for manufacturers and food-service operators. The interplay between product design and compliance (packaging choice, HACCP planning, materials certification) is an underappreciated source of cost and time‑to‑market risk.
Sous Vide Machine Market -
Concentration and consolidation dynamics matter. Leading firms control a significant share of capacity and brand equity, so entrants and adjacent-players must choose between niche specialization, partnership, or acquisition pathways.
What this report delivers — practical content for immediate action
-
Market sizing and growth envelopes: a transparent historical view (2020–2025) and a forward-looking forecast (2026–2032) built from primary demand drivers rather than extrapolation alone. The report contextualizes the 2025 baseline and the 18.1% CAGR so teams can stress-test growth assumptions against their business models.
-
Segment-level demand diagnostics: qualitative and quantitative intelligence on product types, channels, and end‑use cases. (Note: this preview purposely omits the granular segment tables; the full dataset and model access are available in the published study.)
-
Competitive landscape and capability maps: detailed company profiles, strategic positioning, product portfolios, and go‑to‑market strengths — including appliance incumbents, commercial equipment providers, and emerging ecosystem players.
-
Regulatory & packaging risk matrix: end-to-end compliance checklists for design, manufacturing and commercial food production, with mitigations tied to supplier selection and verification protocols.
-
Technology and channel playbook: product feature roadmaps (hardware + software), distribution options, after-sales monetization models, and recommendations for partner ecosystems (OEM, retail, food-service).
-
M&A and valuation benchmarks: market concentration metrics and scenarios to guide acquisition screening and post-deal integration priorities.
-
Operational tools: HACCP templates, procurement scorecards for high‑barrier packaging, sample KPI dashboards, and a phased 90/180/360‑day action plan oriented to commercial pilots and regulatory readiness.
Competitive dynamics — how incumbents and challengers are positioning
The competitive set spans consumer-focused brands with app-driven experiences to heavy-duty commercial equipment manufacturers servicing restaurants and food producers. Key players profiled in the full study include firms with distinctive strategic plays:
-
Household and lifestyle brands specializing in countertop solutions and vacuum-sealing systems that target the premium residential segment.
-
Software-integrated precision-cooker providers whose mobile‑first approach aims to lock in long‑term user engagement through recipes, cloud profiles, and accessory ecosystems.
-
Commercial appliance manufacturers and industrial equipment suppliers that serve high-volume kitchens, cook-chill lines and food processors with scaled circulators and integrated cook-and-hold systems.
Collectively, the competitive picture is a two-speed market: consumer-facing units that compete on user experience and price, and commercial systems that compete on throughput, reliability, and regulatory compliance. Market concentration is material — our analysis shows that the top-tier incumbents capture the majority of market throughput, which creates pricing power and raises barriers for late entrants. Specifically, three-player and five-player concentration measures underscore a marketplace where targeted partnerships or bolt-on acquisitions are realistic accelerators for growth-seeking firms.
Recent signals you must treat as strategic inputs
-
Product convergence in consumer appliances — exemplified by multi‑function devices that now include dedicated sous vide modes — signals platform risk and opportunity. Large appliance OEMs entering the space accelerate volume adoption but compress margins for niche device makers.
-
Regulatory amplification: updated guidance and enforcement expectations (packaging, HACCP documentation, food-contact materials) will increasingly influence design specs and procurement choices. Compliance is no longer a checklist item; it is a product requirement and a go-to-market gating factor.
Regulatory and packaging realities: operational constraints that shape strategy
Three regulatory and material facts should be treated as constraints in product and commercial planning:
-
Packaging must meet high-barrier, impermeable standards at elevated temperatures; this influences supplier strategy, unit cost and claims making.
-
Food-safety processes — including documented HACCP plans and local authority review when products are prepared for sale — are mandatory for commercial applications and prudent for certain consumer use cases in shared kitchens or subscription meal businesses.
-
Materials must comply with food-contact regulations and third-party sanitation standards, which affects design timelines and testing budgets.
Strategic options and recommended playbook for 2026
-
Product strategy: prioritize modularity and serviceability. For consumer products, invest in seamless app integration and subscription recipe services. For commercial units, emphasize uptime, cleanability, and integration with HACCP workflows.
-
Supply chain: secure dual sources for high-barrier vacuum pouches and validated material certificates. Consider strategic contracts with specialty film suppliers or equity stakes in upstream suppliers to lock in quality and pricing.
-
Channel and partnerships: explore co‑branding with appliance OEMs, foodservice distributors, and ingredient brands. OEM deals can accelerate reach, while co-marketing with food brands can drive recurring demand for consumables.
-
M&A and alliances: prioritize tuck-in acquisitions that add regulatory expertise, packaging capability or commercial sales channels. Use concentration metrics to identify consolidation targets and price expectations.
-
Regulatory readiness: embed HACCP templates into commercial product documentation and budget for certification/testing early in the design cycle to avoid launch delays.
-
Sustainability and circularity: design for reduced single-use plastic exposure where possible; buyers increasingly factor material credentials into procurement choices.
Translating insight into a 90/180/360 day plan
-
0–90 days: complete a compliance gap analysis (materials and HACCP), secure preferred supplier agreements for pouches, and run a pilot integration of digital control features with two strategic channel partners.
-
90–180 days: launch a controlled commercial pilot with food-service partners, finalize product certification testing, and establish aftermarket service and parts logistics.
-
180–360 days: scale distribution through targeted retail and OEM channels, evaluate tuck-in acquisition targets identified from concentration analysis, and operationalize subscription or consumables revenue streams.
Why PW Consulting’s methodology matters
We combine a primary‑research foundation — interviews with manufacturers, distributors, foodservice operators and materials suppliers — with a demand model that reconciles unit economics, price elasticity and channel shifts. The result is an actionable dataset and scenario suite that allows executives to stress-test product investments, go‑to‑market choices, and M&A assumptions against downside regulatory and supply constraints.
In this preview I have highlighted the headline market momentum (from a 2025 baseline of USD 215.0 Million and an 18.1% CAGR through 2032) and the strategic implications that should shape boardroom debates in 2026. The full study contains granular regional and application splits, unit-level economics, supplier scorecards, and the model itself — the proprietary inputs and segment tables that power valuation and go‑to‑market planning are intentionally omitted here to preserve the value of the complete deliverable.
If your executive team is preparing product roadmaps, evaluating acquisition targets, or assessing regulatory exposure, the full PW Consulting Sous Vide Machine Market study provides the detailed metrics, templates, and scenario analyses to convert insight into decisions. Contact our research desk to obtain the full report and model access — we will prioritize a briefing tailored to the strategic questions your leadership needs to resolve in 2026.
For detailed analysis of this topic, please visit the official page: Sous Vide Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com