

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Measuring Tape Market to Reach USD 344.8 Million by 2032 at 5.67% CAGR

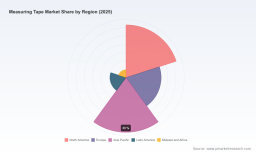
Measuring Tape Market — 2026 Strategic Preview for Corporate Decision‑Makers
Introduction: what this preview delivers
The global measuring tape market has evolved from a niche hand tool industry into a strategically relevant component of several industrial value chains. Using a 2025 base year and a historical series spanning 2020–2025, our market model shows expansion from the pandemic trough into a steady recovery. The market was approximately USD 215.0 Million in 2025 and, on the current trajectory, is forecast to reach roughly USD 344.8 Million by 2032 — a compound annual growth rate (CAGR) of 5.67% across the 2026–2032 forecast period. This article is a focused, executive‑level “trailer” of PW Consulting’s full Measuring Tape Market study: it surfaces the decision‑critical implications for 2026 while deliberately withholding segmented datapoints so you will consult the full report for transaction‑grade figures and regional/application splits.
Measuring Tape Market
Why the measuring tape market matters for 2026 decisions
-
Procurement and supplier strategy — Measuring tapes are low unit‑value items, but they are bought at scale across construction, manufacturing, medical, and semiconductor ecosystems. Small shifts in unit costs, durability standards, or compliance requirements cascade into measurable savings or risk exposure for large end users.
Measuring Tape Market -
Product and R&D prioritization — Material and feature innovations (e.g., reinforced blades, advanced coatings, dielectric properties) change value propositions. Product teams deciding 2026 roadmaps must weigh incremental investment in blade materials, printed scales, and specialty tapes (medical, body, precision diameter) against expected market demand growth.
Measuring Tape Market -
M&A and partnership targeting — The market’s vendor landscape remains fragmented (top‑three concentration is low), creating opportunistic windows for bolt‑on consolidation, regional rollups, and distribution partnerships to capture scale economies in 2026.
-
Regulatory compliance and packaging strategy — Extended Producer Responsibility (EPR) and new packaging directives are active in multiple jurisdictions and will affect tape manufacturing, labeling, and secondary/tertiary packaging flows starting in 2026.
Market dynamics and demand drivers
Demand continues to be driven by professional trades (construction, surveying), industrial maintenance, and specialty verticals such as medical/fitness body tapes and precision industrial measuring (including semiconductor-related processes). While traditional steel and fiberglass blades retain importance for durability and dielectric safety, polymer films and coated blades are gaining traction where weight, printability, and shelf presentation affect buying decisions.
Two structural dynamics are important for 2026 planning:
-
Industry specialization — A growing proportion of value is tied to specialized measuring needs (precision diameters, circumference measures, medical tape measurement). This raises the premium for accuracy, traceability, and application‑specific packaging or sterilization options.
-
Material and performance differentiation — Fiberglass blades are engineered for dielectric strength and corrosion resistance; industry documentation notes typical fiberglass constructions include tens of thousands of strands to achieve required properties. Manufacturers that can demonstrate superior blade longevity and safety credentials can command higher margins in targeted channels.
Regulatory landscape that will influence suppliers and buyers in 2026
-
India’s EPR frameworks have explicitly categorized certain plastic tapes within secondary packaging scopes, requiring registration and tracking by brand owners. For suppliers selling into Indian markets, 2026 is the year to operationalize EPR reporting and compliance workflows.
-
The EU’s Packaging and Packaging Waste Regulation (PPWR) and related guidance (issued in early 2026) targets reductions in plastic packaging waste – an element that can increase product lifecycle costs if tape substrates or adhesives fall within regulatory thresholds.
-
UK EPR rules for packaging also mandate expanded data collection on tapes treated as tertiary packaging. Exporters and multinational OEMs need harmonized data capture systems to avoid duplicative reporting burdens.
-
Separately, the EU Construction Products Regulation (CPR) has interpretative reach into measuring tools when used in construction applications — a compliance dimension that tool OEMs and large contractors should incorporate into procurement specifications and product declarations.
Competitive landscape — who matters and why
The measuring tape market remains fragmented: the three largest firms hold roughly a quarter of market revenue (CR3 ~24.6%), and the five‑firm concentration is similarly modest (CR5 ~26.2%). Low concentration signals that scale advantages are attainable via distribution control, private‑label manufacturing, or targeted product leadership — but it also means niche specialists can sustain profitable positions.
Key competitors you should track:
-
Wintape Measuring Tape Company (Foshan, Guangdong, China — https://www.tapemeasuring.com/) — A leading manufacturer with strong capabilities in precision and specialty lines (medical, body, fiberglass, steel, tailor tapes). Notable for rapid product development and a recent market consolidation move in January 2026 that strengthened its position across healthcare and body‑measurement segments.
-
Milwaukee Tool (Brookfield, Wisconsin, USA — https://www.milwaukeetool.com/) — Focused on professional retractable tapes with innovations such as compact form factors, auto‑lock mechanisms, and magnetic hooks. Launched next‑generation Compact and Auto‑Lock models in September 2024 targeted at trade professionals.
-
Crescent Tool (Brookfield, Wisconsin, USA — https://www.crescenttool.com/) — Competes on heavy‑duty construction offerings (SHOCKFORCE series) with reinforced blades and diamond‑coated hooks; a second‑generation product update was released in September 2024 emphasizing durability and jobsite visibility.
-
Stanley Black & Decker (New Britain, Connecticut, USA — https://www.stanleytools.com/) — Leverages global distribution and brand equity with durable, high‑visibility tape lines positioned at both pro and consumer segments.
-
Keson Industries (Aurora, Illinois, USA — https://www.keson.com/) — Differentiates with fiberglass and steel offerings optimized for dielectric safety and corrosion resistance; their technical resources are frequently cited for blade construction guidance.
-
Perfect Measuring Tape Company (Toledo, Ohio, USA — https://perfectmeasuringtape.com/) — Long‑standing precision tooling heritage focused on textile, medical, industrial and consumer uses; strong OEM and private‑label capabilities.
-
Pi Tape Texas, LLC (Texas, USA — https://www.pitape.com/) — Specialist in precision diameter and circumference tapes for industrial applications (pipelines, O‑rings), representing a high‑value niche within the market.
Recent industry developments to monitor in 2026
-
Product innovation continues among tool OEMs — Milwaukee and Crescent both launched enhanced retractable models in late 2024, signaling continued R&D investment in usability, blade toughness, and hook performance.
-
Market consolidation activity has resumed — a notable consolidation involving a major China‑based manufacturer in January 2026 has changed supplier dynamics in healthcare and body tape segments.
-
Regulatory timelines are compressing — multiple jurisdictions issued packaging and EPR guidance in early 2026, pushing compliance from planning into execution for many companies.
What PW Consulting’s full report includes (practical, transaction‑ready deliverables)
-
Financial market model (historical 2020–2025; base year 2025) with scenario forecasts to 2032, sensitivity testing by pricing, volume, and raw material cost shocks.
-
Executive playbooks for procurement, product development, and channel expansion — including supplier scorecards, total cost of ownership templates, and private‑label decision frameworks.
-
Detailed regulatory impact matrices (EPR/PPWR/UK EPR/CPR) with compliance roadmaps per jurisdiction and recommended operational changes for 2026 implementation.
-
Competitive benchmarking and product feature grids for the major vendors, plus an M&A heatmap highlighting attractive targets by geography and application niche.
-
Go‑to‑market route maps for prioritizing semiconductor, medical, construction, and retail channels — including recommended SKU rationalization and bundling tactics.
-
Supply chain stress tests and raw material sourcing strategies (including fiberglass blade construction considerations and polymer-substrate alternatives).
Strategic playbook — recommended 2026 actions for executives
-
Implement compliance and reporting readiness programs now — where EPR/PPWR obligations exist, treat compliance as a product cost center that will materially affect packaging and labeling strategies in 2026.
-
Prioritize higher‑margin specialty segments — invest selectively in product lines for medical, precision industrial, and semiconductor end users where accuracy, traceability, and certification enable premium pricing.
-
Pursue targeted partnerships rather than broad scale M&A initially — the market’s fragmentation means distribution partnerships and OEM supply agreements can yield faster payback than large acquisitions.
-
Reassess raw material exposure — evaluate alternative blade substrates, coatings, and adhesive chemistries to reduce sensitivity to polymer volatility and to meet dielectric/corrosion requirements in critical accounts.
-
Monitor competitor product cadences and consolidation signals — product launches and small‑scale consolidations in 2024–2026 indicate where incumbents are investing; use that intelligence to time defensive or acquisitive moves.
How to get the full intelligence
This preview outlines why 2026 is a pivotal year for measuring tape market strategy and the levers that drive competitive advantage. For transaction‑grade segmentation, regional and application splits, company scorecards, and downloadable financial models, consult the PW Consulting Measuring Tape Market report (base year 2025; forecast 2026–2032). The full study contains the granular datasets and strategic tools procurement, product and corporate development leaders need to act in 2026 — including downloadable Excel models and bespoke consultancy options for tailored market entry or M&A playbooks.
Contact PW Consulting for a personalized briefing and to obtain the full report; our analysts will walk you through the implications for your specific business unit or investment thesis and provide the underlying datasets required to underwrite decisions in 2026.
For detailed analysis of this topic, please visit the official page: Measuring Tape Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com