

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Scandium Oxide Market to Reach USD 73.8M by 2032 at 4.25% CAGR

Scandium Oxide Market 2026: Strategic Imperatives for Supply Security, Purity Premiums, and Scalable Demand
As PW Consulting’s Senior Strategic Advisor and Head of Industry Analysis, I present a condensed strategic preview of our in-depth Scandium Oxide Market study (base year 2025). This briefing is designed to show the practical value of the full report for corporate decision-makers planning through 2026 and beyond. We surface the structural trends, supply-side inflection points, and commercial playbooks that should inform sourcing, investment, and product-strategy choices — while reserving the granular segment-level tables and company scorecards for the full report.
Scandium Oxide Market
Why scandium oxide matters now: a market that is small in dollars but large in strategic impact
Scandium oxide sits at the intersection of advanced materials, defense readiness, and high-value industrial alloys. The market is compact in absolute revenue terms but growing steadily: our model shows the global market expanding from roughly USD 55.5 million in 2025 (base year) at a compound annual growth rate of approximately 4.25% through the 2026–2032 forecast window, reaching a projected market size in the low‑70s million USD by 2032. What this growth metric understates is scandium’s outsized leverage on value chains where small volumes can enable disproportionate technical advantages — lightweight high-strength alloys, specialized optics and electronics, and niche energy applications.
Scandium Oxide Market
Key structural drivers and demand vectors
-
Aluminum-scandium alloy adoption: incremental performance gains (weldability, grain refinement, strength-to-weight) create a clear pathway from aerospace and defense to selective high-performance automotive and sports applications. The technology adoption curve is still in the early commercialization phase — technical qualification, cost per kg, and supply assurance remain gating factors.
Scandium Oxide Market -
High-purity material demand: certain electronic, laser and defense applications require ultra-high purity classes with tight impurity control. Purity differentiation is a recurring theme we analyze, as it stratifies suppliers and determines margin pools.
-
Strategic procurement and stockpiling: major state and defense actors have signaled a new posture toward securing critical mineral supply. Recent long-term procurement and stockpile purchases have already altered commercial negotiation dynamics and trigger points for private-sector buyers.
-
Feedstock & byproduct nature: commercially viable scandium oxide production remains closely tied to byproduct recovery from titanium dioxide, aluminum operations and other metallurgical flows. This coupling moderates supply elasticity and creates opportunities for processing innovation and co-investment.
Supply-side inflection and what it means for buyers
2024–2026 is a pivotal interval: new demonstration and commercial-scale projects are moving from pilot to commissioning and early production. Notable capacity additions and pilots — from titanium dioxide pigment waste recovery projects to dedicated pilot plants — are improving geographic diversity of supply, but the global output remains constrained relative to potential demand ramp. This constrained but expanding supply implies that buyers who delay contracting risk higher sourcing friction and longer lead times for qualification of alternative suppliers.
Strategically, procurement teams should prioritize: (1) multi-year offtakes with volume-flex features indexed to clear purity and qualification milestones; (2) dual-sourcing strategies that combine long-term agreements with short-term spot access; and (3) structured co-investment or partnership models for upstream processing where appropriate. The full report provides practical templates and term-sheets for each pathway.
Competitive landscape — diverse players, concentrated influence
The producer community today blends resource owners, specialty material suppliers, and vertically integrated producers. A modest number of established and emerging suppliers account for the bulk of commercial supply, and recent moves by some of these players reshape bargaining dynamics:
-
Large miners and integrated producers with industrial byproduct routes are scaling demonstration plants and have the balance-sheet capacity to absorb qualification timelines and secure offtake customers.
-
Specialty material suppliers emphasize purity, tight particle-size distribution, and tailored powder forms for vacuum deposition and advanced manufacturing, creating niches of technical differentiation.
-
Emerging project developers are injecting new primary capacity, but they face the usual milestones: metallurgical optimization, capital-raising, and long lead-times to reliable, qualified supply.
Our competitive profiles (included in the full report) examine each material supplier’s feedstock access, technical processing route, purity capabilities, geographic positioning, and offtake/customer relationships — factors that materially affect qualification risk and time-to-market.
Regulatory shocks and policy tailwinds to factor into procurement and capex decisions
-
Export controls and raw-material sourcing policies are tightening globally. Recent export restrictions and critical‑raw‑materials mandates have already prompted major buyers to lock multi-year arrangements with non-domestic suppliers and to reassess their risk exposure to single-country dependencies.
-
Government-level procurement and stockpile actions have altered market signaling. A recent defense procurement award for strategic stockpiling set a new benchmark for defense-demand pricing and quality expectations — an important precedent for vendors and buyers negotiating defense-grade supply.
-
Public financing initiatives and national innovation funds are increasingly available to de‑risk domestic processing expansions. These incentives shorten the effective payback horizons for projects that can demonstrate downstream strategic value.
Operational and commercial playbook for 2026 decision-makers
For purchasing directors, R&D heads, and corporate development teams, our analysis yields a concise, prioritized action plan.
-
Immediate (0–6 months): complete supply‑chain mapping, qualify at least two suppliers for each critical purity band, and open negotiations for multi‑year offtake with volume-flex clauses tied to qualification milestones.
-
Near-term (6–18 months): embed price‑escalator mechanisms linked to transparent raw‑material indices, pursue small co-investments in upstream recovery or processing to secure preferential access, and accelerate in-house qualification cycles with vendor support.
-
Strategic (18–36 months): evaluate vertical integration where scale economics and downstream value capture justify capex, pursue joint development agreements with resource owners, and consider partnering on recycling and circularity initiatives to reduce raw-material intensity.
Risk matrix and scenario planning
Our forecast and scenario suite is explicitly built to stress-test procurement and investment decisions against a set of plausible futures: accelerated defense stockpiling, export restrictions that tighten non-domestic supply, successful ramp-up of multiple primary projects, and faster-than-expected demand uptake from auto and energy sectors. Each scenario quantifies the impact on prices, availability, and supplier bargaining power and offers tactical responses. Executives will find the scenario outputs directly actionable for boardroom discussions and treasury planning.
What the full PW Consulting report delivers (practical, transaction-ready content)
-
Proprietary market model: historical and forecast market size (2020–2032), with sensitivity doors for purity bands and application adoption curves.
-
Supplier scorecards: operational readiness, purity capability, geographic risk, commercial terms observed in the market, and a risk/return matrix for partnerships.
-
Commercial templates: sample offtake agreements, qualification checklists, and a short-form due diligence pack for upstream investments.
-
Regulatory and policy playbook: mapped implications of recent export controls, critical‑raw‑material rules, and defense procurement on commercial contracts.
-
Scenario dashboards: demand/supply stress tests, price-path sensitivity, and recommended tactical responses aligned to company risk appetite.
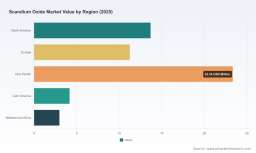
We intentionally withhold the granular regional and application-level splits in this preview — those tables, along with interactive data visualizations and supplier-level revenue decompositions, are included only in the authenticated report package. This structure is deliberate: the nuanced segmentation data is the operational intelligence that informs procurement volumes, inventory policies, and capex decisions, and is therefore gated for subscription readers.
Implications for M&A and corporate development
Given the market’s modest absolute size but high strategic utility, M&A activity in 2026 is likely to be targeted rather than headline-grabbing. Potential acquirers include specialty material companies seeking purity differentiation, miners seeking downstream capture, and strategic buyers (including defense contractors) aiming to secure qualified supply. Our deal framework in the report identifies valuation levers, likely earn-out structures tied to qualification milestones, and diligence checklists tailored to scandium oxide assets.
Final takeaway: act now to secure optionality
For 2026 planning cycles, the central strategic posture should be securing optionality: diversify supply, prioritize purity and qualification, and use structured commercial instruments that align incentives with project developers. The market is moving from scarcity toward a more diversified supply base, but the timing and quality of new supply are uneven. That combination creates a window where well-structured offtakes, targeted co-investments, and disciplined M&A can materially de-risk product roadmaps and create competitive advantage.
PW Consulting’s full Scandium Oxide Market report provides the datasets, supplier diagnostics, and transaction playbooks needed to translate these insights into executable decisions. For access to the complete analysis, interactive forecast model, and bespoke consultancy options for implementation, please visit our publication page or contact the PW Consulting industry team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Scandium Oxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com