

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Brass Rods Market to reach USD 232.4M by 2032, 2.05% CAGR (2026-2032)

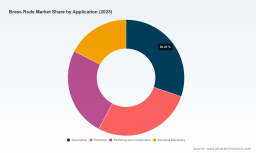
Brass Rods Market — Strategic Preview for 2026 Decision-Makers
As companies finalize budgets and strategic roadmaps for 2026, the brass rods sector presents an inflection of steady demand, cost volatility, and selective consolidation. PW Consulting’s latest Brass Rods Market study (base year 2025; historical 2020–2025; forecast 2026–2032) synthesizes primary research, supply-chain intelligence, and scenario modelling to convert market complexity into boardroom-ready choices. The global market, having stabilised near USD 200 Million in 2025 and poised to expand at a compound annual growth rate (CAGR) of 2.05% across the forecast window, will reward disciplined strategic action across procurement, manufacturing footprint, product portfolio and M&A activity.
Brass Rods Market
Why this study matters for 2026
-
Macro stability masks micro disruption. The low-to-mid single-digit CAGR reflects mature end markets—yet raw-material shocks, regulatory shifts and targeted capacity investments are creating asymmetrical risks and opportunities for market participants.
Brass Rods Market -
Timing is critical. Early 2026 corporate plans that incorporate updated cost and supply scenarios will avoid reactive seat-of-the-pants decisions mid-year when feedstock or tariff measures crystallise.
Brass Rods Market -
Decision-grade outputs. Our study delivers calibrated playbooks for procurement hedging, capacity sizing, product prioritisation and M&A screening—tools designed to be operationalised within 12 months.
What the report delivers — practical content for execution
-
Updated market sizing and validated growth trajectories (2020–2025 historical and 2026–2032 forecasts) with sensitivity cases tied to commodity swings and policy levers.
-
Raw-material economics: a quantified view of feedstock cost exposure, supplier concentration and recycled metal dynamics, plus an actionable framework to reduce scrap-copper vulnerability.
-
Pricing and margin playbooks: indexation templates, pass-through clauses, and short-to-mid-term pricing scenarios tuned to observed market moves in H1–H2 2026.
-
Regulatory and compliance checkpoint: a compliance matrix for EU and US pressure-equipment and recycling-related requirements, and supplier qualification criteria.
-
Competitive landscape and capability maps: strategic profiles for the leading industrial suppliers and a prioritized list of M&A / partnership targets based on capability gaps and geographic need.
-
Operational levers: inventory optimisation modules, CAPEX decision trees for capacity expansion vs. subcontracting, and a labour/capacity sensitivity analysis for nearshoring decisions.
-
Board-level decision support: scenario dashboards and a 100-day action plan for procurement, operations and corporate development teams.
Market structure and concentration — a balanced field
The brass rods market sits in a middle-ground concentration: the three largest producers account for a meaningful share of demand, while the top five increase that footprint further. Our concentration metrics indicate a market where regional champions sit alongside specialised independents. This configuration creates both bargaining pressure on marginal suppliers and room for targeted consolidation—particularly where capacity or certified production (for regulated applications) is a strategic differentiator.
Implication for 2026: players with scale and certification capabilities can command premium positioning, while agile mid-sized producers that master niche alloys or rapid time-to-market retain strong commercial leverage.
Competitive landscape — strategic profiles and recent moves
-
Wieland Chase (Montpelier, Ohio) — As the largest U.S. brass-rod manufacturer in our coverage, the company’s recent plant expansion initiative underscores a North American strategy that blends domestic capability with shortened lead times. The January 2026 ground-breaking for a multi‑million-dollar expansion is both a response to local demand and a hedge against international feedstock and tariff uncertainties.
-
Diehl Brass Solutions (Röthenbach, Germany) — Europe’s leading premium alloy producer, strong in high-spec tubes and profiles. Its differentiated alloy portfolio and engineering integration with end users make it a natural partner for OEMs requiring stringent tolerances and certification traceability.
-
Almag Brass (Roncadelle, Italy) — A heritage manufacturer focused on machinable and forged rods. Its June 2025 Material Manufacture Certificate to supply pressure-equipment-grade rods illustrates how certification accelerates access to regulated segments and higher-value contracts.
-
Rotax Metals (Hauppauge, New York) — A supplier with solid presence in architectural, marine and industrial niches, offering flexibility for customers seeking both standard and custom extrusions.
-
Hillman Brass & Copper (Cincinnati, Ohio) — A focused supplier of free-cutting brass varieties and machined components, serving quick-turn manufacturing and component supply chains.
Strategic read: capacity investment and certification are the two levers most clearly separating winners from laggards in 2026. Firms that proactively secure certified supply chains and align capacity with regional end-market growth will outperform peers on margin and reliability.
Key industry dynamics to monitor this year
-
Feedstock concentration and cost exposure. Scrap copper constitutes a major share of brass-rod production costs and has shown a sustained tightening trend through mid‑2025 and into 2026. This exposure implies that small upward shifts in scrap prices or restrictions on recycled metal export can compress margins quickly unless mitigated.
-
Policy and trade interventions. New tariff measures introduced in 2025 in some jurisdictions have the potential to reshape feedstock flows. Procurement teams should proactively model tariff scenarios and develop alternative sourcing or nearshoring options.
-
Certification-driven demand. Regulatory certifications (e.g., pressure-equipment standards in Europe) have become a gateway to premium contracts. Firms without certified capacity risk being excluded from higher-margin segments.
-
Price volatility in high-spec grades. Observed price points for certain premium alloy grades in mid‑2026 have tightened supplier margins and catalysed short-term contract renegotiations between mills and end-users.
Practical strategies for 2026
-
Procurement: diversify feedstock and embed flexibility. Use staged term contracts with indexation clauses, and create a dual-sourcing strategy that blends primary metal and certified recycled metal to dampen price shocks.
-
Operations: align capacity with demand pockets. Prioritise investments that enable quick changeovers to high‑value alloys; leverage contract manufacturing for low-volume specialty runs rather than committing to fixed CAPEX.
-
Products: move up the value chain. Develop certified product lines for regulated end markets, and bundle machining and finishing services to capture downstream margin.
-
M&A / partnerships: targeted and capability-led. Pursue acquisitions that bring certified capacity, proximity to recycled metal sources, or advanced alloy expertise—rather than scale alone.
-
Risk management: model tariff and raw-material shocks. Build scenario playbooks that forecast margin impact under different tariff and scrap-price paths; prepare contingency logistics and inventory buffers for critical grades.
How PW Consulting’s study supports fast, confident decisions
Our report provides the executive artifacts procurement leaders, COOs and corporate development teams need to act in 2026: integrated price and margin models, supplier scorecards, certification maps, and an M&A target prioritisation matrix. We intentionally structure outputs for rapid deployment—spreadsheets, negotiation scripts, and a 100‑day action plan—so that strategy translates into measurable commercial outcomes within the fiscal year.
Accessing the full intelligence
This article intentionally previews the study’s strategic insights while withholding detailed segmented tables and proprietary competitor revenue breakdowns to preserve the actionable value of the full report. Subscribers to PW Consulting receive the complete segmentation across regions, types and application verticals, granular company benchmarking, downloadable financial models denominated in USD (revenues in Million), and the full scenario suite for 2026–2032.
For teams looking to translate the market’s measured growth and active disruptions into 2026 outperformance, the full study is configured as an operational toolkit—not an exercise in data presentation. Reach out through our portal to obtain the full report, supporting datasets and a complimentary strategy workshop tailored to your role (procurement, operations or corporate development).
For detailed analysis of this topic, please visit the official page: Brass Rods Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com