

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Non-woven Abrasives Market to Grow at 5.4% CAGR Through 2032

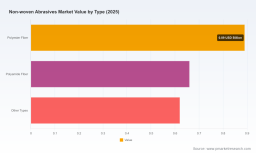
Non-woven Abrasives Market: Strategic Imperatives for 2026
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a concise, practitioner-focused orientation to our full Non-woven Abrasives Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032). This introduction surfaces the market trajectory, the forces shaping supplier and buyer behavior, and the near-term strategic choices executives must make in 2026 — without disclosing the proprietary segment-level tables and modeled splits that are included in the full report.
Non-woven Abrasives Market
Market trajectory — a resilient growth story under stress
The non-woven abrasives market has expanded steadily over the past half decade, growing from approximately USD 1.68 Billion in 2020 to USD 2.17 Billion in 2025. Our updated modeling projects a continuation of that expansion: the market is expected to pass roughly USD 2.35 Billion in 2026 and to reach the mid-single-digit billion mark again by the early 2030s, ending our forecast at about USD 3.14 Billion in 2032. That trajectory reflects a compound annual growth rate (CAGR) of approximately 5.4% through the 2026–2032 forecast window.
Non-woven Abrasives Market
Behind these headline numbers are two countervailing dynamics. Demand-side expansion remains supported by intensifying surface-treatment needs across transportation, heavy industry, industrial maintenance, and advanced manufacturing (composites and electronics). On the supply side, manufacturers face acute cost pressure and logistical uncertainty from feedstock volatility and trade-policy shifts — factors that will determine winners and losers in 2026.
Non-woven Abrasives Market
Principal market dynamics shaping 2026 decisions
-
Raw-material and feedstock volatility — In 2024–2026, synthetic fibers and resin costs drove meaningful pricing swings. Industry data put the global average non-woven abrasives price at roughly USD 2,115 per metric ton in 2024, while input-cost shocks pushed polyester and polypropylene price increases in the high single-digits to low double-digits in early 2026. In April 2026, a major polyester supplier implemented emergency price revisions exceeding 20% for some grades — an event that changed short-term margin calculus across the sector.
-
Trade and policy friction — Tariff revisions announced in the United States for 2025 raised duties on key fibers and abrasive grains. The immediate effect was an acceleration of domestic capacity investment and a reshuffling of sourcing strategies for firms exposed to duty risk.
-
Sustainability and circularity — Manufacturers and industrial buyers are accelerating interest in recycled-grain and circular-feedstock solutions. Early commercial launches and pilot plants for recycled-grain non-woven abrasives are scheduled to appear in market offerings in 2026, signaling a step change in product positioning and procurement criteria.
-
Consolidation and concentration — The market concentration metrics indicate that leading suppliers collectively command a meaningful share of sales (top-three firms account for roughly 46.2% and the top-five for about 52.0%). That scale advantage is translating into accelerated capacity investment, R&D and channel control.
Strategic implications for manufacturers, distributors and OEMs in 2026
2026 will be a year in which strategic resilience matters more than incremental efficiency. Companies that realign sourcing, product development and commercial models to the new cost and regulatory realities will capture outsized returns. Key imperatives:
-
Reconfigure supply chains for duty and feedstock risk. Near-shoring or “dual-sourcing” strategies reduce exposure to tariff and transit shocks and should be evaluated against landed-cost scenarios and service-level trade-offs.
-
Embed feedstock-price stress testing into commercial planning. Pricing clauses, tiered contracts, and dynamic pass-through models will be essential to protect margins while maintaining customer relationships.
-
Differentiate through circularity and lifecycle value. Early-mover investments in recycled-grain and validated circular products — now moving from pilot to commercial scale — will unlock premium positioning with sustainability-minded OEMs and industrial buyers.
-
Prioritize capacity and conversion flexibility. Given the uneven recovery across end markets, manufacturers should favor lines and investments that enable fast product changeover (e.g., fiber-to-conversion) and regional responsiveness.
-
Pursue targeted M&A and partnerships. With mid-sized and specialized players offering niche technical capability, bolt-on acquisitions and co-development agreements are high-return options to broaden product suites without heavy greenfield risk.
Competitive landscape — who’s positioned to lead
The competitive map is defined by a mixture of global companies with broad portfolios and specialist manufacturers with deep technical or channel expertise. A non-exhaustive view of strategic positions:
-
3M Company (Scotch-Brite) — Leverages strong brand, broad industrial channels and deep application-engineering capabilities. Their advantage is customer lock-in via specification and value-added service in surface finishing.
-
Saint-Gobain Abrasives (Norton) — Recent capacity expansion, including a new non-woven plant commissioned in Maia, Portugal (July 2025), shows an aggressive European posture to secure supply and shorten lead times. They combine scale with conversion expertise.
-
Mirka Ltd — A notable strategic differentiator is the investment in a circular-grain manufacturing facility (announced November 2024), positioning Mirka to lead on recycled-grain offerings once full commercialization occurs in 2026.
-
Hermes, Sia, Klingspor, PFERD, Weiler and other regionally strong players — These firms maintain focused portfolios for metalworking, woodworking and automotive finishing. Their moats are technical depth, channel relationships with industrial distributors and product-line specialization.
-
Tool-integrated and aftermarket players (DeWalt / Stanley Black & Decker, Walter Surface Technologies) — These companies combine abrasives with power-tool ecosystems, enabling differentiated bundled value propositions for contractors and industrial buyers.
-
Smaller specialists (ARC Abrasives, Osborn, Nihon Kenshi, SAIT) — Provide customization and specialty grades for niche industrial or OEM applications; attractive targets for strategic partnerships or selective acquisition.
Recent industry moves that matter in 2026
-
Capacity and conversion investments: Saint-Gobain’s new Portuguese plant is a concrete response to regional demand growth and trade dislocations; it shortens lead times and provides a buffer against tariff-driven supply volatility.
-
Circular-grain commercialization: Mirka’s investment in a circular grain facility in Finland reflects a broader industry pivot to lifecycle economics. By 2026, recycled-grain product availability will be a differentiator in procurement tenders with sustainability KPIs.
-
Upstream price shocks and supplier pricing actions: Emergency price revisions from suppliers in April 2026 underscore the need for buyers to revise procurement playbooks and for manufacturers to structure margin-protection mechanisms.
What the PW Consulting report delivers (practical, transaction-ready outputs)
-
Granular market model (2020–2025 historic; 2026–2032 forecast) with scenario runs and sensitivity to raw-material price paths and tariff regimes.
-
Segmentation and regional analyses (interactive dashboards and downloadable datasets) — note: detailed segment-level tables and values are gated in the full report to protect proprietary modeling.
-
Supplier scorecards and capability maps, including capacity, product breadth, vertical integration and innovation pipeline assessments.
-
Supply-chain risk heatmap and procurement playbook — supplier concentration, lead-time stress tests, and contract structures to mitigate cost shocks.
-
Commercial and pricing playbooks for OEM, distribution and aftermarket channels, plus a go-to-market blueprint for launching circular or premium product lines.
-
M&A screening and diligence checklist — technical, commercial and regulatory criteria to prioritize acquisition targets and JV partners.
Executive checklist — actions to take in 2026
-
Run accelerated scenario planning for feedstock shocks and tariff permutations; quantify margin impact and determine trigger points for price renegotiations and inventory changes.
-
Establish pilot programs for recycled-grain abrasives with strategic OEM customers; lock early feedback loops and certification pathways.
-
Audit conversion flexibility and short-cycle capacity; prioritize investments in modular conversion assets that enable rapid product shifts across applications.
-
Negotiate multi-year feedstock agreements with indexed clauses and contingency mechanisms to share upside and downside with suppliers.
-
Map potential M&A targets and integration playbooks now — market consolidation dynamics will accelerate if raw-material volatility persists.
PW Consulting’s full Non-woven Abrasives Market report provides the complete datasets, segment-level analytics, supplier financials and interactive scenario tools that corporate strategists, procurement leaders and M&A teams need to execute these actions in 2026. For executives preparing budget cycles, CAPEX requests or strategic negotiations this year, the report converts macro trends into concrete, actionable options — and the gated segment tables and dashboards supply the detailed levers for decision-making.
To access the full study, including downloadable models, supplier scorecards and our scenario-driven playbooks, please visit the PW Consulting report page. Our team stands ready to support custom workshops, tailored scenario runs, and due-diligence support for transaction activity in this rapidly evolving market.
For detailed analysis of this topic, please visit the official page: Non-woven Abrasives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com