

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: ESCs Market to Hit USD 406.56M in 2025, 5.6% CAGR Through 2032

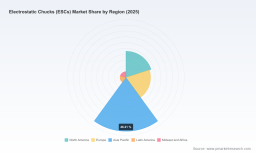
Electrostatic Chucks (ESCs) Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on Electrostatic Chucks (ESCs) synthesizes five years of historical market dynamics and a seven-year forecast to equip corporate leaders with the actionable intelligence required to make high‑stakes decisions in 2026. Built on a 2025 base year, the report tracks the ESC market through 2020–2025 and projects trends across 2026–2032. At a macro level the market is expected to expand at a steady compound annual growth rate (CAGR) of 5.6%, rising from an observed market size in 2025 to materially larger levels by the end of the forecast window. Concentration metrics signal a market that is neither fully fragmented nor dominated by a single cluster of incumbents (CR3 ≈ 28.5%, CR5 ≈ 38.2%).
Electrostatic Chucks (ESCs) Market
Why this study matters for 2026 corporate decisions
-
Accelerating technology transitions (advanced nodes, heterogeneous integration, larger/novel wafer formats) are changing ESC performance requirements — material, thermal, and electrode architectures must keep pace.
Electrostatic Chucks (ESCs) Market -
Supply chain fragility for critical ceramics and high‑conductivity materials creates tactical procurement exposure for equipment OEMs and fabs alike; 2026 is a window to secure capacity ahead of the next investment cycle.
Electrostatic Chucks (ESCs) Market -
Competitive avenues are bifurcating between high‑performance, materials‑led differentiation and systems integration into process tools — strategy in 2026 will determine who captures aftermarket and service revenue as well as new OEM design win opportunities.
-
Investor and M&A activity will intensify around niche ceramics specialists and service/refurbishment providers — those who move early on diligence and bolt‑on acquisitions can compress time‑to‑market for differentiated ESC offerings.
What the PW Consulting report delivers — practical components
-
Executive dashboard: concise market snapshots, decade view, and scenario outputs tailored for board and C-suite briefings.
-
Market sizing & scenarios: rigorous bottom‑up and top‑down TAM/SAM/SOM frameworks, with sensitivity runs that map investment timing to revenue outcomes under conservative, base, and accelerated adoption cases.
-
Technology and materials roadmaps: comparative analysis of Coulomb vs. Johnsen‑Rahbek architectures, advanced ceramics (alumina, aluminum nitride), electrode patterning strategies, and emerging surface treatments that affect plasma resistance and wafer flatness.
-
Supply chain heatmaps: supplier concentration, single‑source risk nodes, critical material lead times, alternative sourcing options, and cost/quality tradeoffs for critical inputs.
-
Commercial playbooks: pricing elasticity models, aftermarket and refurbishment monetization strategies, channel and distribution scenarios, and negotiation templates for multi‑year supply agreements.
-
Competitive target list & M&A playbooks: candidate screening criteria, valuation multiples observed in recent comparable deals, integration risk checklists, and synergy realization paths.
-
Operational templates: production yield levers, quality control checklists for ceramic fabrication, process control KPIs, and rapid pilot‑to‑scale checklists for new ESC designs.
-
Workshops and implementation sprints: ready‑to‑run client workshops that translate insights into a 90‑day action plan and a 24‑month roadmap aligned to CapEx cycles.
Data‑driven highlights and strategic implications
-
Growth trajectory and timing: with a base‑case CAGR of 5.6% across the forecast horizon, the ESC market offers consistent, predictable expansion rather than hypercyclical spikes. This pattern favors companies with disciplined product roadmaps and predictable supply commitments.
-
Market concentration: CR3 and CR5 values indicate meaningful presence of established players but room for differentiated entrants. Strategic newcomers that combine materials expertise with tool‑level integration can carve defensible niches without immediately triggering incumbent retaliation.
-
Technology convergence: the interplay of thermal management, plasma resistance, and electrostatic force control is becoming the design battleground. Aluminum nitride and other high thermal conductivity ceramics are moving from niche to mainstream for high‑power plasma applications — a material advantage that can translate directly into process performance claims for customers.
-
Serviceable market expansion: beyond OEM sales, refurbishment, replacement services, and retrofit opportunities represent an enlarging revenue pool that rewards firms able to bundle hardware, maintenance, and uptime guarantees into commercial contracts.
-
Capital allocation guidance: steady market growth suggests that selective, focused investments (strategic partnerships, capacity expansions for critical ceramics, and modular ESC platforms) will yield a higher return on invested capital than broad, unfocused expansion.
Competitive landscape — supplier archetypes and positioning
-
Advanced ceramics specialists: firms with deep ceramics know‑how drive material performance and reliability. Their strengths lie in internal electrode designs, plasma resistance coatings, and formulation expertise that deliver wafer flatness and thermal uniformity. Watch for technology licensing and supply agreements from this cohort as they monetize IP beyond direct OEM sales.
-
Integrated equipment OEMs: vendors who bundle ESCs as part of larger etch/deposition platforms differentiate on systems integration — segmented electrodes, independent voltage control, and embedded diagnostic features are ways they lock in tool design wins and recurring services.
-
Global service and refurbishment specialists: firms offering refurbishment, replacement, and aftermarket services capture long‑tail revenue and can become preferred partners for fabs seeking uptime guarantees and predictable TCO models.
-
Regional challengers and scale‑up entrants: local manufacturers that focus on cost competitiveness and quick delivery represent near‑term competitive pressure, particularly in opportunistic retrofit markets. Their trajectory depends on securing material quality and obtaining process tool compatibilities.
Representative firms in the ecosystem illustrate these archetypes and the strategic moves to monitor in 2026:
-
Kyocera Corporation — leverages advanced fine ceramics and internal electrode architectures to deliver high plasma resistance and precise wafer mounting for demanding process environments.
-
NGK Insulators — differentiates on aluminum nitride formulations with very high thermal conductivity for uniform temperature control under high‑power plasma loads.
-
SHINKO Electric Industries — offers comprehensive ceramic ESC families across multiple material systems and ESC types, positioning for broad coverage of wafer sizes and process applications.
-
TOTO and NTK CERATEC — apply ceramics expertise to high‑performance ESC designs focused on wafer holding and flatness correction in advanced fabs.
-
Sumitomo Osaka Cement — targets high‑performance ESC applications with a manufacturing heritage in engineered ceramics.
-
Applied Materials — integrates proprietary ESC designs into their process platforms, using segmented electrode patterns and independent voltage control as a systems‑level differentiator.
-
Technetics Semi and Entegris — combine hardware with aftermarket and refurbishment services, capturing long‑term value through service contracts and replacement cycles.
-
Beijing U‑Precision and other regional players — represent the cost‑competitive cohort, increasingly present in retrofit and regional capacity expansions.
A pragmatic strategic playbook for 2026
-
For OEMs: prioritize partnerships with ceramics specialists to lock in material roadmaps and co‑develop ESC designs that are both modular and upgradeable. Embed diagnostic telemetry to create recurring service revenue streams.
-
For fabs: accelerate qualification pathways for higher‑performance ESC materials and secure multi‑year supply agreements for critical components to avoid lead‑time fracturing during capacity ramps.
-
For suppliers: invest selectively in capacity for high thermal conductivity ceramics and build refurbishment/service offerings to capture aftermarket economics and improve customer switching costs.
-
For investors and M&A teams: screen targets that combine differentiated materials IP with established customer relationships in process tool OEMs or large fab groups — integration potential and near‑term aftermarket revenue should be primary valuation drivers.
How PW Consulting supports decision execution
-
Tailored diligence: supplier and asset‑level diligence focused on material supply, IP defensibility, and integration risk.
-
Commercial acceleration: bespoke negotiation playbooks, supplier scorecards, and pilot commercialization plans that reduce time‑to‑revenue for new ESC designs.
-
Operational readiness: manufacturing scale‑up blueprints, yield improvement programs, and quality assurance roadmaps for ceramic fabrication.
-
Workshops and sprints: facilitated 90‑day sprints to convert the strategy into prioritized tactical actions, assigned owners, and measurable KPIs.
Our research is intentionally a “trailer” — it reveals the structural dynamics, competitive vectors, and practical levers that matter for 2026 decisions while preserving the granular segmented data, market tables, and company‑level financial estimates for subscribers and clients. To access the full dataset, including granular regional/application splits, supplier shares, and downloadable modeling templates that underpin the scenarios summarized here, please consult the full report on our website.
PW Consulting’s ESCs market study arms leaders with the contextual clarity and operational playbooks needed to move decisively in 2026: secure critical materials, pick the right partners, and structure contracts that convert predictable market growth into sustainable competitive advantage.
For detailed analysis of this topic, please visit the official page: Electrostatic Chucks (ESCs) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com