

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Hydraulic Hammer Market to Reach USD 2,400.82M by 2032 at 5.79% CAGR

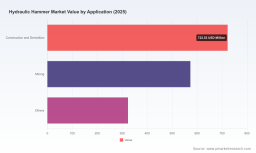
Hydraulic Hammer Market — PW Consulting Strategic Preview (2026)
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our full Hydraulic Hammer Market study — a decision-grade resource crafted for executives shaping capital allocation, product strategy, and M&A moves in 2026. Built on a 2025 base year and a detailed historical window (2020–2025), our model projects the market through 2032. The market expanded from roughly USD 1.25 billion in 2020 to about USD 1.62 billion in 2025 and is forecast to surpass USD 2.40 billion by 2032, growing at a compound annual growth rate (CAGR) of 5.79% over the 2026–2032 forecast horizon. This preview synthesizes the strategic implications of those trends while intentionally withholding granular segment-level figures — the full intelligence set is reserved for report subscribers.
Hydraulic Hammer Market
Why this study matters for 2026 decision-making
-
Timing: 2026 is a pivot year. Macro recovery dynamics, tightened emissions standards, and accelerating product innovations mean decisions made now will determine market share and profitability through the next equipment replacement cycle.
Hydraulic Hammer Market -
Capital allocation: Our forecast and scenario analyses translate market momentum into actionable spend recommendations across R&D, production scaling, and aftermarket build-outs — helping you prioritize investments with quantified ROI expectations.
Hydraulic Hammer Market -
Risk mitigation: From raw material volatility to regulatory shocks, we provide stress-tested downside scenarios and hedging strategies so procurement and treasury can lock in margins without sacrificing competitiveness.
-
Competitive positioning: A compact, evidence-based playbook shows where product differentiation, service models, and channel tactics produce asymmetric advantages against incumbents and regional challengers.
Market dynamics to factor into 2026 strategies
-
Steady, resilient growth: After a five-year historical run and near-term resilience, the hydraulic hammer market shows steady expansion through 2032. The growth profile supports mid- and long-term investments in both core products and adjacent services.
-
Regulatory pressure accelerating innovation: Tightening emissions frameworks (notably Euro 7 and comparable regimes) are driving manufacturers to re-think hydraulic system efficiencies, machine integration, and ancillary equipment emissions — creating windows for first-mover advantage in “cleaner” breaker solutions.
-
Raw material and supply-chain friction: Steel price volatility continues to pressure fabrication costs — our sector analysis indicates a meaningful share of manufacturers reported cost impact from steel fluctuations. Procurement strategies and alternative sourcing will be decisive for margin stability in 2026.
-
Operational compliance and labor pressure: Noise and workplace exposure rules are shifting product requirements; a subset of OEMs already report impacts from compliance-driven redesigns. Manufacturers able to cost-effectively incorporate noise mitigation will access new commercial opportunities in urban demolition and infrastructure upgrade projects.
-
Service and telematics as value drivers: Value is migrating from one-time equipment sales to lifecycle management. Telematics-enabled predictive maintenance, easier field serviceability, and parts availability are emerging as primary differentiators in procurement decisions.
-
Demand heterogeneity: While core demand stems from construction, demolition and mining projects, procurement patterns vary by operator type (rental houses vs. owner-operators vs. mine fleets). Customized go-to-market strategies that recognize these channels will outperform one-size-fits-all approaches.
Competitive landscape — what incumbents and challengers are doing
The hydraulic hammer market remains fragmented (market concentration metrics indicate a low combined share among the largest firms), creating a competitive environment where product innovation, service excellence, and distribution reach matter more than sheer scale alone. Our competitive synthesis highlights recurring strategic themes among leading players:
-
Epiroc AB — Stockholm-based Epiroc continues to emphasize smart maintenance and operator-focused design. Recent product introductions (e.g., new EC series models showcased at major equipment shows) underline a push for reduced life-cycle costs through modular wear parts and active percussion chamber management — features that appeal to fleet operators seeking uptime gains.
-
Sandvik (Rammer) — Integration of hydraulic breakers into broader equipment portfolios and an emphasis on robust design for mining and heavy construction remains Sandvik’s strategic edge. Their channel partnerships with OEM equipment brands preserve relevance in fleet-level procurement processes.
-
Caterpillar — Leveraging an unparalleled global service and dealer network, Caterpillar’s attachments strategy converts OEM relationships into sticky aftermarket revenue; their scale enables bundled financing and service contracts that are particularly attractive to rental houses and large contractors.
-
Atlas Copco, Komatsu, Furukawa and other OEMs — These players focus on niche technical differentiators (e.g., rock excavation, trenching, heavy-duty mining breakers) and geographic strengths. Several have introduced incremental product improvements aimed at reducing weight, improving maintainability, and enhancing operator safety.
-
Regional and low-cost manufacturers — A cohort of Asian and European suppliers competes aggressively on price and customization. Their presence keeps pricing discipline in many end markets but also creates acquisition targets for international players seeking capacity or market access.
Recent market events reinforce these dynamics: targeted product launches in 2025–2026 (including multiple new EC-series breakouts), active trade-show participation by both incumbents and emerging brands, updated operator manuals and service collateral from aftermarket specialists, and government solicitations that create near-term demand pockets for specific OEMs. Collectively, these activities signal a market balancing product-centric differentiation with service-led capture strategies.
Strategic opportunities and operational priorities for 2026
-
Product architecture for serviceability: Prioritize modular components, field-replaceable wear items, and service-friendly designs. Our benchmarking shows that reduced mean-time-to-repair translates directly into higher utilization rates for fleet customers.
-
Electrification and hybrid readiness: Even where full electrification is not immediately feasible, designing breakers for compatibility with electrified excavator platforms mitigates obsolescence risk as end-users decarbonize fleets to meet emissions mandates.
-
Aftermarket and subscription models: Build recurring revenue via parts, preventive maintenance subscriptions, and telematics-based analytics. Structured service offerings increase customer lifetime value and create insulation from cyclical new-equipment markets.
-
Supply-chain hedging: Implement raw material procurement strategies (long-term contracts, alternative suppliers, local sourcing) and lean inventory tactics to smooth cost exposure from steel price swings.
-
M&A and partnerships: With low market concentration among top players, bolt-on acquisitions (component makers, regional distributors, telematics startups) can rapidly enhance capability sets and expand addressable market access.
-
Channel segmentation: Differentiate commercial approaches across rental fleets, large contractor accounts, and direct mine procurement. Each requires tailored product, warranty and financing structures.
What PW Consulting’s full report delivers (practical, ready-to-use outputs)
-
Comprehensive market size and forecast model (2020–2032) with base year 2025 and scenario toggles for upside/downside risk assumptions.
-
Segment-level dashboards (by region, type, application) and demand-driver heatmaps — note: detailed segment tables and percentage splits are available in the full report only.
-
Competitor playbooks: profiles, product positioning maps, recent moves, and capability gap analyses for >20 vendors.
-
Price and cost benchmarking, including a raw-material sensitivity module that quantifies margin impacts from steel price swings and labor/regulatory compliance costs.
-
Regulatory impact matrix: a practical guide to Euro 7 and analogous standards, with prioritized design and certification milestones.
-
Commercial playbooks — tactical sales scripts, rental-house engagement frameworks, and tender capture templates for government procurement (including how to align with small-business set-asides and government solicitations).
-
Strategic option analyses and a decision-support tool that quantifies expected returns for R&D, manufacturing scale-up, aftermarket expansion, and M&A scenarios.
Immediate next steps for executives (practical checklist)
-
Run the PW Consulting stress-test model on your product roadmap to quantify exposure to regulatory scenarios and material-cost shocks.
-
Prioritize one pilot program in 2026 for either telematics-enabled maintenance subscriptions or a service-bundled financing offer to test recurring revenue elasticity.
-
Initiate a strategic sourcing review aimed at reducing steel procurement price exposure within 6–9 months and identify at least one alternate supplier per critical component.
-
Scan the M&A landscape for complementary capabilities (forging suppliers, wear-part specialists, telematics providers) that can be integrated within 12 months.
-
Engage regulatory and certification teams now to map compliance milestones against upcoming product launches — early alignment reduces time-to-market risk.
In sum, the hydraulic hammer market presents a mix of steady growth and structural change. Companies that combine pragmatic product design, aftermarket-driven business models, and supply-chain resilience — while closely monitoring regulatory inflection points — will convert 2026 investments into disproportionate returns across the 2026–2032 horizon.
Next step — access the full PW Consulting hydraulic hammer study
This preview outlines the strategic lens and the actionable frameworks included in our full study. For the complete segmentation tables, competitor market-shares, downloadable financial models, and the decision-support dashboard, please access the PW Consulting report page. The full report contains the granular data and step-by-step playbooks needed to operationalize the recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Hydraulic Hammer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com