

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Epinephrine Autoinjector Market to Reach USD 348M by 2032 at 8% CAGR

Epinephrine Autoinjector Market: Strategic Imperatives for 2026 Decision‑Makers
Prepared by PW Consulting — Senior Strategic Advisory & Industry Analysis
Epinephrine Autoinjector Market
Executive snapshot
The epinephrine autoinjector market is transitioning from scarcity‑driven volatility toward structurally higher demand and renewed competitive intensity. Our modelling (base year 2025) shows the global market expanding on an 8.0% compound annual growth rate (CAGR) through the 2026–2032 forecast window, with the market size rising materially from the mid‑2020s into the early 2030s. That trajectory reflects a mix of demographic and policy tailwinds, increased public and institutional adoption, and a maturing generics presence — set against periodic supply‑side shocks and regulatory events that continue to reshape access and pricing dynamics.
Epinephrine Autoinjector Market
Why this research matters for 2026 decisions
- Tactical procurement and formulary strategy: With episodic shortages and manufacturer line disruptions still present in early 2026, buyers and payers need precise, forward‑looking visibility into supply flexibility and alternative sources to avoid operational risk.
- Go‑to‑market and pricing programs: Manufacturers and distributors must balance coupon/copay mechanics, institutional contracting, and differentiated product positioning (e.g., voice‑guided devices) to protect margins while expanding access.
- M&A and capacity investments: The market shows consolidation opportunities and capacity investment cases where supply redundancy can be monetized — particularly for strategic players seeking to close hospital and government channels that require guaranteed supply.
- Regulatory and geopolitical risk management: Recent recalls and distribution constraints create potential withdrawal scenarios in certain markets; the right surveillance framework is essential for 2026 planning.
What PW Consulting’s market study delivers (actionable contents)
- Proprietary market sizing and model framework (base year 2025; historical 2020–2025; forecast 2026–2032) with scenario and sensitivity layers that quantify the impact of shortage events, reimbursement shocks, and accelerated generic uptake.
- Supply chain heatmap and supplier scorecards — manufacturing footprints, single‑point failures, lead‑time analyses, and recommended mitigation playbooks for procurement teams.
- Commercial intelligence on pricing levers, coupon/copay program ROI, and channel economics across hospital, retail pharmacy, and emergency preparedness channels.
- Regulatory and reimbursement playbook — pathways for device approvals, anticipated formulary positioning, and payer negotiation strategies focused on the coming 24 months.
- Competitor strategic profiling and scenario planning — product differentiation strategies, capacity commitments, partnership opportunities, and prioritized M&A targets.
- Practical implementation templates — procurement term sheets, supplier risk clauses, go‑to‑market launch checklists, and a rapid‑response shortage playbook.
Market dynamics and drivers
Demand drivers combine epidemiology (persistent prevalence of anaphylaxis‑prone conditions), institutional policy (schools and workplace emergency preparedness), and rising patient awareness and self‑provisioning. On the supply side, generics and authorized generics have improved fill rates in many formularies, but manufacturing continuity challenges — including intermittent shortages at legacy manufacturers — keep procurement teams on alert.
Epinephrine Autoinjector Market
Key policy and commercial developments through 2025–mid‑2026 reinforce these dynamics: manufacturers have refined copay programs to protect retail uptake; regulatory approvals expand hospital supply options; and targeted device selections (including specialized applications such as aerospace mission kits) underscore the premium and differentiation plays available to innovators. Our forecast explicitly incorporates these measurable drivers and models multiple downside scenarios where recall or capacity loss events reallocate demand rapidly.
Competitive landscape — who matters and what they signal
The market exhibits moderate concentration: leading incumbents maintain important institutional relationships, but a broad set of competitive options and generics keep the market contestable. The three‑to‑five largest suppliers account for a material but not overwhelming share of global supply, leaving room for nimble entrants and contract manufacturers to change dynamics quickly.
- Viatris Inc. — A longstanding supplier with a deep institutional presence across hospitals, pharmacies, and public preparedness channels. Viatris remains a cornerstone supplier for many systems; however, ongoing production constraints on legacy lines have created windows of opportunity for competitors and contract manufacturers.
- Teva Pharmaceutical Industries Ltd. — A scale generics player that leverages distribution breadth and copay programs to sustain retail uptake. Teva’s digital copay refinements indicate a focus on protecting volume in competitive markets while preserving list price positioning.
- Amneal Pharmaceuticals LLC — A strategically positioned manufacturer whose recent regulatory approvals for hospital‑oriented formulations and ongoing production capacity make it an increasingly important supplier for acute care and perioperative channels.
- Kaleo Inc. — Differentiation through design and user experience (voice‑guided device) — and selection into specialized mission kits — demonstrates a premium product play that can command institutional and niche‑market access even amid generic competition.
- ALK‑Abelló A/S — A regional leader in Europe with occasional distribution friction in other geographies following recall events; their situation highlights how regulatory recalls can rapidly alter competitive footprints.
Recent developments that will shape 2026 strategy
- Product selection into special mission environments underscores the value of differentiated device features in non‑traditional procurement channels.
- New approvals for hospital formulations broaden the hospital playbook, enabling manufacturers to capture higher‑margin institutional volume beyond 1:1 retail replacement demand.
- Copay and savings program adjustments remain a primary lever to manage retail penetration; program caps and eligibility nuances materially affect net patient cost and manufacturer gross‑to‑net profiles.
- Recalls and constrained distributor access continue to create rerouting of demand and upward pressure on spot market prices for short durations — forcing buyers to adopt multi‑supplier contracting and safety stock protocols.
Strategic implications and recommended actions for 2026
Organizations across the value chain should prioritize three clusters of action:
- Supply resilience and sourcing: Secure tiered supply contracts with minimum fill guarantees, qualify alternate manufacturers, and incorporate capacity options into corporate continuity plans. For buyers, introduce flexible purchasing clauses that allow diversion to authorized generics when shortages are declared.
- Commercial optimization: For brand and generic manufacturers, refine copay programs to balance share retention with margin protection; invest selectively in device differentiation (usability, voice guidance, compact form factors) that command premium placement in institutional kits and specialized channels.
- Regulatory and market intelligence: Maintain a live regulatory tracker focused on recalls, approvals, and formulary shifts. Payers and hospital systems should model formulary outcomes under both “steady supply” and “recall” scenarios to quantify clinical and financial exposure.
KPIs and leading indicators to watch in 2026
- Manufacturer reported production uptimes and lot‑release timelines (short windows of below‑target uptime are early warning of supply risk).
- Formulary placement changes, particularly within Medicare Part D and major commercial plans, which will alter generic fill rates.
- Coupon/copay program modifications and caps — small changes have outsized effects on retail demand elasticity.
- Regulatory filings and recall notices — both speed and scope determine reallocation of institutional contracts.
- New product selections into specialized institutional kits (e.g., aerospace, defense, emergency preparedness) as a bellwether for premium device demand.
Methodological rigor and what is intentionally withheld
Our study blends primary interviews with manufacturers, hospital procurement officers, payers, and distributors; a bottom‑up supply chain mapping; and a market model calibrated to real‑world shipment and sales data. The report provides a complete model, sensitivity analyses, supplier scorecards, and executable tools for procurement and commercial teams.
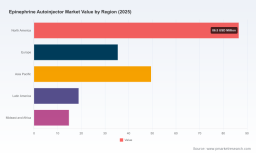
In keeping with our “trailer” principle, this introduction showcases the analytical depth and strategic value of the full study while intentionally withholding granular region/application splits and certain contract‑level datapoints that are included exclusively in the full report. Those granular slices — which shape tactical supplier selection and bidding strategy — are provided only through the full licensed dataset to ensure clients receive verified, operationally relevant intelligence.
How PW Consulting helps clients act
- Rapid due‑diligence workshops for sourcing teams to run simulated shortage scenarios and test contract language.
- Commercial playbooks for manufacturers that map pricing, coupon mechanics, and targeted institutional value propositions.
- Transaction support for buyers and investors evaluating bolt‑on capacity targets or vertical integration opportunities.
- Customized dashboarding and early‑warning systems that feed into procurement ERP and category management workflows.
Next steps
For procurement leaders, payers, and market‑facing manufacturers planning decisions in 2026, this study provides the quantitative foundation and pragmatic tools to convert market volatility into strategic advantage. Contact PW Consulting for access to the full dataset, supplier scorecards, and tailored scenario workshops that translate this market intelligence into executable plans.
For detailed analysis of this topic, please visit the official page: Epinephrine Autoinjector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com