

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PAA Market to Reach USD 344.8M by 2032 at 8.5% CAGR

Peracetic Acid (PAA) Market: Strategic Imperatives for 2026
Executive snapshot
Peracetic acid (PAA) is moving from niche disinfectant chemistry toward broadened industrial adoption. PW Consulting’s latest market study — anchored on a 2025 base year and a 2026–2032 forecast horizon — shows the global PAA market continuing a robust expansion driven by hygiene governance, wastewater treatment upgrades, and industrial oxidation uses. At a compound annual growth rate (CAGR) of 8.5% the market has grown from a mid‑three‑figure USD million base in 2020 to approximately USD 215 million in 2025, with PW projecting further expansion to roughly USD 345 million by 2032.
Peracetic Acid (PAA) Market
This introduction frames why those macro trends matter for executives planning capital allocation, product strategy, regulatory preparedness, and M&A through 2026. We intentionally present high‑confidence, decision‑relevant conclusions while reserving the granular segment and regional matrices for subscribers — a deliberate “trailer” approach that demonstrates our analytical depth and preserves the proprietary data that underpins tactical moves.
Peracetic Acid (PAA) Market
What the data reveals — high‑level takeaways
- Market momentum: Historical growth between 2020 and 2025 established the PAA market on an upward trajectory; with an 8.5% CAGR forecast into 2032, PAA represents a mid‑stage growth market rather than a commoditized mature segment.
- Moderate concentration: Competitive intensity is meaningful but not monopolistic — our concentration analysis finds the top three players hold a substantial portion of market value while the top five increase that share modestly, indicating space for regional leaders, specialized formulators, and agile new entrants.
- Application diversity: Demand originates from multiple, structurally different end markets (food & beverage sanitation, healthcare sterilization, municipal and industrial wastewater treatment, pulp & paper, aquaculture). Each application imposes distinct regulatory, packaging, and logistics requirements that influence unit economics and go‑to‑market approaches.
- Operational and safety constraints: Above certain concentrations, PAA handling triggers costly plant engineering and safety investments (e.g., explosion‑proof equipment), creating natural barriers to commoditized bulk supply and favoring vertically integrated or specialized manufacturers.
Key demand drivers for 2026 strategic planning
Executives must plan against three intersecting drivers that will shape near‑term demand and supplier economics:
Peracetic Acid (PAA) Market
- Regulatory tightening and approval dynamics: Recent approvals under major jurisdictional frameworks have clarified end‑use acceptability but also raised compliance complexity. Firms preparing new formulations or market entries must build regulatory timelines into product development and commercialization schedules.
- Institutional hygiene and sustainability mandates: Heightened expectations for pathogen control in food production, healthcare and municipal systems are encouraging substitution toward oxidizing biocides like PAA that offer fast action and degradability. Procurement teams are increasingly assessing life‑cycle risk and residue profiles when specifying chemistries.
- Infrastructure and logistics cost sensitivity: Bulk PAA requires compatible storage and transport systems; investments in appropriate containers and supply chain safety materially influence landed costs. Manufacturers with in‑house transportation and stable warehousing enjoy margin advantages in large‑scale contracts.
Supply‑side constraints and risk vectors
PAA production is sensitive to upstream raw materials, process safety requirements, and specialized manufacturing know‑how. Two operational realities deserve particular attention:
- Upstream feedstocks and production configuration: The economics of PAA depend on reliable access to hydrogen peroxide and acetic precursors plus reaction systems that manage heat and decomposition risk. Changes in peroxide availability or price can compress margins quickly for non‑integrated producers.
- Safety engineering and capacity scalability: At higher concentrations, industry best practice requires explosion‑proof equipment and stringent process controls. That raises the marginal cost of scaling capacity and shifts the competitive advantage toward players with modern assets or the capital to retrofit older plants.
Regulatory and safety landscape
The regulatory environment is a double‑edged sword: recent formal recognition of certain PAA production routes under European biocidal frameworks has reduced some market uncertainty, but it also imposes strict approval criteria that extend time‑to‑market. At the same time, product registrations remain mandatory under major health agencies for use as sanitizers and disinfectants in food and healthcare settings — compliance is table stakes.
From a safety perspective, industry guidance continues to emphasize that handling higher‑strength PAA necessitates explosion‑rated equipment and specialized storage. These compliance realities inform capital planning, contract length negotiation, and insurance exposure assessments for both suppliers and large buyers.
Competitive landscape — who matters and why
The PAA industry combines global chemical majors, regional manufacturers, and specialized formulators. Key players driving technology, scale, and channel access include legacy chemical producers with peroxygens portfolios and smaller, integrated players that combine production with logistics and application engineering. Notable industry participants include established global producers that offer solution and distilled grades across multiple applications, regionally focused manufacturers serving food and water markets, and specialty providers offering automated handling or formulation services.
Strategically, firms distinguish themselves along several axes:
- Product scope and purity: High‑purity and distilled grades command technical premium and target industrial/technical applications; stabilized, application‑specific formulations target hygiene and animal husbandry markets.
- Vertical integration: Firms controlling transportation, blending, and packaging lower working‑capital requirements and improve service levels for large buyers.
- Technical services and channel depth: Suppliers that bundle application support, dosing technology, and regulatory documentation win relational contracts in food, healthcare, and municipal procurement.
Recent industry moves to monitor
Market activity in 2025–2026 highlights product innovation and regulatory developments that will shape competitive positioning. For example, a mid‑2025 launch of a high‑strength PAA solution targeted at municipal wastewater operators demonstrates suppliers’ attention to infrastructure markets where efficacy and handling efficiency drive procurement decisions. Simultaneously, recent EU decisions clarifying approved production chemistries underline the strategic importance of regulatory engagement and compliance roadmaps.
What PW Consulting’s full report delivers (practical components)
PW’s full Peracetic Acid (PAA) Market report goes beyond high‑level narrative to provide operationally actionable resources for 2026 decision cycles. Highlights include:
- Demand and supply forecasting model with base‑case and alternative scenarios through 2032 — downloadable model for client use.
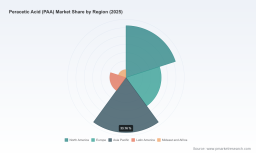
- Segment‑level analysis and buyer profiles that translate performance metrics into go‑to‑market tactics (note: detailed segment and regional breakdowns are reserved for the full report).
- Competitive benchmarking and capability mapping across production, logistics, and application services.
- Regulatory impact matrix and rollout timetables for major jurisdictions, including recommended regulatory engagement approaches.
- Capex and operational due‑diligence checklist for greenfield expansion, brownfield retrofit to higher‑concentration capacity, and contract manufacturing arrangements.
- Playbooks for commercial leaders: tender response templates, risk‑adjusted pricing frameworks, and service‑based contracting options for large end‑users.
Strategic recommendations for 2026 leaders
Executives preparing budgets and strategy for 2026 should prioritize a short list of high‑impact moves that address both opportunity capture and downside protection:
- Lock in regulatory and product registrations early. Obtain or validate required approvals before committing to large‑scale production or major market launches — regulatory lag is a predictable timing risk that erodes first‑mover advantages.
- Assess and, where necessary, shore up safety and storage investments. If your product strategy contemplates higher‑strength offerings, build robust capital estimates for explosion‑proof upgrades and insurance implications into project IRR models.
- Pursue vertical integration selectively. For mid‑to‑large volume contracts in sanitary water and industrial customers, integrated manufacturing + logistics providers can underprice outsourced suppliers when transport and handling costs are material.
- Differentiate through service. Technical application support, dosing systems, and bundled regulatory dossiers reduce buyer switching and support premium pricing where performance or compliance matters.
- Consider bolt‑on M&A to secure feedstock reliability or to add specialized formulation capabilities — given the market’s moderate concentration, targeted acquisitions can be an efficient way to buy scale or market access without engaging top‑tier global players head‑on.
How to use this intelligence in 90 days
For 2026 planning cycles, we recommend a three‑step tactical program that leverages the full PW study:
- Week 1–4: Run our downloadable sensitivity model against your cost base to stress test margin outcomes under different feedstock and logistics scenarios.
- Month 2: Align regulatory and operations teams on a prioritized register of approvals, packaging standards, and plant upgrades that must be in place to meet your target segments.
- Month 3: Execute targeted outreach — partner talks, supply contracts, or acquisition diligence — informed by the report’s supplier capability matrix and commercial playbooks.
Concluding note — why this matters for 2026
PAA is no longer a marginal disinfectant. The convergence of strengthened hygiene mandates, clarified regulatory pathways, and predictable operational constraints creates an environment where strategic foresight will determine competitive winners. Companies that combine regulatory readiness, operational resilience, and service‑led commercial models will capture disproportionate value as the market grows at an 8.5% CAGR into 2032.
PW Consulting’s full Peracetic Acid Market report contains the empirical datasets, segment maps, and actionable playbooks needed to convert this macro outlook into executable 2026 decisions. Contact PW Consulting to access the complete study and the interactive forecasting model that underpins our recommendations.
For detailed analysis of this topic, please visit the official page: Peracetic Acid (PAA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com