

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Microplate Readers Market Set for 7.5% CAGR Through 2032 — PW Consulting

Microplate Readers Market — 2026 Strategic Outlook (PW Consulting)
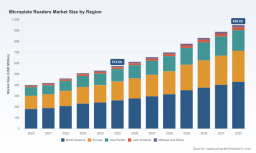
As laboratories, diagnostics providers, and life-science instrument vendors position for the next cycle of procurement and product development, clarity on trajectory, competitive intensity, and regulatory exposure is non-negotiable. PW Consulting’s Microplate Readers Market research — anchored to a 2025 base year and projecting through 2032 — provides the evidence-based perspective that senior executives and investment committees need to make decisive moves in 2026. The market is on an unmistakable growth path: expanding from roughly USD 400 million in 2020 to an estimated USD 574.7 million in 2025, and expected to approach the USD 949 million mark by 2032 at a compound annual growth rate (CAGR) of approximately 7.5%. These headline figures frame a market that is both mature in its core applications and receptive to technology-driven adjacencies.
Microplate Readers Market
Why this intelligence matters for 2026 decisions
-
Investment prioritization: The combination of mid-single-digit CAGR and recurring consumables/service revenue creates a predictable investment thesis for platform owners, OEMs, and channel partners. Our report translates macro-growth into actionable scenarios for CapEx and R&D allocation.
Microplate Readers Market -
M&A and partnership screening: The market exhibits meaningful concentration (top-three players account for over half of reported revenues, with top-five firms approaching roughly two-thirds). That degree of consolidation shapes valuation expectations and highlights acquisition targets that can deliver scale or technical differentiation.
Microplate Readers Market -
Regulatory and validation risk management: Compliance expectations (including electronic records and signatures under FDA 21 CFR Part 11 and traceable calibration aligned with ISO/IEC 17025 practices) are now table stakes for devices intended for GxP or clinical workflows. Our analysis identifies where compliance capability unlocks premium pricing and where gaps create sales friction.
-
Go-to-market optimization: As laboratories accelerate automation and move to integrated workflows, buyers increasingly value instrumentation with native automation interfaces, validation packages, and lifecycle service models. The research maps where service and software delivery are competitive levers in 2026.
Core market dynamics and technology inflections
-
Platform convergence: Readers are evolving from single-function devices toward multimodal platforms that combine absorbance, fluorescence, luminescence and time-resolved measurements, often bundled with environmental control for live-cell assays. These hybrids expand addressable use cases but also raise product development complexity and BOM cost.
-
Software and compliance as differentiators: Built-in software suites that support audit trails, IQ/OQ validation packages, and GxP-compliant record handling materially shorten procurement cycles for regulated labs. Vendors that bundle validated workflows and documentation are winning longer-term maintenance contracts.
-
Miniaturization and point-of-use innovation: Compact, automation-friendly readers designed for incubators, anaerobic chambers, and benchtop use are opening adoption in non-traditional lab settings. This trend changes the unit economics of deployments and creates adjacent sales in consumables and integration services.
-
Validation and traceability expectations: Routine use in diagnostic and regulated research environments has made traceable calibration (ISO/IEC 17025) and vendor-supported validation an operational requirement. The practical implication: procurement committees favor vendors that can demonstrate validated performance and deliver standardized validation artifacts.
Competitive landscape — what matters beyond brand names
The ecosystem is anchored by established instrument OEMs and a crop of specialized challengers. Competitive advantage is increasingly derived from three vectors: optical and detection capability; software/validation ecosystem; and delivery model (compact/portable vs. high-throughput automation). Representative vendor positioning:
-
Molecular Devices — Strong in multi-mode platforms that marry tunable monochromators with hybrid detection modes and live-cell environmental control. Their emphasis on GxP-compliant software and integrated validation support makes them a go-to for regulated discovery workflows. Recent product refreshes signal continued investment in multi-omics compatibility and higher sensitivity detection.
-
Tecan — Differentiates with live-cell imaging capabilities and a clear compliance play (IQOQ validation bundles). Their portfolio appeals to labs seeking image-driven cytometry integration alongside classic plate-reader assays.
-
BMG LABTECH — A specialist manufacturer with a focused product line and deep assay-compatibility features (e.g., TR-FRET, NanoBRET). Their software-centric approach supports regulated environments and high-fidelity data capture.
-
Agilent (BioTek) — Post-acquisition, the combined footprint strengthens automation integration and high-throughput screening capabilities — a strategic imperative for CROs and large pharma.
-
Revvity, Promega, Bio-Rad, PerkinElmer — Each of these players leverages core strengths (assay portfolio, diagnostics workflows, ELISA expertise, HTS imaging) to defend specific verticals. Their success shows the value of tight assay–instrument alignment.
-
Cerillo — Represents the edge of innovation: compact, application-focused readers designed for constrained environments and automation compatibility. New product launches signal growing demand for low-footprint solutions.
Recent product activity illustrates where innovation dollars are flowing. Incumbents continue to layer advanced optics, dual-injector kinetics, and environmental control into flagship platforms, while smaller entrants focus on portability and ease-of-integration. Those tactical differences map cleanly to customer segments — high-throughput screening vs. bench-level routine assays vs. incubator/automation use cases.
What the PW Consulting report delivers (practical content snapshot)
-
Market sizing and forecast model (2020–2032) with scenario analysis to test alternative adoption curves and sensitivity to pricing and consumable penetration.
-
Competitive scorecards and capability matrices that benchmark optical performance, detection modes, software/compliance readiness, and automation interfaces — designed for RFP and vendor selection use.
-
Regulatory and validation playbook: step-by-step documentation templates for IQ/OQ execution, recommended calibration cadences, and traceability checklists aligned to ISO/IEC 17025 and FDA 21 CFR Part 11 expectations.
-
Commercial models: channel strategies, pricing elasticity analysis, service and consumable revenue forecasts, and go-to-market playbooks for OEMs and distributors.
-
Capital and M&A intelligence: valuation frameworks, buyer archetypes, and prioritized target lists for bolt-on acquisitions or technology partnerships.
-
Client-ready artifacts: executive briefings, board-ready slides, and an interactive data pack for ad hoc modeling.
Note: This introduction intentionally highlights the structure and utility of our deliverables while withholding proprietary segmentation tables and drilldowns reserved for the full report. The approach is deliberate — to give you the strategic vantage while inviting the deeper, transaction-grade analysis behind our models.
How to use this intelligence in 2026 — pragmatic next steps
-
For OEMs: Prioritize investment in software/compliance stacks and modular hardware interfaces. Allocate R&D to improve signal-to-noise for multimodal assays and reduce BOM costs for compact variants. Use our scenario model to size payback for instrument-as-a-service offerings.
-
For distributors and system integrators: Build validation and IQ/OQ services as a revenue stream. Bundle automation integration services and consumables to lock in recurring revenue and shorten procurement cycles.
-
For clinical labs and CROs: Standardize procurement specifications to include validation artifacts and software audit capabilities. Use our TCO models to compare total lifecycle cost between compact readers and high-throughput platforms.
-
For investors and M&A teams: Focus on targets that either expand serviceable addressable market (e.g., portable instrumentation, automation adapters) or close critical capability gaps (e.g., validated software, environmental control). Our CR3/CR5 concentration analysis helps calibrate acquisition premiums.
Conclusion — strategic openness, tactical confidentiality
The microplate readers market presents a compelling mix of steady growth and targeted disruption. With a solid macro trajectory (CAGR ~7.5% from a 2025 base), meaningful concentration among established players, and active innovation at the edges, 2026 will be a year where execution on product differentiation, compliance readiness, and service models determines market share movements. PW Consulting’s full report converts this strategic perspective into executable programs — from vendor selection scorecards to M&A playbooks and validated procurement templates.
For executives building strategy in 2026, this research is the bridge between industry noise and operational decisions. Access the complete intelligence pack to unlock the detailed segmentation, vendor-level financial modeling, and the transactional datasets that are intentionally withheld from this preview.
For detailed analysis of this topic, please visit the official page: Microplate Readers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com