

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: fNIRS Market to Reach USD 417.64M by 2032 at 7.86% CAGR

fNIRS Brain Imaging Systems: Strategic Outlook and 2026 Decision Playbook
Executive trailer
As PW Consulting’s lead industry analyst, I present a concise yet strategically rich preview of our full fNIRS Brain Imaging System Market study. This briefing distills the structural forces, regulatory inflection points, competitive moves, and near-term opportunities that will shape executive decisions in 2026. We reveal the market’s trajectory at the aggregate level — while intentionally withholding granular regional/application splits and proprietary model outputs to encourage access to the full dossier.
fNIRS Brain Imaging System Market
Why this study matters for 2026 decisions
-
Timing: The fNIRS space is moving from a specialist research tool toward higher-volume clinical and applied deployments. Strategic bets made in 2026 will determine who captures the next wave of adoption.
fNIRS Brain Imaging System Market -
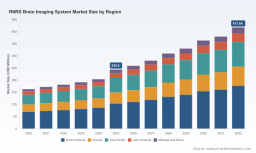
Predictability: Our model shows a clear, sustained expansion across the forecast window (2026–2032) at a compound annual growth rate of 7.86%, underpinning capital allocation, R&D prioritization, and partnership strategies.
fNIRS Brain Imaging System Market -
Risk calibration: Regulatory and standards convergence — including imminent updates to IEC norms and the first MDR-compliant portable approvals in Europe — introduces both opportunity (path-to-market clarity) and execution risk (compliance cost and timing).
Market trajectory at a glance
At the market level, fNIRS system revenues have risen steadily through the 2020–2025 historical window and are projected to continue expanding through 2032. The base year for our analysis is 2025, and our forecast period runs 2026–2032. These dynamics reflect broadening use-cases (research → clinical → applied BCI/VR integrations), falling unit costs for optoelectronics, and improved signal-processing platforms that make fNIRS practically deployable outside specialized labs.
Concentration and competitive structure
The market remains moderately fragmented: the three largest participants account for roughly a quarter of market revenue, and the top five capture a little over one quarter. That concentration profile signals a landscape where specialist innovators and niche hardware/software integrators can still scale meaningfully, and where targeted consolidation or distribution partnerships can shift competitive balance quickly.
Who to watch — competitive highlights
-
Artinis Medical Systems (Elst, Netherlands) — Known for wearable and portable device families, including CE-MDR-certified medical-class offerings for clinical research and bedside applications. Strategic strength: regulatory traction in Europe and a clear clinical product roadmap.
-
NIRx Medical Technologies (Berlin/Orlando) — Offers both lab-focused and wearable lines, with a track record in multi-modal integration (EEG/fMRI/BCI). Notable 2025 moves include a physiological sensing extension released in April 2025 and a July 2025 strategic partnership with Artinis to accelerate platform innovation.
-
Shimadzu Corporation (Kyoto, Japan) — Established instrument manufacturer with lab (LABNIRS) and portable (LIGHTNIRS) offerings; it is active on regulatory fronts, including submissions targeting PMDA pathways for diagnostic use-cases.
-
BIOPAC Systems, Inc. (Goleta, USA) — Focused on integrated whole-head fNIRS+EEG solutions for continuous monitoring and research workflows.
-
Hitachi Medical Corporation (Tokyo, Japan), Soterix Medical (New York, USA), CortiVision (Poland), Gowerlabs (UK), ISS, Inc. (USA), and TechEn, Inc. (USA) — each brings differentiated strengths across high-density systems, VR/BCI compatibility, frequency-domain instruments, and clinical-grade topography.
Regulatory and standards landscape — read this before you launch
-
Standards: The IEC 80601-2-71 update is in its final production stages; it will materially change device safety and performance expectations. Vendors should align product development and verification plans to anticipated new test vectors and documentation demands.
-
European regulation: The first portable fNIRS device cleared under EU MDR has shifted the risk–reward calculus for clinical deployment in Europe. This creates a near-term commercial advantage for firms already compliant with MDR requirements.
-
National pathways: Shimadzu’s PMDA submission for fNIRS-based psychiatric diagnostics signals that national regulators are receptive to new neurodiagnostic paradigms — but national approvals will require rigorous clinical evidence, endpoint clarity, and human factors validation.
-
Labeling nuance: Several major vendors continue to position key platforms as “For Research Use Only.” This creates a bifurcated market — research-grade systems versus medical-grade platforms — with separate regulatory and commercialization strategies required for each track.
Core report contents — what you get (practical and actionable)
-
Top-line market sizing and validated demand curves (historical 2020–2025, forecast 2026–2032), including sensitivity analyses under alternative adoption and reimbursement scenarios.
-
Go-to-market playbooks tailored to vendor archetypes: pure-play hardware OEMs; software/AI analytics providers; hospital systems & clinical networks; consumer/BCI integrators.
-
Commercial models and pricing heuristics: channel economics, average selling price dynamics, and device-as-a-service vs. capital sale tradeoffs.
-
Regulatory roadmap templates: gap assessments against IEC and major regional device regulations, plus prioritized clinical evidence strategies to accelerate PMDA/CE/US pathways.
-
Partnering and M&A thesis: target profiles, valuation multiples observed in adjacent neurotech transactions, and scenarios where consolidation materially alters market share dynamics.
-
Buyer cohort segmentation and adoption barriers: hospital buyers, translational research labs, neurorehabilitation clinics, and BCI/VR integrators — with tailored value propositions and pilot-to-scale templates.
-
Technology risk matrix: optical hardware, signal processing/AI, motion artifact mitigation, and multimodal integration risk ratings with recommended mitigation investments.
Strategic playbook for 2026
-
For hardware OEMs: prioritize modularity and software-defined differentiation. Invest in flexible probe architectures and open APIs so your device can serve research, clinical pilots, and applied BCI partners without multiple hardware SKUs.
-
For software and analytics providers: focus on artifact cleaning, physiological confound separation, and clinically interpretable biomarkers. Partner aggressively with hardware vendors that expose raw data access to accelerate algorithm training and validation.
-
For investors: the moderate concentration indicates abundant scope for roll-up strategies and bolt-on analytics. Look for companies with MDR/PMDA-ready documentation or clear, fundable clinical evidence plans.
-
For hospital systems and clinical adopters: run staged pilots that emphasize workflow integration, reimbursement mapping, and health-economic evidence. Early adopters that can demonstrate improved clinical decisions or throughput will capture durable adoption advantages.
-
For public research consortia and labs: insist on interoperability standards in procurement to ensure long-term data harmonization and downstream clinical translation.
Timing, investment, and risks
Entering or expanding in the fNIRS space in 2026 requires three synchronized moves: accelerate compliance readiness (standards and regional regulation), demonstrate differentiated clinical value through robust studies, and secure partnerships that bridge lab-to-clinic (or research-to-BCI/commercial use). Key risks include regulatory delays, slower-than-expected clinical adoption cycles, supply-chain bottlenecks for optoelectronics, and rapid commoditization of low-cost wearables that compress margins.
What we intentionally withhold (and why)
To preserve the business value of the full study, this preview omits granular regional and application revenue splits, detailed pricing matrices, and proprietary company-level market-share tables. These items are included in the full report and interactive dashboards, which also contain scenario models, downloadable datasets, and prioritized action templates for 2026 execution.
Call to action
If your 2026 strategic plan depends on making defensible choices about product roadmaps, regulatory investment, or M&A in the neurotech space, the full PW Consulting fNIRS Market report delivers the operational detail and decision-ready models you need. Contact our research desk to access the complete study, including interactive segmentation, vendor scorecards, and customizable adoption scenarios.
— PW Consulting, Senior Strategy & Industry Analysis
For detailed analysis of this topic, please visit the official page: fNIRS Brain Imaging System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com