

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Synthetic Pyrethroids Market to Reach USD 289.0M by 2032 at 4.4% CAGR

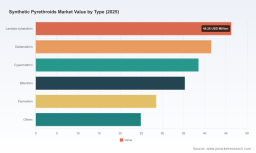
Synthetic Pyrethroids Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused introduction to our full Synthetic Pyrethroids Market study. This briefing exposes the structural signals that will shape competitive advantage in 2026 while deliberately withholding granular sub‑segment figures so that executives must consult the full report to capture the tactical details needed for execution.
Synthetic Pyrethroids Market
Market snapshot: what senior teams need to know
The synthetic pyrethroids market stands at a pivotal inflection. After a steady recovery through the early 2020s, the market reached an estimated USD 215 million in our base year (2025). Our model indicates a continuation of moderate, but structurally supported expansion, with a compound annual growth rate (CAGR) of approximately 4.4% across the 2026–2032 forecast period, taking the market to an estimated aggregate in the high two‑hundreds by 2032.
Synthetic Pyrethroids Market
Two implications for 2026 planning are immediate. First, this is not a hyper‑growth environment; instead it's one of stable enlargement where disciplined portfolio choices and efficiency gains deliver disproportionately high returns. Second, the market remains moderately consolidated: the top three firms account for roughly 45% of demand and the top five about 55%. These concentration metrics mean market power resides with a handful of global and regional players, but there remains meaningful room for nimble specialists and differentiated formulations to capture pockets of margin expansion.
Synthetic Pyrethroids Market
Structural drivers and the strategic prism for 2026
-
Demand steadying around agriculture and public health: End‑use drivers remain anchored in crop protection and vector control. Growth is being fuelled more by intensity of use, resistance management cycles, and formulary switching than by massive acreage expansion. This nuance shifts the bet from land‑grab volume strategies to value capture via formulation differentiation, application efficiency, and integrated pest management (IPM) solutions.
-
Supply chain and raw material volatility: Upstream dynamics continue to influence cost and availability. Recent commodity tightness has highlighted the sensitivity of margins to precursor and co‑ingredient pricing, underscoring the value of backward integration, strategic contracting, and multi‑sourcing of key intermediates.
-
Regulatory intensity and compliance cost: The regulatory frame is dynamic and increasingly granular. Recent regulatory actions in major jurisdictions have elevated ecological and human‑health screening for organophosphates and pyrethroid classes. For manufacturers, this raises both compliance costs and the strategic need to develop diversified portfolios that can tolerate regulatory churn.
Regulatory and environmental dynamics — actionable risk scenarios
Two recent regulatory shifts exemplify the risk environment: (1) selective revocations and restrictions on long‑standing pesticide chemistries in certain jurisdictions, and (2) accelerated wastewater and environmental discharge standards in parts of the EU and North America. In addition, regulatory agencies have pushed forward new ecological risk assessments for multiple pyrethroids and pyrethrins. These developments create three immediate strategic levers:
-
Scenario planning: Prepare parallel commercialization plans for “base case” regulatory timelines and for accelerated restriction timelines. Scenario playbooks should specify inventory buffers, labeling updates, and alternative product rollouts.
-
Operational compliance: Capitalize on early investments in effluent treatment, formulation containment, and residue mitigation—these reduce the marginal cost of compliance should new limits be imposed.
-
Stakeholder mapping: Formalize intensive engagement with regulators and NGOs in target markets to shape implementation details and transition timelines, converting regulatory engagement into a competitive moat.
Competitive landscape — positioning lessons from core players
Our study benchmarks leading incumbents and their strategic postures. Three archetypes emerge from the current competitive set:
-
Integrated, low‑cost producers with in‑house R&D and technicals capability. Players that control technical manufacture and formulation capture margin across the value chain and can better manage raw‑material volatility through backward integration and process optimization.
-
Global formulators with broad go‑to‑market reach who leverage brand and distribution. These firms monetize breadth of crop registrations and multi‑commodity formulations to maintain price realization and shelf presence.
-
Specialist innovators focused on seed treatment, soil insecticides, or public‑health applications. These players win through technical differentiation and regulatory agility, often commanding premium pricing for specialized formulations or application platforms.
Representative company profiles in the full report illustrate these archetypes. One established technical‑producer combines integrated technical manufacture with formulations and in‑house R&D to serve both domestic and export markets. A major agrochemical corporation leverages advanced seed and soil insecticide platforms alongside a vast crop registration registry. A global crop protection firm with a broad commercial footprint pushes specialty formulations for both agriculture and public health. Analysis of their cost structure, capability gaps, and partnership patterns informs actionable tactics for mid‑sized competitors and private equity investors considering consolidation plays.
What the full PW Consulting report delivers (operationally focused)
Our full study is designed as a decision‑making toolbox for 2026. It contains:
-
Proprietary market sizing and seven‑year forecasts (2026–2032), reconciling top‑down macro drivers and bottom‑up consumption modelling.
-
Scenario‑based regulatory impact models that quantify revenue and margin sensitivity under alternative restriction timetables and effluent standards.
-
Competitive benchmarking across technology, backward integration, formulation portfolio, and go‑to‑market footprint—highlighting capability levers that materially change EBITDA trajectories.
-
Practical commercial playbooks for pricing, channel segmentation, and switch‑incentive programs that prioritize value capture over volume alone.
-
Supply‑chain stress tests and procurement hedging strategies for key intermediates and co‑ingredients, including options for tolling, strategic stockpiles, and contract renegotiation templates.
-
M&A and partnership screening: a shortlist of candidate targets and partnership archetypes aligned to specific strategic moves—capacity addition, registration portfolios, or regional market entry.
Strategic recommendations for 2026 action plans
-
Prioritize portfolio resilience over maximal near‑term share capture. With a mid‑single digit CAGR environment, the highest‑return investments are margin protection (costs, formulation efficiency) and de‑risked registration strategies rather than aggressive capacity‑led expansion.
-
Operationalize regulatory contingency budgets. Assume that environmental and ecological reassessments could accelerate; allocate 2026 CAPEX/OPEX to treatment upgrades and alternative formulation development now to reduce time‑to‑market for compliant offerings.
-
Lock strategic raw‑material arrangements. Given upstream price episodes and intermittent supply tightness, prioritize structural contracts, tolling agreements, and multi‑sourcing pilots for critical intermediates.
-
Segment go‑to‑market by value potential, not by geography alone. Targeted investments in seed/soil applications and public‑health formulations can yield higher returns where regulatory and resistance dynamics favor pyrethroid solutions.
-
Deploy an M&A playbook focused on capability stitches—acquiring registrations, local formulation know‑how, or effluent treatment capacity—rather than simply adding volume.
Why this matters for your 2026 boardroom
2026 is a year to convert insight into structural advantage. The market’s trajectory—steady growth rather than explosive expansion—means that disciplined strategic choices will define winners. Firms that treat 2026 as a re‑anchoring year (protecting margins, de‑risking regulatory exposure, and selectively investing in differentiated formulations) will emerge with superior return profiles as the market expands modestly over the next decade.
Our full Synthetic Pyrethroids Market report delivers the granular inputs, risk maps, and prioritized initiatives your executive team needs to turn strategy into execution. The summary above identifies the levers; the comprehensive study provides the data, models, and playbooks required to operationalize them.
Next step
For access to the complete forecast tables, segmented demand analytics, competitor scorecards, and the tactical playbooks referenced here, consult the full PW Consulting report. The detailed intelligence reveals the exact sub‑segment dynamics and financial sensitivities necessary for transaction diligence, portfolio rebalancing, and 2026 budget allocation—information we have intentionally withheld in this briefing to preserve strategic value for our clients.
For detailed analysis of this topic, please visit the official page: Synthetic Pyrethroids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com