

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chlor-alkali Ion Exchange Membrane Market to Reach USD 656.69M by 2032 (3.5% CAGR)

Chlor‑Alkali Ion Exchange Membrane Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present a concise, decision‑focused primer to orient executives, investors and procurement leaders confronting the Chlor‑alkali ion exchange membrane market as they plan for 2026. This is a trailer: we surface the structural signals, competitive moves, regulatory inflection points and practical levers that will determine winners and losers — while reserving the granular, transaction‑ready tables and segment micro‑data for the full study.
Chlor-alkali Ion Exchange Membrane Market
Why this market matters to 2026 strategies
The membrane segment serving chlor‑alkali electrolysis and adjacent electrochemical applications is modest in absolute size but strategically outsized. After a steady expansion during 2020–2025, the market reached an estimated USD 518.4 Million in our 2025 base year and is forecast to grow at a compound annual growth rate (CAGR) of approximately 3.5% through the 2026–2032 horizon. Under our baseline scenario, this trajectory takes the industry from roughly USD 541 Million in 2026 toward a mid‑to‑upper six‑hundred million dollar range by the early 2030s.
Chlor-alkali Ion Exchange Membrane Market
That steady growth masks high strategic volatility: small shifts in membrane adoption, technology substitution, or regulatory policy can materially alter plant economics and vendor positioning. For corporations that depend on continuous and predictable electrolytic production — whether for chlorine/caustic, green hydrogen, or desalination — membrane selection is both an operational and strategic decision. The 2026 planning cycle is therefore a moment to translate directional market signals into procurement, R&D and portfolio moves that deliver durable advantage.
Chlor-alkali Ion Exchange Membrane Market
Three high‑impact strategic themes for 2026
-
1) Transition risk and retrofit opportunity
The industry is in the tail of a global regulatory wave that accelerated plant closures and technology swaps. The enforcement of international environmental conventions accelerated the retirement of legacy mercury‑based cells, consolidating demand toward modern membrane and diaphragm technologies. That transition created an immediate retrofit market for membranes — and a longer‑term replacement cycle as plants convert or optimize operations. For firms evaluating capex in 2026, there is a near‑term window to lock favorable supply terms for membrane inventory and to secure upgrade projects that will run for the next decade.
-
2) Technology differentiation is concentrated and enduring
Perfluorinated ionomers and engineered membrane architectures remain the performance standard for low‑energy, long‑lifetime operation in chlor‑alkali electrolysis. A small set of suppliers with deep materials know‑how and validated plant references continue to capture a disproportionate share of premium projects. Market concentration metrics indicate a top‑tier cluster that holds meaningful pricing and specification influence — enough that buyers should treat vendor relationships as strategic assets rather than transactional purchases.
-
3) Adjacent demand vectors: hydrogen and water electrochemistry
Water electrolysis for hydrogen production and advanced water treatment use cases create a higher‑growth adjacent addressable market. While these segments do not eclipse core chlor‑alkali demand in the near term, they change the product roadmap and R&D priorities for membrane suppliers. Organizations planning 2026 supply chains should assess dual‑use membrane specifications and negotiate development partnerships that preserve optionality across industrial and energy applications.
Implications for corporate action in 2026
-
Procurement and Inventory
With growth steady but supply risk asymmetric (concentrated know‑how, limited high‑quality fluoropolymer capacity), 2026 is the year to move from juste‑à‑temps purchasing to strategic buffer positioning. That includes multi‑year frameworks with top‑tier vendors, conditional buy‑options tied to plant modernization schedules, and supplier development clauses to share risk on raw material price shocks.
-
R&D and Technical Partnerships
Buyers should prioritize technical alliances that shorten pilot timelines for alternate membrane chemistries and recyclability pathways. Collaborative development agreements — including co‑funding for scale‑up — reduce time‑to‑qualification and capture first‑mover advantages when new low‑cost or lower‑carbon membranes prove viable.
-
M&A and Joint Ventures
The moderate market concentration suggests room for bolt‑on consolidation and strategic joint ventures, particularly at the intersection of membrane manufacturing and system integration (cell frames, stack components). Corporates with downstream exposure to electrolysis should size potential acquisitions against their ability to integrate production know‑how and protect IP.
-
Regulatory and ESG Positioning
Regulatory momentum around hazardous materials and lifecycle emissions is not optional. Firms that preemptively map membrane lifecycle footprints, support end‑of‑life recovery and provide transparent material provenance will have a procurement advantage with both public buyers and large industrial customers aligning to net‑zero targets.
Competitive landscape — what matters beyond logos
The market is served by a small set of established technology leaders and regional champions. Three profiles merit specific strategic attention:
-
Asahi Kasei Corporation (Tokyo, Japan)
Asahi Kasei’s Aciplex™ membranes and its decades of electrolysis system experience position the company as a turnkey supplier for large chlor‑alkali operations. Its manufacturing footprint and long plant track record reduce execution risk for large retrofit projects. A recent capacity expansion announced in October 2025 — aimed at producing cell frames and membrane components for both chlor‑alkali and alkaline water electrolysis — is a clear signal that Asahi Kasei is pursuing cross‑application scale. Strategic takeaway: suppliers expanding integrated manufacturing are likely to strengthen negotiation position on comprehensive bids; buyers should require roadmap commitments and capacity reservation terms in new contracts.
Reference: Asahi Kasei Official Press Release, Oct 2025 — https://chlor-alkali.asahi-kasei.co.jp/en/
-
The Chemours Company (Wilmington, Delaware, USA)
As the originator of a leading perfluorinated cation‑exchange membrane technology, Chemours supplies a performance benchmark that many operators still adopt for high‑duty applications. Its long commercial history and extensive deployment references provide buyers with reduced technical risk and easier validation pathways. Strategic takeaway: legacy technology providers command premium positioning on high‑stability contracts; use warranty and life‑cycle service commitments to align supplier incentives.
Reference: Chemours Nafion™ membranes — https://www.nafion.com/en/products/chlor-alkali-membranes
-
Dongyue Group Co., Ltd. (Zibo, Shandong Province, China)
Dongyue and other regional manufacturers are increasingly important for domestic substitution and cost‑sensitive projects. Their role is especially material where localized environmental regulation and procurement preferences favor domestic supply. Strategic takeaway: global buyers should evaluate regional sourcing to manage total landed cost and political/regulatory risk, while protecting qualification standards through performance‑based contracting.
Reference: Dongyue Group — https://www.dongyuechem.com/en/index.html
Market structure and competitive intensity
Concentration metrics indicate a market where the top three and top five suppliers control a meaningful share of business — enough to influence price dynamics, product roadmaps and qualification hurdles. This structural reality favors established producers on high‑value projects, while leaving room for entrants that bring differentiated chemistry, cost profile or captive end‑market access.
What the report delivers — practical contents for 2026 action
Our full Chlor‑alkali Ion Exchange Membrane Market study is structured to be a working tool for commercial, technical and corporate strategy teams. Highlights include:
- Methodology and scenario forecasts (2026–2032) with sensitivity stress tests for raw material cost, retrofit pace and regulatory changes.
- Plant‑level demand modelling and procurement timetables to align membrane deliveries with conversion projects.
- Supply chain heat maps identifying critical raw material dependencies, lead times and near‑term capacity constraints.
- Price and margin analysis across membrane chemistries, including landed cost models for cross‑regional sourcing.
- Vendor scorecards and a negotiated supplier playbook — contract terms, KPIs, warranty structures and service‑level expectations.
- M&A target screening, integration risk checklists and valuation sensitivities for bolt‑on plays.
- Regulatory intelligence and ESG compliance checklists, mapped to operating jurisdictions and expected 2026 policy changes.
- Actionable 90‑, 180‑ and 360‑day plans for procurement, engineering and investor relations teams.
Limits and where to go for the full intelligence
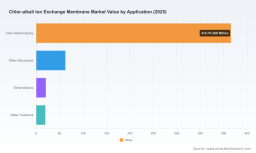
This overview intentionally omits the granular region, application and type‑level allocations that underpin project‑level decisions. The full report contains those segmented tables, plant‑by‑plant demand curves, vendor‑specific shipment histories and downloadable models that enable contract modelling and bid optimization. If you are designing capital programs, negotiating multi‑year membrane contracts, or evaluating M&A in 2026, you will need that micro‑data to convert these strategic directions into defensible financial commitments.
Closing recommendations for 2026
- Embed membrane supply risk into capital planning: assume modest growth (c. 3.5% CAGR) but asymmetric supplier leverage.
- Prioritize strategic partnerships with technology leaders while preserving regional sourcing flexibility.
- Accelerate technical validation pilots for dual‑use membranes targeting both chlor‑alkali and water electrolysis applications.
- Require supplier commitments on capacity reservation and lifecycle services during contract negotiations.
PW Consulting’s full Chlor‑alkali Ion Exchange Membrane Market report equips you with the missing granular analysis and executable templates to operationalize the above recommendations. For access to the models, segment breakouts and supplier scorecards referenced in this brief, please consult the complete study.
For detailed analysis of this topic, please visit the official page: Chlor-alkali Ion Exchange Membrane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com