

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: TCS market set to reach USD 7,100M in 2025; 8.7% CAGR (2026–2032)

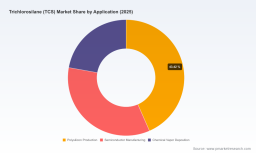
Trichlorosilane (TCS) Market: Strategic Outlook for 2026 Decision‑Making
Executive preview
The Trichlorosilane (TCS) market has entered a phase of renewed structural growth that will disproportionately shape capital allocation and supply‑chain strategies in 2026. After expanding from approximately USD 3,950 Million in 2020 to about USD 7,100 Million in the base year 2025, the market is forecast to continue its upward trajectory through the 2026–2032 horizon at a compound annual growth rate of 8.7%, reaching an estimated USD 12,660 Million by 2032. This trajectory is being driven by intersecting dynamics in polysilicon feedstock demand, semiconductor capacity rebuild and localization, technology shifts in chlorosilane manufacture, and intensifying regulatory and geopolitical constraints.
Trichlorosilane (TCS) Market
Why this report matters for executive choices in 2026
-
Timing capital projects. The pace and shape of the forecast create a narrow window to green‑light expansions or pivot existing assets for electronic‑grade production. The analysis in our study provides scenario‑calibrated timing for capex deployment that reconciles demand growth with regulatory lead times.
Trichlorosilane (TCS) Market -
Where to locate capacity. Reshoring of semiconductor production, regional PV industry cycles, and local regulatory regimes have changed the calculus for geography selection. Our work maps the trade‑offs among cost, regulatory compliance, and access to offtake partners without exposing the granular regional splits in this summary.
Trichlorosilane (TCS) Market -
Supplier and technology strategy. Low‑carbon, energy‑efficient manufacturing pathways—most notably fluidized bed reactor (FBR) approaches—are now meaningful levers for cost and ESG differentiation. Companies that select the right technology and secure feedstock pathways earlier will capture outsized margin expansion.
-
Commercial and contractual design. With price indices showing notable short‑term volatility across regions in 2025, procurement strategies that combine indexed pricing, strategic inventory, and long‑term offtake agreements will outperform spot‑heavy peers.
Core market dynamics shaping 2026 decisions
-
Demand drivers. Growth is concentrated in polysilicon feedstock demand and replenishment cycles in semiconductor fabs, amplified by capacity projects and technology transitions that require stricter material specifications. These drivers underpin the mid‑ to long‑term CAGR and create differentiated demand pockets for electronic‑grade versus solar‑grade product streams.
-
Supply innovations and cost disruption. The 2025 startup of FBR‑based production and the commercial roll‑out of advanced purification facilities have already begun to shift cost and carbon curves. One notable FBR start reduced energy consumption by roughly 60%, altering the unit economics for new entrants and influencing incumbent reinvestment choices.
-
Price behavior and market signals. Regional price indices in 2025 demonstrated meaningful dispersion—North America recorded a sharp quarter‑over‑quarter increase in mid‑2025, while Asia‑Pacific and China showed more modest quarter‑over‑quarter rises with differing baseline price levels. These signals point to tightness in certain regional supply chains and the potential for arbitrage and logistics‑led margin capture.
-
Regulatory and geopolitical friction. Environmental testing regimes and transportation controls (e.g., REACH‑related reporting obligations in Europe and heightened scrutiny on chlorosilane handling) are raising compliance overheads and, in some cases, creating temporary production disruptions. Geopolitical tensions are increasing the cost and complexity of cross‑border supply and are a primary scenario variable for capacity siting decisions.
Competitive landscape — capabilities that matter
The TCS market remains moderately concentrated, with the top few producers accounting for a material share of global capacity. This structure gives scale players advantages in feedstock integration, purification infrastructure, and long‑term offtake relationships with polysilicon and semiconductor customers. At the same time, recent moves by incumbents and new entrants have introduced points of competitive differentiation that matter for 2026 strategy.
-
Tokuyama Corporation (Tokyo) — Focused on ultra‑high‑purity TCS for semiconductor applications and actively co‑developing product specifications with key chipmakers. Their close customer integrations and containerized supply solutions reduce lead‑time risk for electronic‑grade applications.
-
Wacker Chemie AG (Munich) — Recently commissioned an electronic‑grade purification facility in Europe to support localized semiconductor supply chains. This move underscores the strategic premium on in‑region purification and traceability for advanced fabs.
-
Shin‑Etsu Chemical (Tokyo) — Leverages vertical capabilities across silicon intermediates and electronic materials. Their breadth across material flows provides integration advantages in matching quality, availability and regulatory compliance for PV and chip customers.
-
OCI Company Ltd. (Seoul) — Expanded capacity in Southeast Asia in 2025, reinforcing a regional supply play to capture polysilicon feedstock demand and offering a durable hedge against regional logistics constraints.
-
Hemlock Semiconductor (Michigan) — Signed long‑term offtake supply arrangements with major solar manufacturers and is executing localized production agreements to de‑risk logistics and shorten time to market in the U.S.
-
GCL‑Poly Energy (Beijing) — Brought an FBR‑based plant online in 2025 with significant energy advantages, exemplifying how new process technology can rapidly alter competitive positioning on both costs and sustainability credentials.
What the PW Consulting report delivers (operational, decision‑grade content)
-
Base and forecast market sizing (2020–2025 historical; 2026–2032 forecast) with scenario variants and sensitivity to throughput, yield and feedstock prices.
-
Price‑index analysis and short‑term trajectory models by major shipping hubs, with tools to convert indices into procurement cost projections.
-
Supplier scorecards — capabilities, geographic footprint, purification technology, ESG footprint, and counterparty risk assessment — built for rapid RFP and sourcing decisions.
-
Technology briefings on FBR, advanced purification, and handling/packaging innovations; capex/opex models and ROI calculators for retrofit versus greenfield scenarios.
-
Regulatory playbook: compliance timelines, testing and reporting checklists (including EU REACH implications), permitting risk matrices, and mitigation pathways.
-
Commercial templates: long‑term offtake agreement structures, indexed pricing models, hedging approaches and inventory optimization heuristics tailored to TCS supply characteristics.
-
M&A and partnership pipeline analysis with valuation frameworks reflecting concentration dynamics and strategic synergies.
-
Case studies and actionable entry/exit decision rules for executives considering expansions, divestments or vertical integration.
Risks, near‑term triggers and scenario framing
-
Regulatory enforcement spikes can create localized capacity reductions and shift trade flows; REACH‑related testing backlogs were already implicated in production interruptions in 2025.
-
Raw material and logistics volatility remain a core earnings risk; regional price index moves in 2025 highlight how swiftly feedstock economics can oscillate.
-
Technology adoption risk — incumbents face retrofit versus replace tradeoffs when considering energy‑efficient FBRs; timing influences competitive position and stranded asset exposure.
-
Geopolitical fragmentation could accelerate localization but raise incremental capex and operating costs for duplicated assets across markets.
Practical strategic recommendations for 2026
-
Prioritize offtake hedges and long‑term contracts with built‑in escalation and quality clauses to secure feedstock needs while preserving flexibility to capture upside from price appreciation.
-
Fast‑track investments in purification capacity or strategic partnerships with players that have in‑region purification capabilities to win semiconductor supply chains being localized across Europe and North America.
-
Evaluate FBR adoption or JV approaches to access low‑energy production routes. Even partial conversion can meaningfully lower life‑cycle emissions and unit costs over a 5–7 year horizon.
-
Build a compliance‑first governance layer to absorb regulatory complexity: a cross‑functional program for testing, reporting and transport approvals will materially shorten permitting timelines and prevent avoidable stoppages.
-
Use scenario‑based capital planning: run upside, base and downside cases that incorporate regulatory shocks, regional price spreads, and technology adoption curves when sizing projects for 2026–2028 execution.
-
Monitor concentration movements: with moderate top‑end concentration, smaller innovators can capture niche premiums through service models (localized cylinders, rapid‑response supply) while scale players defend via integration and purification investments.
Conclusion & next steps
The TCS market entering 2026 presents a clear set of strategic inflection points: technology shifts (notably FBR and purification upgrades), regulatory pressure, and evolving demand from solar and semiconductor manufacturing. Executives must combine rigorous scenario analysis with tactical moves—selective capex, targeted partnerships, and procurement sophistication—to convert market growth into durable competitive advantage.
PW Consulting’s full Trichlorosilane Market study contains the complete datasets, regional and application breakdowns, supplier scorecards, and executable commercial templates referenced above. To preserve the strategic value of the research and encourage direct engagement, we have intentionally withheld granular regional and application split tables from this summary. Access the full report for the detailed matrices and downloadable financial models that will inform high‑confidence decisions in 2026.
For detailed analysis of this topic, please visit the official page: Trichlorosilane (TCS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com