

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Melamine Foam Market to Reach USD 282.6M by 2032 at 5.85% CAGR

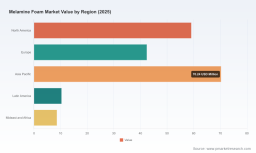
Melamine Foam Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
As companies prepare strategy for 2026, the melamine foam market presents a measured growth opportunity anchored in both retrofit-driven acoustic upgrades and new-build thermal management requirements. Our analysis uses 2025 as the base year; the market expanded from a mid-hundreds USD million footprint in 2020 to approximately USD 190.6 Million in 2025 and is modeled to reach roughly USD 282.6 Million by 2032 under a central scenario. The forecasted compound annual growth rate for the 2026–2032 window is 5.85% — a pace that favors deliberate, capability-led moves over speculative capacity bets.
Melamine Foam Market
Why this report matters for 2026 strategic choices
- Portfolio prioritization: Understand which product attributes (acoustic performance, fire retardancy, hydrophobicity, recycled content) drive price premiums and which are table-stakes for entry into regulated segments.
- CapEx and capacity allocation: Translate a steady, mid-single-digit CAGR into capacity timing and utilization strategies to avoid the twin risks of underinvestment in premium product lines and overinvestment in commoditized grades.
- Sustainability and compliance planning: Anticipate certification requirements and carbon implications for product lifecycles, which are increasingly decisive for specification in construction and transport sectors.
- M&A and partnerships: Use a granular competitor and capability map to identify bolt-on or capability-acquisition targets that accelerate entry into high-margin niches.
Report contents — practical and action-oriented
The research is structured as an operational playbook for leaders who need to convert market intelligence into executable plans. Core deliverables include:
Melamine Foam Market
- Market sizing and trend decomposition (2020–2025 historical benchmarking; 2026–2032 forecast with scenario bands).
- Demand-driver analysis by end-use and technical requirement, linking macro construction and transport indicators to foam demand curves.
- Supply-side audit: feedstock sourcing, manufacturing routes, unit-cost curves, and a mapped supplier ecosystem from resin producers to converters.
- Competitive benchmarking and capability profiles for the industry’s leading manufacturers and fabricators — technology, certification status, product differentiation, distribution models, and go-to-market footprints.
- Regulatory and standards matrix (fire safety, carbon accounting, chemical registrations), highlighting certification pathways that materially affect procurement choices.
- Commercial playbooks: pricing strategies, tender response templates, specification win themes, and product-bundling approaches tailored to construction, transport, and industrial cleaning customers.
- M&A screen and valuation sensitivities for potential bolt-ons in manufacturing, converting, and specialty product lines.
- Stress-tested scenario analyses for raw-material price spikes, carbon regulation tightening, and step-changes in specification (e.g., new fire-rating requirements).
- Appendices with primary interviews, patent landscaping, test protocols, and sample technical datasheets to accelerate buyer conversations.
Market dynamics shaping 2026 decisions
Three structural dynamics will dominate strategy conversations in 2026:
Melamine Foam Market
- Sustainability as a specification filter — Recent product introductions demonstrate the market turning from simple chemical or acoustic spec wars to lifecycle- and feedstock-aware selection. One leading producer announced a melamine foam grade produced with 100% green electricity and renewable feedstock balance, cutting Product Carbon Footprint (PCF) by up to half compared with conventional grades, and aligning the product with internationally recognized certification schemes. For purchasers and producers alike, PCF credentials and third-party certification are becoming differentiators rather than optional claims.
- Product premiumization and design integration — Suppliers are expanding beyond raw foam supply into colored, shaped, and performance-tuned formats that meet architects’ and OEMs’ aesthetic and functional requirements. The launch of a dark-colored premium foam that maintains the same technical performance is a clear signal: visual design considerations now intersect with acoustic and thermal performance in specifying materials for visible surfaces.
- Fragmented supply and targeted consolidation — Market concentration remains low, with leading firms accounting for a minority share of global volumes. That structure creates opportunities for scale-seeking acquisitions as well as for nimble specialists that can capture margin through vertical integration, fast prototyping, or certification-led differentiation.
Competitive landscape — how incumbents are positioning
The competitive field is populated by technology leaders, vertically integrated manufacturers, specialty fabricators, and regional converters. Each plays a distinct role in the value chain:
- Technology and premium brand leaders — Large chemical companies with established foam technologies occupy the premium acoustic and safety-oriented segments. Their investments in low-PCF production routes, formal safety certifications, and product variants that combine performance with design appeal create a high barrier to entry for cost-driven competitors.
- Scale-focused manufacturers — Several large Asia-based producers pursue integrated manufacturing, supplying everything from standard blocks to specialty low-compression and hydrophobic variants. Their advantages are cost efficiency, broad product portfolios, and rapid catalog expansion; they are also the primary source of volume supply for converters and OEMs.
- Specialty fabricators and niche innovators — A network of smaller firms specializes in converting base foam into engineered parts for transportation, industrial filtration, acoustic panels, and consumer erasers. Their value lies in application know-how, finishing capabilities, and localized service, making them natural partners for OEMs needing just-in-time, application-specific components.
- Adjacency players — Companies from thermal insulation, acoustic textiles, and absorbent materials are increasingly active, leveraging existing customer relationships in building and transport to offer melamine-based variants where fire performance and thin-profile insulation are required.
Recent moves underscore these dynamics. A leading European chemical firm launched an EcoBalanced line in 2025 and later introduced a dark-colored variant designed for visible interior applications — moves that protect pricing by combining sustainability credentials with design-led differentiation. A vertically integrated Asian manufacturer updated its product catalogs in mid‑2026 to include absorbent flakes, low compression sheets for sensors, hydrophobic sorbents, and passive cooling insulation — signaling rapid portfolio expansion into adjacent industrial niches.
Strategic implications: recommended actions for 2026
- Define a certification-first road map: Prioritize investment in the handful of third-party certifications that unlock specification in construction and transport segments. These certifications are becoming decision gates; allocating program budget now reduces time-to-spec in major tenders.
- Differentiate through application know-how: Compete on system value — acoustic performance plus installation labor savings, fire-safe thin insulation, or integrated sensor-support sheets — rather than on commodity €/kg metrics.
- Right-size capacity expansion: Use the report’s scenario outputs to phase capacity additions targeted at premium and specialty grades rather than undifferentiated block production.
- Pursue targeted M&A or JV to acquire missing capabilities: Look for converters with deep OEM relationships, or regional fabricators with rapid prototyping and finishing expertise, to accelerate access to high-margin channels.
- Hedge feedstock and energy risks: Supplier contracts should include indexation clauses and dual-sourcing strategies; for players targeting eco-premiums, secure renewable electricity and certified biomass feedstock paths early.
- Embed sustainability in commercial contracts: Translate PCF advantages into contractual value through carbon-linked pricing or specification guarantees that can be monetized in public tenders and corporate procurement.
Why PW Consulting’s analysis accelerates decision-making
Our market model integrates granular demand signals from construction and transport activity, primary interviews across the supply chain, and technical scoring of product grades against certification and fire-safety requirements. The result is not just a top-line forecast but a set of operational levers — pricing bands, utilization thresholds, and acquisition candidate filters — that can be converted into a 12–24 month execution plan.
To preserve the strategic advantage for subscribers, the report intentionally withholds certain granular segmentation tables and contract-level pricing that are included in the full deliverable. These withheld details are exactly the inputs procurement and corporate development teams need to finalize capital allocation and bid strategies.
Next steps
For executives preparing budgets and go-to-market plans in 2026, the full Melamine Foam Market report provides the actionable data and playbooks required to convert steady market growth into sustainable margin expansion. Access the full dataset and company appendices for detailed regional and application splits, supplier scorecards, and transaction screens that support confident investment and commercial decisions.
For detailed analysis of this topic, please visit the official page: Melamine Foam Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com