

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thermal Lamination Films Market to Reach USD 4,104M by 2032

Thermal Lamination Films Market: Strategic Primer for 2026 Decision-Makers
Why this study matters now
As companies plan capital allocation, product development, and go-to-market strategies for 2026, the thermal lamination films market presents a distinctive mix of steady demand, technology-driven premiumization, and regulatory pressure. Our PW Consulting study—anchored on a 2025 base year with historical analysis from 2020–2025 and a forward-looking forecast through 2032—translates macro momentum into actionable choices. The headline: the market is expanding at a compound annual growth rate (CAGR) of approximately 8.8%, with total global revenues moving from roughly USD 2.27 billion in 2025 toward a projected USD 4.10 billion by 2032. Those topline dynamics create both predictable growth corridors and discrete disruption risks that every executive must address in 2026.
Thermal Lamination Films Market
Market trajectory and what the numbers actually tell you
High-level market growth is not an invitation to complacency. The mid‑single‑to‑high‑single digit CAGR masks important operational realities: rising premiumization of packaging and graphic applications, intensifying sustainability requirements, and periodic raw-material shocks. Our research charts the market’s recovery and expansion path—moving from about USD 1.56 billion in 2020 to USD 2.27 billion in 2025, and showing continued acceleration thereafter to an estimated USD 4.10 billion by 2032. These aggregate figures are essential inputs into 2026 budgeting, capacity planning, and M&A screening: they define the size of the prize, the pace at which it grows, and the window for investment returns.
Thermal Lamination Films Market
Core structural drivers shaping 2026 decisions
- Premium product adoption: Brand owners and converters are increasingly specifying value‑added films—soft‑touch, anti‑scratch and anti‑fingerprint variants—driven by shelf differentiation and longer use cycles.
- Regulatory and EPR pressures: Extended Producer Responsibility schemes are accelerating demand for recyclable, durable coatings and for films that enable thinner substrate designs without compromising protection.
- Certification and food safety requirements: For food and liquid packaging applications, ISO 9001 and BRCGS-level compliance are non‑negotiable procurement requirements—raising the bar for supplier qualification and favoring established, audited producers.
- Raw-material and cost volatility: Resin price swings (PP, PE, PET) tied to oil and gas cycles translate directly into margin volatility for film manufacturers and pricing pressure for converters.
- Technology diffusion in printing: Growth in industrial and digital printing applications increases demand for films that offer print protection at higher speeds and with improved adhesion characteristics.
Competitive landscape: fragmentation, specialization, and consolidation opportunity
The market exhibits a mixed structure: a meaningful number of capable global players co-exist with a large base of regional specialists. Measured concentration shows the top three players account for under one-third of the market (CR3 ≈ 29.5%), and the top five for just over two-fifths (CR5 ≈ 41.2%). This fragmentation creates room for scale plays—both organic and acquisitive—as well as for partnerships that knit together specialty capabilities with distribution reach.
Thermal Lamination Films Market
Key strategic competitor archetypes to watch in 2026:
- Global specialty producers: Firms like COSMO Films and Polyplex combine global distribution and diversified product portfolios, positioning them to capture premium and commodity segments.
- Technology-focused premium players: Companies such as Derprosa (Taghleef Industries) and Mitsubishi Chemical emphasize differentiated products—soft-touch, anti-scratch, and sustainability-optimized films—that command margin premiums.
- Custom and performance-oriented converters: Players like Transilwrap provide tailored solutions for industrial and labeling applications, competing on flexibility and speed-to-market.
- Regional volume producers: A number of China- and India-based manufacturers prioritize cost-competitive volumes and local logistics advantages—an important consideration for capacity and price dynamics in certain markets.
Recent signals: innovation and regulatory catalysts
- Product innovation is accelerating: recent 2025 launches demonstrate the industry’s push toward films that enable recyclability and premium tactile finishes—examples include high-performance polyolefin sleeves designed for bottle-to-bottle recycling and soft-touch films with enhanced anti-scratch/anti-fingerprint properties.
- Regulatory levers are shifting buying criteria: EPR schemes and food‑packaging certification mandates are reframing supplier selection, increasing the commercial value of traceability, recyclability claims, and third-party certifications.
Strategic playbook for 2026 (five priority moves)
The following moves are engineered to translate the market’s growth and structural shifts into tangible competitive advantage within a 12–24 month horizon.
- Prioritize portfolio segmentation: Create a two-track product roadmap—(a) premium, differentiated films targeting brand owners and value chains where margin is accessible; (b) high-volume, cost‑efficient lines for price‑sensitive industrial buyers. Defer commoditized expansion unless backed by clear logistic or feedstock cost advantages.
- Lock in raw-material resilience: Implement layered procurement contracts, indexation clauses with customers, and selective hedging strategies. Scenario-model resin shocks in financial plans and embed pass‑through mechanisms in commercial contracts.
- Invest in certification and sustainability credentials: Fast-track ISO/BRCGS and EPR-compliance support for plants that feed food/liquid packaging channels. Publicize circularity initiatives and co‑develop recyclable laminate systems with brand partners.
- Build scale through focused M&A and partnerships: Target tuck‑ins that add geographic reach, specialty capability (e.g., soft-touch, anti-fingerprint), or channel access. Given CR3/CR5 levels, well‑timed consolidation can rapidly enhance market share and margin realization.
- Commercial mechanics and route-to-market: Reconfigure commercial incentives toward longer-term contracts with converters and brand owners; offer co‑development programs with price/volume guarantees to reduce adoption friction for new film technologies.
Operational levers and KPIs for 2026
- Capacity utilization and line efficiency: target incremental gains of 3–5% in OEE through quick wins (changeover reduction, preventive maintenance).
- Raw material cost-to-price lag: measure and reduce average lag days between resin price movements and customer price adjustments.
- New product adoption curve: track time-to-first-order and repeat rate for premium films—aim to convert initial pilots into multi-year contracts within 12 months.
- Certification coverage: percentage of revenue attributable to certified plants serving food/liquid market segments—move toward full coverage for prioritized sites.
What the full PW Consulting report delivers (practical components)
Our market study goes beyond topline forecasts to deliver the operational intelligence that directors and business unit leaders need to make 2026 choices with conviction. Highlights include:
- Granular market sizing and a transparent forecasting methodology (base year 2025, historical 2020–2025, forecast 2026–2032) with scenario sensitivity to resin price and regulatory uptake.
- Detailed competitive profiles, capability matrices, and M&A screens—showing where each player competes, which technologies they prioritize, and how they are positioned on sustainability metrics.
- Commercial and pricing playbooks for converters and film producers, including contract templates and pass‑through clause examples tailored to volatile feedstock markets.
- Supply‑chain stress tests and a set of hedging and inventory strategies calibrated for different corporate risk appetites.
- Actionable investment cases with IRR and payback models for capacity additions, technology upgrades, and greenfield versus brownfield expansion scenarios.
- Roadmaps for product development and certification sequencing to accelerate access to high-value food and liquid packaging segments.
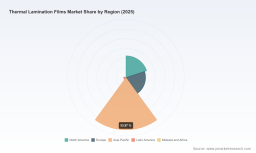
To preserve the competitive value of granular segmentation, regional and application-level splits are summarized in the full report rather than disclosed here—this article intentionally highlights strategic implications while directing decision-makers to the full dataset for tactical execution.
How to use this intelligence in boardroom conversations
Use the study’s aggregated growth curves and scenario outputs to stress-test capital allocation choices. Frame investment proposals against three clearly defined scenarios (base: steady adoption and moderate commodity inflation; upside: accelerated premium adoption and favorable resin markets; downside: sharp resin inflation and slower regulatory adoption). Quantify the sensitivity of NPV and payback to +/- 10–20% volume outcomes and to +/- 15–20% resin price swings. That level of rigor converts market enthusiasm into defensible investment decisions.
Final recommendation
In 2026, winners will be those who pair nimble operational responses to feedstock and certification pressures with deliberate moves into premium product sets and partnership-driven distribution. The market’s forecasted expansion—from an aggregate base of roughly USD 2.27 billion in 2025 toward roughly USD 4.10 billion by 2032 at an 8.8% CAGR—creates a runway for margin expansion, provided companies prioritize resilience, certification, and targeted consolidation. Our full PW Consulting report provides the segment-level maps, competitive scorecards, and financial templates to convert strategic intent into measurable outcomes. For teams drafting 2026 budgets and three‑year roadmaps, that granular intelligence will be essential.
For detailed analysis of this topic, please visit the official page: Thermal Lamination Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com