

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Oil Seal Market to Reach USD 596.37 Million by 2032 at 3.32% CAGR

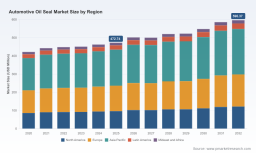
Automotive Oil Seal Market — Strategic Outlook for 2026 Decision‑Makers
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an executive introduction to our latest Automotive Oil Seal Market study. This briefing frames the report’s strategic utility for executives making capital, sourcing, product and M&A decisions in 2026. It highlights the macro trajectory, competitive dynamics, regulatory headwinds, and the actionable modules within the full study — while intentionally withholding the granular regional and application breakdowns that are included in the paid research package.
Automotive Oil Seal Market
Macro snapshot you need to know
The automotive oil seal market is stable and growing with a clear, predictable cadence. Our analysis uses 2025 as the base year and draws a validated historical series from 2020–2025, with forward projections through 2032. On a revenue basis (USD, Million), the market stands in the mid‑hundreds in the base year and is forecast to expand to the high‑five‑hundreds by 2032 under a baseline scenario. The compound annual growth rate (CAGR) for the forecast window is calculated at 3.32%.
Automotive Oil Seal Market
Why this matters for 2026 planning: the market is not in hyper‑expansion mode, but it is large and resilient. That combination favors disciplined investments — targeted capacity additions, product line optimization, and precision in supplier qualification timing rather than broad, speculative rollouts.
Automotive Oil Seal Market
What the full report delivers (practical, decision‑ready modules)
- Actionable market sizing & scenarios — Transparent methodology, historical reconciliation, and three forward scenarios (baseline, upside, stress) that support CAPEX and inventory models.
- Demand driver matrix — Component-level triggers (powertrain architecture shifts, EV/non‑EV fleet mix, duty cycles) mapped to volume and value outcomes for the period 2026–2032.
- Price & material sensitivity models — Elasticity analyses that translate feedstock swings (rubber and key elastomers) into cost of goods sold impact and margin-press scenarios for OEM and aftermarket channels.
- Supplier risk heatmap — Tiered supplier scoring across quality certifications, capacity flexibility, geographic risk, and IATF 16949 compliance timelines to prioritize strategic sourcing.
- Testing, qualification & compliance playbook — Practical checklists for endurance testing, contamination/particle limits, batch traceability and harmonized tariff considerations that affect landed costs and lead times.
- Technology & materials roadmap — Comparative assessment of elastomer chemistries, thermoplastics and metal‑composite solutions with guidance on durability, temperature endurance and manufacturability trade‑offs.
- Commercial benchmarking — Pricing buckets, contract structures, and aftermarket vs OEM margin profiles to shape commercial negotiation strategies.
- M&A and partnership decision aids — Valuation compendia for carve‑outs and capability‑seeking transactions supported by sensitivity tables and synergy levers.
Note: The full PW Consulting report contains detailed regional, application and material splits, unit volumes, and supplier scorecards. We intentionally omit those tables from this preview to preserve the research’s proprietary value.
Competitive landscape — concise strategic signals
The automotive oil seal market is moderately consolidated: leading global suppliers collectively control just under six‑in‑ten of market value, leaving room for specialized players and regional champions to sustainably compete. The competitive map is driven by engineering depth, test & validation capabilities, OEM approvals and footprint alignment with vehicle assembly and tier‑1 suppliers.
- Freudenberg Sealing Technologies (Weinheim, Germany) — Known for Simmerring® radial shaft seals and high‑performance elastomer solutions across engines, transmissions and electric drivetrains. Recent investments include a large‑ring test bench that materially expands validation capability for extreme diameters and dynamic eccentricity testing — a clear signal of ambition to capture seal applications in larger EV and industrial drivetrains.
- Parker Hannifin Corporation (Cleveland, Ohio, United States) — Offers Clipper and radial lip oil seals for rotating shaft applications with strong aftermarket and OE footprint in conventional powertrains.
- Trelleborg Sealing Solutions (Lund, Sweden) — Producer of Stefa® rotary shaft seals focused on durability for heavy‑duty and EV use cases. The company’s recent supplier certifications in agricultural OEM programs indicate an intentional push into engineered, high‑duty segments.
- SKF Group (Gothenburg, Sweden) — Combines bearing and sealing systems to create integrated shaft solutions; this systems‑level positioning is an advantage where space, NVH and lifecycle guarantees are bundled.
- NOK Corporation (Tokyo, Japan) — Strong OEM penetration for crankshaft and transmission seals; organizational depth in materials and long‑standing approvals in Asian vehicle programs.
- Hutchinson SA, ElringKlinger, JTEKT, Eaton, EKK Eagle Industry — Each leverages differentiating competencies from integrated powertrain modules to specialized elastomer formulations and commercial vehicle focus. Collectively, tiered competition fosters innovation while keeping supplier switching frictions moderate.
Recent product and capability developments — notably new material classes and enhanced test facilities — are not incremental. They lower the technical bar for entering higher‑value applications (large diameters, high temps, EV drivetrains) and will shape OEM sourcing in the 2026–2028 window.
Regulation, standards and supply chain dynamics
- Quality & approvals: IATF 16949 certification and OEM endurance testing remain gating factors for program inclusion. Suppliers without rigorous batch traceability and contamination control will be screened out early in supplier selection.
- Trade & classification: Tariff classifications for automotive seals affect landed costs and should inform nearshoring vs global sourcing decisions.
- Raw material volatility: Elastomer and synthetic rubber price swings directly impact manufacturing economics. Our sensitivity module quantifies pass‑through timing and realistic margin compression under stress cases.
How executives should use this intelligence in 2026
- R&D prioritization: Use the report’s materials roadmap to prioritize compound development and testing budgets for applications most likely to migrate to higher operating temperatures and tighter leakage tolerances (e.g., electrified drivetrains).
- Sourcing & supplier governance: Recalibrate supplier qualification timelines around test bench availability and certification cycles. The supplier heatmap helps rank suppliers for dual‑sourcing where geographic or raw material risk is material.
- Manufacturing footprint decisions: Leverage the scenario outputs to decide between incremental capacity expansions and flexible manufacturing assets that can pivot across seal types as vehicle architectures evolve.
- Commercial strategy: Align contract durations and indexation clauses to raw material volatility profiles identified in the study; consider hedging strategies and longer‑term take‑or‑pay structures where justified.
- M&A and partnerships: Use the report’s valuation templates and synergy mapping when evaluating acquisitions that provide complementary materials expertise, test facilities or regional route‑to‑market advantages.
Methodology and confidence level
The study combines bottom‑up sizing, OEM program mapping, primary interviews across OEMs and tier‑1s, and raw material price series reconciliation. Historical performance is reconciled for 2020–2025; forecasts span 2026–2032 and include sensitivity bands around macro and materials shocks. We validate supplier capabilities through capability audits, public disclosures and cross‑reference recent product launches and certification announcements.
Closing — the strategic value of the report
For leadership teams planning for 2026, this study functions as both an early warning system and an implementation playbook. It surfaces where technical innovation (materials and test capability) is creating value, which supplier relationships are strategically important versus simply transactional, and how modest but steady market growth should shape capital deployment and pricing discipline.
This preview intentionally highlights the analytic framework and strategic takeaways while withholding granular regional, application and material splits — those detailed tables and downloadable datasets are available in the full PW Consulting Automotive Oil Seal Market report. For procurement, product, and corporate development teams seeking to convert market insight into executable plans in 2026, the full report provides the calibrated numbers and supplier scorecards you will rely on.
For detailed analysis of this topic, please visit the official page: Automotive Oil Seal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com