

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: PCB Market to Reach USD 138.4B by 2032 at 5.28% CAGR

Printed Circuit Board Market 2026: Strategic Imperatives for Decision‑Makers
As organizations finalize 2026 budgets and set multi‑year roadmaps, the Printed Circuit Board (PCB) sector sits at a strategic inflection point. Our PW Consulting market study – built on a 2025 base year with historical analysis through 2020–2025 and a forward forecast to 2032 – shows the global PCB market reached approximately USD 96.8 billion (figures reported in USD Million) in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.28% across the 2026–2032 forecast window. That stable but structurally shifting growth trajectory demands a different set of choices from procurement directors, R&D leads, corporate development teams, and policy stakeholders alike.
Printed Circuit Board Market
What this research delivers (practical, decision‑grade content)
- Actionable forecasts and scenarios: a base forecast plus three stress scenarios driven by raw‑material volatility, geopolitics, and policy interventions to stress-test capital allocation and inventory policies.
- Supply‑chain playbook: supplier heatmaps, short‑ and medium‑term risk scores, and tactical contracting clauses designed to preserve margins under rapid commodity swings.
- Technology and capacity roadmaps: capability matrices for rigid, flexible, HDI and substrate technologies, and guidance on where incremental CAPEX will unlock the most value.
- Commercial and pricing levers: a modular pricing playbook for OEMs and EMS providers that balances pass‑through mechanisms, hedging, and collaborative supplier cost‑reduction programs.
- Competitive and M&A playbooks: a prioritized target list with acquisition fit scores, integration risk checklists, and divestiture templates for companies seeking to reshape portfolios.
- Analytical toolset: an Excel model for “what‑if” scenario analysis (currency, commodity, lead‑time shocks), supplier scorecards, and an executive dashboard for monthly monitoring.
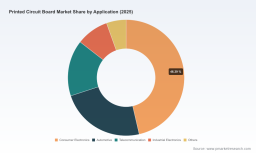
We intentionally omit the full segmentation tables in this executive introduction to preserve the strategic runway for clients; the full dataset—including proprietary regional, type and application breakdowns, and vendor‑level benchmarks—is available in the complete report.
Printed Circuit Board Market
Macro dynamics shaping 2026 decisions
- Commodity shocks and cost passthrough: 2025–first quarter 2026 saw unprecedented input volatility. Copper foil and prepreg costs jumped sharply in 2025 (industry reporting cited rises in the order of multiple tens of percent), and acute supply disruptions in early 2026 produced price spikes and lead‑time elongation for key resins and foils. One industry outlook reported PCB prices increasing as much as 40% in April 2026 during a raw‑material squeeze; parallel reports documented epoxy resin lead times extending materially. For 2026 planning this translates to three imperatives: convert variable costs into hedged exposures where possible, redesign bill‑of‑materials to diversify critical suppliers, and build commercial clauses that fairly allocate unexpected cost inflation.
- Policy and reshoring momentum: legislative initiatives introduced in 2025 to support domestic PCB production are reshaping investment calculus. Producers and OEMs must now weigh the long‑term advantages of nearshoring (proximity, reduced geopolitical risk, potential incentives) against higher operating costs. Our scenario work quantifies the threshold at which reshoring becomes value‑accretive under different subsidy and tariff assumptions.
- Geopolitical tail risks: episodic conflicts in early 2026 created immediate delivery and price dislocations. Scenario planning in our study models both transient shocks and protracted disruptions, giving corporate development teams trigger points for capacity acceleration, stockpiling, or strategic supplier substitution.
- Consolidation and competitive dynamics: the market structure remains neither atomistic nor highly concentrated – top players hold meaningful share but opportunities exist for mid‑market consolidation. Our analysis highlights how vertical integration (for example into copper‑clad laminates and IC substrate capabilities) and capacity specialization (Ultra‑HDI, high‑layer‑count, rigid‑flex) are the dominant strategies for defensive and offensive growth.
Competitive landscape — who to watch and why
The industry’s front runners have sharpened distinct strategic orientations. Below are high‑level profiles and strategic implications for key players featured in our analysis.
Printed Circuit Board Market
- TTM Technologies (United States) – Focused on advanced PCB manufacturing and RF connectivity solutions for computing, defense, and aerospace. Strategic implication: TTM’s recent Ultra‑HDI facility initiative in Central New York underscores a bet on defense and advanced computing demand and signals a move to secure domestic high‑end capacity. Corporates should evaluate partnerships or co‑investment models where onshore security and advanced capability are required.
- Unimicron Technology (Taiwan) – Specializes in HDI, high‑layer‑count multilayer, and IC package carrier PCBs for consumer electronics, automotive, and servers. Strategic implication: their capability mix makes them a natural partner for OEMs chasing miniaturization and high‑density computing; engagement strategies can range from preferred supplier agreements to joint development programs.
- Nippon Mektron & Ibiden (Japan) – Both emphasize high‑reliability multilayer and flexible substrates, with Ibiden also strong in semiconductor packaging substrates. Strategic implication: Japanese vendors remain go‑to partners for reliability‑critical applications (automotive, industrial) and for premium pricing segments where performance trumps cost.
- Zhen Ding Technology (Taiwan), Tripod Technology & Shengyi Technology (China) – Players competing on scale across rigid and flexible PCBs and targeting diverse end markets. Strategic implication: these firms are focal points for supply diversification strategies and for buyer negotiations where scale advantages can translate into lead‑time resilience.
- Compeq Manufacturing (Taiwan) – Specializes in high‑layer‑count and HDI PCBs for data centers, AI servers, and telecom. Strategic implication: as compute density drives demand for specialized substrates, partnerships with firms like Compeq will be central to server OEMs aiming to secure capacity for AI workloads.
Recent industry developments reinforce these dynamics: greenfield expansions and facility investments were announced across geographies throughout 2025 (including a large integrated multilayer PCB and laminate facility in India and TTM’s Ultra‑HDI plant), while industry trade events in late 2025 emphasized design‑for‑manufacturability and advanced materials innovation.
Strategic playbook for 2026 (what leaders should do now)
- Run commodity stress tests and lock optionality: use layered hedges for copper exposure, negotiate flexible pricing ladders with suppliers, and create approved secondary supplier lists with rapid qualification pathways.
- Prioritize capability over low cost for mission‑critical products: for automotive, defense, and server platforms, invest in supplier certification and co‑fund capability upgrades rather than chasing the lowest bid.
- Embed resiliency in sourcing: implement near‑term tactical inventory buffers for critical SKUs and mid‑term dual‑sourcing for key phases (laminates, foils, prepregs), with pre‑negotiated surge capacity clauses.
- Pursue targeted inorganic moves: use our M&A scorecard to identify tuck‑ins that close capability gaps (e.g., HDI, high‑layer count, substrate tech) and accretive consolidation targets where scale materially improves margin protection during commodity volatility.
- Leverage policy incentives intelligently: map the economics of reshoring under realistic subsidy scenarios and prioritize investments that yield the fastest payback under plausible incentive regimes.
- Adopt rolling scenario planning: refresh supply‑chain and pricing scenarios monthly through 2026 to ensure trigger points for strategic actions are well understood and rehearsed.
Why PW Consulting’s PCB study matters for 2026
This report is designed as a decision engine: it blends granular supplier intelligence and capability mapping with scenario‑driven financial models and operational playbooks. For executives making capital allocation, sourcing, or M&A decisions in 2026, the study provides the evidence base and tactical templates to move quickly and with conviction when market windows open or shocks occur.
We deliberately keep several high‑value datasets and segment‑level unit economics reserved for the full publication and client engagements—these include the complete regional and application breakdowns, vendor‑level price curves, and the proprietary benchmarking matrix. That level of detail is essential for implementation and is provided with the full report and accompanying advisory services.
Next steps
- Download the full report for the complete dataset and the embedded decision models.
- Request a tailored briefing to translate the findings into prioritized actions for your portfolio (procurement remediation, CAPEX sequencing, or M&A targeting).
- Engage our scenario workshop to stress-test your 2026 plans under the most disruptive commodity and geopolitical pathways.
In an industry where raw‑material swings, technology density, and policy shifts can rapidly rewrite competitive advantage, the right mix of forecasting rigor and operational playbooks is the difference between defending margin and capturing share. PW Consulting’s Printed Circuit Board Market study equips leaders to do both.
For detailed analysis of this topic, please visit the official page: Printed Circuit Board Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com