

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insight: Blood Filter Market to Reach USD 1.4B in 2025

Blood Filter Market: Strategic Imperatives for 2026 — A PW Consulting Preview
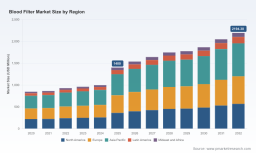
The global blood filter market is entering a pivotal chapter. Our PW Consulting market model — calibrated to a 2025 base year and spanning historical (2020–2025) and forecast (2026–2032) windows — shows sustained expansion driven by clinical demand for safer transfusion practice, the proliferation of blood-processing applications, and rising investment in perioperative and critical‑care blood management. With a compound annual growth rate (CAGR) of 6.7% across the 2026–2032 forecast horizon, the market trajectory offers both growth runway and higher regulatory and commercial complexity. In 2025 the market reached a notable valuation (reported in USD, revenue unit: Million) and is projected to grow meaningfully through 2032 under our base case scenario.
Blood Filter Market
Why this matters to corporate leaders in 2026
- Strategic timing: The market is large enough to justify scale investments but still sufficiently fragmented that tactical moves (targeted M&A, geographic expansion, or clinical partnerships) can shift competitive positions meaningfully within 18–36 months.
- Regulatory inflection: Recent regulatory actions have amplified compliance risk and will change procurement behaviors — creating short-term disruption and medium-term opportunity for suppliers with robust quality and vigilance programs.
- Technology and clinical differentiation: Incremental innovation — in leukocyte-reduction efficiency, microaggregate capture, materials science, and autologous blood recovery integration — is becoming an important lever for premium pricing and hospital adoption.
- Operational resilience: As procurement increasingly prioritizes supplier reliability and traceability, manufacturing footprint, supplier consolidation, and nearshoring strategies rise to the top of executive agendas.
What the full PW Consulting report delivers (practical, decision‑ready outputs)
- Market model and interactive dashboard: A proprietary, scenario-ready model with historical reconciliation (2020–2025) and forward-looking forecasts (2026–2032) allowing executives to run sensitivity, pricing, and volume scenarios. Note: the public preview intentionally withholds granular segment-level revenue lines — these are available in the full deliverable.
- Segmentation analysis: Multi-dimensional segmentation by product, material, application, and region. The report quantifies addressable sub‑markets, growth differentials, and strategic margins — without disclosing those fine-grain cells in this preview.
- Competitive landscaping: Deep profiles and strategic positioning maps for market incumbents and emergent specialists, including product portfolios, recent clinical claims, manufacturing footprints, and go-to-market models.
- Regulatory & clinical risk map: An evidence‑based matrix linking device classifications, regional approval pathways, active safety communications, and the implications for reimbursement and tender dynamics.
- Commercial playbooks: Actionable go-to-market strategies for market entry, customer segmentation, pricing strategy, and clinical evidence generation tailored to vendor scale and ambition.
- M&A & partnership playbook: Target screens, valuation benchmarks, and integration risks for buyers seeking growth via bolt‑on acquisitions or strategic alliances.
- Operational & supply‑chain checklist: Supplier concentration analysis, lead‑time stress tests, and contingency plans to secure critical materials and components.
Competitive dynamics — who’s positioned to win (and why)
The competitive picture is mixed: global diversified medtech players remain influential thanks to scale, regulatory know‑how, and broad hospital relationships, while specialist firms compete on innovation and clinical differentiation. Below we summarize the strategic posture of core players tracked in the report and the tactical implications for rivals, partners, and acquirers.
Blood Filter Market
- Pall Corporation (Port Washington, NY) — Known for established transfusion filters and leukocyte‑reduction offerings. Strengths include a deep installed base, recognized clinical claims, and global distribution; risks stem from recent device-level recall activity that increases near‑term reputational and regulatory scrutiny. For competitors, Pall’s recall creates localized opportunity to accelerate tender wins where immediate supply continuity is needed.
- Fresenius Kabi AG (Bad Homburg, Germany) — A broad blood‑management portfolio and strong relationships in hospital procurement. Its focus on leukodepletion and component processing positions it well for integrated solutions, but incumbency also requires continuous clinical evidence investment to defend premium positions.
- Haemonetics Corporation (Boston, MA) — Combines blood recovery systems with filter technologies (including autologous recovery filtration), giving it differentiation in surgical blood management. Strategy should emphasize bundled value propositions that link device, consumable, and service economics.
- Terumo Corporation (Tokyo, Japan) — Strength in pre‑storage leukodepletion and transfusion sets, supported by global clinical channels. Terumo’s comparative advantage is regulatory experience in multiple jurisdictions and product breadth.
- Asahi Kasei Medical Co., Ltd. (Tokyo, Japan) — Focus on neonatal/pediatric low‑volume transfusion filters demonstrates niche specialization. This positioning reduces direct price competition but requires sustained specialization in clinical training and neonatal procurement pathways.
- B. Braun Melsungen AG (Melsungen, Germany) — Offers comprehensive transfusion and blood‑component processing sets; competitive strength lies in integration across the therapy lifecycle and longstanding hospital relationships.
- Macopharma SA (Saint‑Hilaire‑de‑Riez, France) — A specialist in leukocyte depletion and plasma pathogen‑reduction adjacent technologies. Its strategic playbook should focus on partnerships with blood services and plasma collectors.
Regulatory and clinical noise — immediate risks and strategic consequences
- FDA recall activity and warning letters in early 2026 have raised the bar for post‑market surveillance, adverse event reporting, and clinical documentation. Expect lengthened procurement cycles as hospital risk committees and group purchasing organizations increasingly require enhanced vigilance artifacts.
- Certain blood‑filter device categories remain subject to defined 510(k) pathways and Class II controls; manufacturers should revisit regulatory files, labeling, and special controls compliance to avoid interruptions and to support tender bids in regulated markets.
- The combined effect: near‑term market disruption (supplier switching, inventory hoarding) and medium‑term higher compliance costs that favor incumbents with established regulatory infrastructures while increasing entry barriers for smaller innovators.
2026 playbook — prioritized actions for manufacturers, investors, and hospital systems
- Immediate (0–12 months)
- Conduct a regulatory readiness audit focused on post‑market surveillance, adverse event reporting, and label claims. Prioritize remediation where gaps exist.
- Stabilize supply for key customers: secure safety stock, verify secondary sourcing for critical materials, and establish expedited complaint handling workflows to maintain contract trust.
- Leverage clinical evidence to convert short‑term procurement disruptions into wins — offer rapid‑deploy comparative studies and risk‑mitigation guarantees tied to hospital KPIs (e.g., transfusion reaction rates, reoperation risk).
- Near term (12–24 months)
- Invest in differentiated materials and product features that address clinician pain points (e.g., filter flow dynamics, hemolysis minimization, compatibility with cell‑saver systems).
- Pursue selective partnerships with blood services and large hospital systems to co‑develop usage protocols and build evidence for value‑based contracting.
- For acquirers: prioritize targets with clean regulatory histories, defensible IP, and complementary channel access rather than scale alone.
- Medium term (24–36 months)
- Scale manufacturing footprint strategically to reduce lead times and manage tariff/regulatory risk; consider nearshoring for mission‑critical consumables.
- Deploy outcome‑linked pricing pilots with large health systems to capture value from reduced adverse events and improved transfusion efficiency.
- For investors: stress‑test exit scenarios against evolving regulatory risk premiums and payer acceptance curves.
Methodology highlights and confidence framing
Our forecasts combine bottom‑up shipment data, historical supplier revenues, product lifecycle curves, hospital procurement cycles, and macro health‑expenditure inputs. We use scenario analysis (base, conservative, upside) to reflect regulatory shock, adoption rate variance, and raw‑material price stress. The model includes sensitivity levers for price erosion, substitution, and accelerated clinical adoption. The full report provides the calibrated workbook and an interactive dashboard so clients can run bespoke scenarios; the preview intentionally omits fine‑grained segment cells to preserve the report’s commercial value for paying subscribers.
Blood Filter Market
How PW Consulting can work with you in 2026
- Custom due diligence and valuation modeling for M&A, with special attention to regulatory legacy risk and post‑acquisition remediation costs.
- Commercial acceleration programs: go‑to‑market design, hospital pilot management, and clinical evidence generation roadmaps.
- Regulatory readiness and remediation support, including complaint handling, recall playbooks, and 510(k) strategy alignment.
- Supply‑chain resilience assessments and mitigation planning tailored to consumable manufacturing footprints.
This preview is designed as an operational trailer: it outlines the strategic contours and urgent decision levers for 2026 while reserving the granular segment-level intelligence and the proprietary market model for the full report. For access to the complete dataset, segmented revenue cells, company financial benchmarks, and our interactive forecast workbook, visit the PW Consulting report page and request the full Blood Filter Market study and advisory engagement options.
For detailed analysis of this topic, please visit the official page: Blood Filter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com