

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Control Foot Switches Market to Reach USD 1.65 Billion by 2032 at 5.5% CAGR

Control Foot Switches Market: Strategic Imperatives for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an independent, forward-looking briefing designed to orient executives, product leaders, procurement heads, and M&A teams preparing for strategic moves in 2026. This introduction synthesizes market scale, competitive dynamics, regulatory headwinds, and actionable playbooks derived from our full Control Foot Switches Market study (base year 2025; forecast period 2026–2032). It is written to demonstrate the research depth you need to act — while reserving the granular segment-level datasets and supplier rankings for subscribers to the full report.
Control Foot Switches Market
Why this market matters in 2026
-
Reliable human-machine interface components are mission-critical across medical imaging, surgical systems, laboratory automation, and industrial controls. Foot switches sit at the intersection of ergonomics, electrical safety, and clinical risk management — meaning their performance affects uptime, patient safety, and liability exposure.
Control Foot Switches Market -
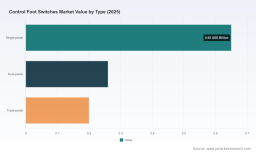
From a macro perspective, the global Control Foot Switches market exhibited steady expansion in the 2020–2025 historical window and is expected to continue growing through 2032. Our topline sizing follows a clear upward trajectory: the market was modest in 2020, expanded through 2025 (our base year), and is projected to grow at a mid-single-digit compound annual growth rate (CAGR) of 5.5% during the 2026–2032 forecast period. By 2026 the market is forecast to increase relative to 2025 and continues to scale thereafter through 2032.
Control Foot Switches Market -
Market concentration metrics confirm a fragmented supplier ecosystem: the three-largest vendors account for roughly a quarter of market share (CR3 ≈ 25.8%), while the top five account for just over 30% (CR5 ≈ 32.4%). That fragmentation creates both risk — inconsistent standards and variable supplier resilience — and opportunity for consolidation or strategic supply partnerships.
Key demand drivers and technology vectors
-
Healthcare modernization and procedural throughput: growth in minimally invasive procedures, interventional imaging suites, and surgical robotics is increasing demand for foot-actuated controls that are durable, hygienic, and precise.
-
Shift toward wireless and modular designs: systems demanding mobility, cable-reduction, and OR flexibility are accelerating adoption of wireless footswitch technologies — but these bring new reliability, cybersecurity, and regulatory verification requirements.
-
Infection prevention and device cleaning protocols: the tension between full sterilizability and electronic reliability is shaping design choices. Many medical-grade footswitches are specified for manual cleaning or limited chemical disinfection rather than autoclave sterilization, which affects product architecture and aftermarket service models.
-
Industrial automation spillover: industrial-grade foot switches continue to inform material and sealing standards (e.g., IP ratings), while medical certifications remain a distinct barrier to entry in clinical markets.
Regulatory and safety developments that will shape 2026 strategies
-
Regulatory scrutiny is intensifying. Recent high-profile recall activity tied to foot switch failures has placed supplier reliability squarely in procurement risk registers. Notable events include regulatory actions related to wired foot switch malfunctions in imaging systems and pedal spring failures in surgical robots — both with implications for product design, post-market surveillance, and liability exposure.
-
Across suppliers, compliance with electrical safety and quality systems standards (IEC 60601 family, FDA QMS/510(k) pathways, and ISO 13485) is table stakes for clinical adoption. Buyers will increasingly place contractual requirements around validation evidence, field-failure MTBF data, and CAPA histories.
-
Sterilization and disinfection guidance is fragmented by supplier and product family. Several established vendors explicitly prescribe manual cleaning or defined disinfectant exposure rather than steam sterilization; those constraints will shape clinical acceptance and procurement specifications in 2026.
Competitive landscape: profiles and strategic implications
The market is characterized by a mix of specialized medical suppliers, diversified OEMs, and regional contract manufacturers. Below are summary profiles of representative players and the strategic implications for market participants:
-
Linemaster Switch Corporation (USA) — Offers FDA-cleared wired and RF wireless medical foot switches with IEC 60601 compliance and explicit references to surgical and imaging applications. Strategic implication: strong regulatory credentials make such suppliers attractive for OEM partnerships where fast regulatory onboarding is required.
-
Herga Technology (UK) — Focus on modular, multi-pedal designs with rugged ingress protection and established medical approvals. Strategic implication: modular approaches enable platform standardization across procedure types, reducing SKU proliferation for system integrators.
-
DewertOkin GmbH (Germany) — Produces medical-grade dental and surgical footswitches aligned with medical device quality standards. Strategic implication: European-certified vendors are preferred partners for CE-marked systems and can ease market entry in regulated territories.
-
steute Meditech (US/EU footprint) — Specializes in bespoke wireless and cabled foot switches for OR ecosystems. Strategic implication: suppliers with custom-engineering capability are valuable where ergonomic differentiation and integration with proprietary platforms are required.
-
China-based suppliers (representative) — A cohort of manufacturers offers cost-competitive metal and plastic foot pedals, including integrated solutions for imaging OEMs. Strategic implication: Chinese suppliers can be attractive for volume-price plays but require rigorous quality and regulatory due diligence for clinical use.
-
Systems OEMs with integrated controls — Larger medical device OEMs increasingly integrate footswitches into platform-level offerings, sometimes sourcing from internal teams or captive suppliers. Strategic implication: independent footswitch vendors may need to negotiate supply exclusivities or target accessory channels to retain relevance.
Operational and commercial risks to monitor in 2026
-
Product reliability incidents: field failures can trigger recalls, remediation costs, and brand damage. Scenario planning should assume both isolated component failures and systemic design issues that propagate across an OEM’s installed base.
-
Regulatory delays and additional testing requirements for wireless solutions (e.g., EMC, RF safety) can extend time-to-market and certification costs.
-
Supply chain concentration and single-source dependencies for key components (force sensors, sealed housings, RF modules) raise procurement risk. The fragmented market structure suggests heterogeneous supplier capabilities; prudent buyers will implement multi-sourcing and strategic vendor development programs.
What the full PW Consulting report delivers (high level)
Our comprehensive study provides the datasets and practical tools that decision-makers need to execute in 2026. Highlights include:
-
Topline market sizing and seven-year forecasts (2026–2032) with scenario runs reflecting alternate adoption curves for wireless, sterilizable, and integrated OEM modules.
-
Regulatory matrix mapping standards, certification pathways, and post-market surveillance expectations for medical-grade footswitches across major jurisdictions.
-
Supplier capability assessment framework, including QA maturity (ISO 13485, FDA QMSR), product portfolio depth, custom engineering bandwidth, and historical field performance indicators.
-
Commercial playbooks: procurement scorecards, RFP templates, TCO models incorporating lifecycle repair/replacement, and warranty-cost simulations.
-
M&A and investment guidance: identification of acquisitive synergies, valuation heuristics for bolt-on targets, and integration risks specific to electromechanical HMI components.
-
Operational readiness checklists for device suppliers and clinical OEMs addressing sterilization constraints, cleaning protocols, and service logistics.
Actionable recommendations for 2026
-
Audit supplier assurance comprehensively: require sample-level reliability testing, documented CAPA histories, field complaint trend analyses, and explicit sterilization/disinfection instructions before qualifying suppliers for clinical systems.
-
Pursue modular product strategies: standardize on a limited set of footswitch platforms that can be configured for multiple applications to lower inventory, simplify validation, and accelerate time-to-market.
-
Insist on design-for-service: prioritize suppliers offering sealed, replaceable sub-assemblies and clear service parts pipelines to reduce downtime and warranty exposure.
-
Integrate regulatory risk into commercial contracts: include performance bonds, recall-sharing clauses, and defined remediation timelines tied to supplier certifications.
-
Prepare for consolidation: with a fragmented market and moderate growth, 2026 is a window for strategic acquisitions of specialized vendors to buy capability, certifications, or regional access — at valuations sensitive to quality records and product liability histories.
Concluding view: where to focus your 2026 investment and attention
Control foot switches are small in bill of materials but outsized in operational impact. The market’s steady growth (mid-single-digit CAGR through 2032) and fragmented supplier base create a favorable backdrop for disciplined investment and strategic consolidation. However, the regulatory environment and recent field incidents underscore that quality, reliability, and compliance are non-negotiable. For 2026 decision-makers, the highest-return actions are focused supplier qualification, modular platform design, and embedding regulatory contingency into commercial and M&A plans.
PW Consulting’s full report equips you with the quantitative breakdowns, supplier scorecards, and executable templates you need to translate these priorities into procurement, product, and M&A decisions. For access to the complete datasets, regional and application-level forecasts, and supplier rankings that the market relies upon, please visit the report landing page.
For detailed analysis of this topic, please visit the official page: Control Foot Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com