

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Pallet Conveyor Market to Reach USD 2,360.24 Million by 2032 at 5.2% CAGR

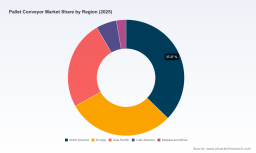
Pallet Conveyor Market — Strategic Imperatives for 2026 Decision‑Makers
As organizations finalize capital plans and automation roadmaps for 2026, the pallet conveyor market presents a mix of predictable expansion and tactical uncertainty. PW Consulting’s latest Pallet Conveyor Market research (base year 2025; forecast period 2026–2032) synthesizes industry dynamics, supplier capability profiles, regulatory shifts, and practical decision tools to help operations, engineering, and corporate development leaders convert market movement into defensible actions.
Pallet Conveyor Market
Momentum in context: the growth story and what it means
The pallet conveyor market has demonstrated steady recovery and expansion through the early 2020s. After a post‑pandemic rebound and a period of cost pressure, the market reached approximately USD 1,655.19 Million in 2025. Under our central forecast—anchored to market activity, investment pipelines, and demand drivers—the market is projected to continue growing at a compound annual growth rate (CAGR) of 5.2% across 2026–2032, reaching roughly USD 2,360.24 Million by 2032.
Pallet Conveyor Market
Why these headline numbers matter for 2026 decision cycles:
Pallet Conveyor Market
- They justify near‑term capital allocation to pallet handling automation where ROI can be measured in labor savings and throughput gains.
- They imply a healthy competitive environment where product differentiation, service models, and systems integration determine share shifts rather than pure market expansion alone.
- They highlight a multi‑year upgrade window: decisions made in 2026 are likely to determine installed base composition for the rest of the decade.
Key market dynamics shaping vendor and buyer strategies
Our analysis isolates four drivers that will disproportionately influence winners and laggards in 2026:
- Automation economics and labor availability — Persistent labor shortages and rising wages in logistics and manufacturing continue to push organizations toward automated pallet handling. Systems that lower the need for manual intervention and reduce changeover time will command premium positioning.
- Material‑cost pressure and contract design — Steel, aluminum, and copper volatility increased fabricator input costs in 2024–2025; many suppliers responded with price‑escalation clauses. Buyers must now treat supply contracts and SLAs as strategic levers: timing of procurement and clause negotiation materially affect landed system cost.
- Regulatory and safety compliance — The introduction and adoption of standards such as EN619:2022, alongside EN ISO 13854:2019 and performance requirements under EN ISO 13849, raise the compliance bar for pallet conveyors. In the U.S., OSHA guidance referencing ANSI/ASME B20.1 and the need for documented risk assessments under EN ISO 12100 create operational requirements that impact design, installation timelines, and total cost of ownership.
- Market concentration and supplier strategy — The sector exhibits a moderate degree of concentration: leading incumbents capture a meaningful share of industry revenue, yet there remains room for specialized vendors and regional integrators to compete effectively. This structure favors alliances, platform modularity, and targeted M&A plays.
What this means for 2026 strategic decisions
Executives should translate the market signals into concrete actions across procurement, engineering, and corporate development:
- Procurement — Delay versus accelerate? Use the 2026 budget cycle to re‑price quotes with escalation‑resilient contract terms. Short‑to‑mid term procurement should prioritize suppliers with strong raw‑material hedging, transparent escalation mechanics, and modular systems that reduce bespoke engineering days.
- Engineering and operations — Design for agility Move away from single‑purpose, high‑customization designs where possible. Investments in modular pallet platforms, quick‑change pallets, and standardized interfaces reduce retrofit costs and futureproof throughput changes.
- Automation and integration — Prioritize end‑to‑end productivity Integration capabilities (controls, ASRS compatibility, sorter interfaces) are often worth a premium. Consider lifecycle costing that includes software updates, cybersecurity of control systems, and certification pathways for safety standards compliance.
- M&A and partnerships — Fill capability gaps For firms seeking to scale quickly, bolt‑on acquisitions of regional integrators or technology enablers (e.g., motor controllers, pallet‑level sensors) can accelerate market access without the long lead time of in‑house development.
- Service and aftermarket — Make it a revenue stream Warranty models, remote diagnostics, and outcome‑based SLAs (e.g., uptime guarantees) are differentiators that reduce buyer procurement friction and increase lifetime vendor margins.
Competitive landscape — who to watch (and why)
The market is anchored by a mix of heavy‑duty OEMs, modular platform providers, and system integrators. Our report profiles leading firms and contrasts their propositions along capability, product breadth, geographic reach, and commercial models. Highlights include:
- Alba Manufacturing (Albany, Oregon) — Known for heavy‑duty, pre‑engineered pallet handling systems designed for industrial environments. Recent trade show visibility (MODEX 2026) signals an emphasis on commercial expansion and product showcase as a go‑to‑market tactic.
- Hytrol Conveyor Co. (Jonesboro, Arkansas) — Offers comprehensive pallet handling solutions across diverse weights and environments; competitive strength lies in end‑to‑end system provision and strong domestic distribution.
- Interroll (Switzerland; global operations) — Brings modular platform thinking and component‑level innovation (e.g., modular pallet conveyor platforms) that appeal to customers prioritizing scalability and integration.
- Dorner Manufacturing (Hartland, Wisconsin) — Focuses on precision flow control with timing belt and dual‑move systems—an advantage where delicate material flow and synchrony are required.
- mk North America (Michigan) — Competes on adaptable, quick‑change pallet systems suited to assembly and mixed‑model production lines.
- Regional specialists and integrators — Firms such as Roach Conveyors, Ashland Conveyor, Adaptecsolutions, Pack Air Inc., and others remain important partners for tailor‑made installations and service agreements, especially where U.S. manufacturing or rapid deployment is required.
- Systems integrators and ASRS integrators — Players like Swisslog integrate pallet conveyors into automated warehouse ecosystems; their recent product certifications (e.g., a pallet conveyor system certified to EN619:2022) underscore the convergence of safety, software, and intralogistics design.
Recent developments to factor into 2026 plans
- Trade show activity and product showcases continue to be a primary channel for channel engagement and RFP pipelines—e.g., Alba Manufacturing’s MODEX 2026 presence.
- Certifications and safety updates (Swisslog’s EN619:2022 certification for a pallet conveyor system) have practical implications for procurement specifications and installation checklists.
- Supplier pricing and contract mechanisms have shifted in response to steel and non‑ferrous price movements; buyers should expect continued negotiation over escalation clauses.
What the full PW Consulting report delivers (practical, actionable modules)
Our market study is deliberately structured to support decision cycles in 2026. The report contains:
- Market sizing and trend analysis (historical 2020–2025, outlook 2026–2032) with scenario runs to stress‑test investment timing.
- Provider scorecards and capability heat maps that evaluate companies across engineering depth, modularity, geographic coverage, and aftermarket strength.
- Regulatory compliance checklist and implementation timelines (EN and ANSI/OSHA implications) tailored to procurement and installation planning.
- Commercial and procurement playbooks, including recommended contract language for steel‑price escalation, lead‑time guarantees, and performance KPIs.
- Investment‑level cost models and ROI calculators to compare CAPEX timing against labor arbitrage and throughput gains.
- Deal‑tracker and recent developments log that documents major product launches, certifications, and trade activities through 2026.
Note: In this high‑level briefing we have intentionally avoided disclosing detailed segment revenues and regional/application splits. The full report contains the granular segmentation and revenue breakout that procurement, engineering, and corporate development teams use to size opportunities and prioritize supplier shortlists.
How to use this intelligence in your 2026 plans
Immediate steps for executives preparing 2026 programs:
- Run a gap analysis of current pallet handling capability versus the safety and integration requirements detailed above; prioritize upgrades that unlock throughput or reduce headcount risk.
- Negotiate supplier contracts with explicit material‑price clauses, lead‑time remedies, and staged payment tied to milestones to reduce exposure to raw‑material shocks.
- Pilot modular platforms in one or two facilities to validate changeover time and control‑integration before enterprise‑wide rollouts.
- Engage legal and EHS early on to map EN/ANSI/OSHA compliance paths into project schedules to avoid late change orders.
- Consider strategic partnerships or targeted acquisitions to acquire missing integration capabilities or regional service footprints rather than building from scratch.
Closing — why 2026 is a pivotal year
The pallet conveyor market in 2026 is neither a speculative growth bubble nor a mature stagnation; it is a pragmatic expansion driven by automation needs, cost pressures, and regulatory tightening. The decisions organizations make this year about suppliers, contract terms, and automation architecture will disproportionately influence total cost of ownership and operational resilience through the remainder of the forecast window.
For teams required to justify capital and to design compliant, scalable systems, PW Consulting’s Pallet Conveyor Market report supplies the data, supplier intelligence, and practical tools to act with conviction. To access the full segmentation, supplier scorecards, and downloadable ROI models, consult the complete report and our interactive dashboards.
For detailed analysis of this topic, please visit the official page: Pallet Conveyor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com