

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Smartphone Cover Glass Market reaches $1,563.7M in 2025

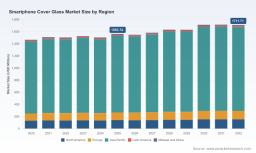
Smartphone Cover Glass Market — Strategic Preview for 2026 Decision-Makers
This executive preview introduces PW Consulting’s forthcoming Smartphone Cover Glass Market study (base year 2025; forecast period 2026–2032). The market is mature and concentrated, exhibiting modest compound growth — a projected CAGR of 1.3% across the 2026–2032 forecast window — with total industry revenues measured in the low‑to‑mid USD millions range (reported on a USD, Million basis). Our analysis synthesizes five years of historical performance (2020–2025), the near‑term supply shocks and regulatory shifts of 2024–2026, and scenario models to support the strategic decisions executives must make in 2026.
Smartphone Cover Glass Market
Why this research matters in 2026
- Strategic timing: 2026 marks a transition point where incremental innovation (e.g., ceramic and next‑gen chemically strengthened glass) converges with industrial shifts — capacity expansions, reshoring initiatives, and new regulatory costs — creating asymmetrical opportunities for first movers.
- Allocation of scarce capital: With headline growth subdued, returns will be driven by unit economics, price mix, and cost control rather than volume expansion. Our study isolates the drivers that matter for capex prioritization and short‑cycle profitability improvements.
- Supply chain resilience: Recent raw‑material disruptions and export controls have elongated lead times and raised compliance costs. The report provides decision frameworks to balance onshore capacity, dual sourcing, and inventory strategies without overcapitalizing.
- Competitive positioning: Market concentration is high (CR3/CR5 levels indicate a top‑heavy supplier base). Understanding competitive dynamics — including product innovation roadmaps and buyer‑supplier verticality — is essential for OEM procurement and supplier strategy.
What the full report delivers (practical, transaction‑ready content)
- Integrated market model — a downloadable, scenario‑ready financial model (2026–2032) calibrated to 2020–2025 history that lets you test demand shocks, price erosion, and material‑cost inflation. (Macro figures and headline CAGR are published in this preview; detailed segment numeric tables are reserved for the report.)
- Technology and product roadmap — comparative assessment of chemically strengthened glass variants, ceramic composites, sapphire alternatives, and thin‑glass processes, with a decision matrix that maps performance attributes to smartphone design priorities (drop resistance, scratch resistance, weight, and cost).
- Supply chain maps and lead‑time analytics — end‑to‑end supplier mapping for primary cover glass technologies, tier‑1 vs tier‑2 concentration risk heatmaps, and a playbook to reduce average lead times and improve fill rates.
- Manufacturing economics and CAPEX playbook — benchmarking of build vs buy decisions, utilization curves, break‑even analyses under multiple demand scenarios, and procurement contract templates to protect margins under volatile raw‑material pricing.
- Regulatory and geopolitical scenario planning — bespoke scenarios that quantify the operational and cost impact of export controls, updated export‑control rules, and heightened compliance costs (e.g., chemical handling). Each scenario includes mitigations and a policy engagement checklist.
- Supplier performance scorecards and commercial negotiation levers — calibrated supplier scorecards, escalation protocols, and recommended terms for long‑cycle supply agreements tailored to different buyer archetypes (flagship vs midrange OEMs).
- M&A and partnership intelligence — a filtered list of acquisition and JV target profiles, valuation sensitivities and integration risk checklists designed for strategic buyers and private equity.
Competitive landscape — what the market structure and recent moves mean
The smartphone cover glass market is marked by a concentrated supplier base and a clear technology hierarchy. The top global suppliers — including Corning Incorporated, AGC Inc., Schott AG, Nippon Electric Glass, AvanStrate, Biel Crystal Manufactory, Lens Technology and TPK Holding — set the pace on innovation, capacity expansion, and commercial leverage. PW Consulting’s report contains individual supplier dossiers and a comparative capability matrix; we summarize strategic signals below without publishing sensitive share or split data.
Smartphone Cover Glass Market
- Corning Incorporated (Corning, NY; https://www.corning.com): A technology and scale leader. Corning’s recent capacity expansions (early 2026) and the March 2026 launch of a next‑generation ceramic glass product signal an aggressive move to capture demand in premium and foldable applications. Moreover, the Apple–Corning production arrangement (announced August 2025) to localize large‑scale production in Kentucky materially changes OEM bargaining dynamics and regional manufacturing footprints.
- AGC Inc. (Tokyo; https://www.agc.com) and Schott AG (Mainz; https://www.schott.com): Legacy glass manufacturers with strong chemically strengthened glass portfolios. They compete on materials science and differentiated process IP, especially for premium display stacks.
- Nippon Electric Glass, AvanStrate, Biel Crystal Manufactory, Lens Technology, TPK: These firms collectively represent the global manufacturing breadth — from high‑precision specialty glass to high‑volume assembly and sapphire components. Their geographic footprints and scale are central to OEM supplier‑strategy decisions, especially where regionalization and cost competition collide.
Key implications from the competitive moves:
- Vertical partnerships and near‑shoring are accelerating. Apple’s partnership with Corning to localize production is an inflection point for how OEMs think about supply assurance and IP control.
- Product differentiation is concentrated at the top. Material innovations (ceramic composites, next‑gen strengthening) are the primary route to margin expansion in a low‑growth face market.
- Scale matters, but so does qualification lead time. Large incumbents can wield scale advantages, but OEMs still prize supplier flexibility for short lifecycle models and emergent form factors such as foldables.
Regulatory and supply risks that will affect 2026 choices
- Rising chemical‑handling costs: European compliance costs for hydrofluoric acid and similar agents rose notably in 2024, increasing processing costs for tempering operations and driving some shift toward alternative chemistries.
- Export control noise: Expanded U.S. export controls since 2024 and China’s updated export control rules introduce operational friction for cross‑border specialty material flows and tech transfer — an input to any regionalization or global sourcing decision.
- Supply chain timing: Industry lead times extended to approximately 45 days in 2024 amid precursor shortages and logistics congestion. This lengthening affects inventory strategies and buy decisions for 2026 product ramps.
Strategic playbook for 2026 — pragmatic moves by stakeholder
- OEMs: Prioritize a two‑track sourcing strategy — secure long‑term supply for flagship models with leading suppliers while maintaining flexible spot capacity for midrange SKUs. Accelerate qualification cycles for new material types to avoid single‑supplier lock‑in.
- Tier‑1 suppliers: Invest selectively in downstream capabilities (coating, integration) to capture more aftermarket value. Use joint‑development agreements to de‑risk product adoption and lock in capacity commitments.
- Investors and PE: Target bolt‑on acquisitions that provide process IP or niche capacity with low customer concentration. Apply rigorous scenario testing for export‑control and regulatory sensitivity when setting valuations.
- Policy and procurement: Establish compliance monitoring for chemical and export regulations and early engagement with regulators where possible. Negotiate flexible take‑or‑pay clauses to balance supplier CAPEX risk and buyer demand uncertainty.
How to use PW Consulting’s models and workshops
The full study includes downloadable models and workshop modules designed to make the output operational in 30–90 days:
- Demand sensitivity tool — test product mixes and price elasticity against macro scenarios (consumer demand shifts, form‑factor adoption curves).
- Capex sizing and ROI templates — compute break‑even for greenfield vs expansion, with embedded stochastic drivers for price and lead‑time risk.
- Supplier scorecard and negotiation playbook — a ready‑to‑use RFP template and scoring system calibrated to 2026 procurement realities.
- Regulatory impact simulator — quantify margin erosion under different compliance cost and export restriction scenarios.
What we are deliberately withholding in this preview (and why)
Consistent with our “trailer” approach, this preview surfaces headline macro trends, competitive context, and strategic implications to build confidence in our methodology. To preserve the commercial value of the full research product and to ensure clients engage directly for decision‑grade outputs, detailed segment tables (regional splits, application breakout, supplier share by segment, and unit‑level pricing matrices) are withheld from this public synopsis. The full dataset, annexes, and interactive models are available through PW Consulting’s report access channels and client workshops.
Next steps — how to convert insight into action in 2026
- Download the full report for the 2026–2032 market model and supplier dossiers.
- Book a tailored strategy workshop to adapt the scenario models to your balance sheet, product roadmap, and supplier exposure.
- Request a confidential supplier benchmarking memo if you are evaluating partnerships, M&A targets, or reshoring investments this year.
In a market where headline growth is modest but structural shifts — technology innovation, regionalization, and regulatory complexity — are accelerating, 2026 is a year to trade volume chasing for strategic clarity. PW Consulting’s full Smartphone Cover Glass Market study provides the calibrated data, scenario tools, and decision frameworks required to translate that clarity into defensible capital allocation, sourcing, and product strategy. Contact PW Consulting to obtain the full report, models, and a bespoke workshop to operationalize the findings for your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Smartphone Cover Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com