

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: BTS Antenna Market to Reach USD 23,299M by 2032 with 14.9% CAGR

BTS Antenna Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our new BTS Antenna Market study. This briefing is designed to make the strategic value of the full research immediately actionable for corporate leaders, investors, and network operators preparing decisions in 2026. Consider this a high-fidelity trailer: we expose the analytical framework, directional sizing, competitive cues, and tactical implications — while preserving the granular segment tables and proprietary scenario outputs for authorized report access.
BTS Antenna Market
Market at a Glance: Directional Sizing and Momentum
Our baseline synthesis uses 2025 as the reference year and tracks historical performance from 2020 through 2025, with forward-looking scenarios across 2026–2032. The BTS antenna ecosystem is experiencing an inflection driven by accelerated macro 5G rollouts, densification with small cells and indoor DAS, and an expanding set of enterprise and vertical IoT use cases. On a topline basis, the market is forecast to grow at a robust compound annual growth rate (CAGR) of 14.9% over the forecast window, underpinned by a multi-year lift in infrastructure spend and technology refresh cycles. Reflecting that trajectory, the market more than doubles from mid‑decade levels to reach the high‑single‑to‑low‑double‑billion USD scale by the end of our forecast horizon.
BTS Antenna Market
Why this matters for 2026 decisions
-
Timing capital allocation: The 14.9% CAGR and near‑term market acceleration imply that investment in antenna‑centric capabilities — whether in product R&D, manufacturing scale, or strategic partnerships — has an asymmetric upside if initiated in 2026 versus later in the cycle. Put simply, first movers who secure supplier relationships and spectrum‑aligned product roadmaps now capture outsized install-share as operators accelerate rollouts.
BTS Antenna Market -
Technology bets and modularity: Massive MIMO, active antenna units (AAUs), and AI‑integrated beamforming are shifting the value from passive panels to antenna + software stacks. Procurement strategies that favour modular, software‑upgradeable antenna systems have lower lifetime TCO and provide optionality for future 5G‑Advanced and 6G upgrades.
-
OPEX and sustainability as competitive levers: Equipment that demonstrably reduces radio output power and site energy consumption (benchmarks show meaningful per‑site kWh savings in contemporary deployments) will be prioritized by operators concerned with network TCO and ESG targets. Energy efficiency therefore becomes a procurement differentiator, not merely a technical specification.
-
Regulatory and site acceleration: Policies limiting unwarranted municipal friction on tower modifications materially shorten deployment lead times when leveraged correctly. Companies that align permitting playbooks and local regulatory engagement to exploit these frameworks unlock faster time‑to‑market for capacity expansions.
What the PW Consulting BTS Antenna Report Contains (Practical, Decision‑Grade Deliverables)
-
Transparent market sizing and scenario methodology — we document inputs, sensitivity bounds, and alternative demand pathways so leaders can stress‑test strategic plans against low/central/high adoption cases.
-
Operator deployment archetypes and procurement playbooks — tailored buyer’s guides for Tier‑1 MNOs, regional carriers, neutral host providers, and venue integrators that map product selection to business objectives (coverage vs capacity vs energy optimization).
-
Tech roadmap and capability matrices — a commercially pragmatic taxonomy of antenna types, AAU integration levels, and software features that matter for mid‑decade network economics, including upgrade paths for 5G‑A and early 6G concepts.
-
Vendor scorecards and supplier risk matrices — comparative strengths, go‑to‑market footprints, manufacturing scale, IP positions, and integration risk assessments to support sourcing and strategic partnership choices.
-
Site TCO and energy modelling — pro forma models for rooftop, tower, and ground‑based installations enabling rapid scenario comparisons and CapEx/Opex tradeoffs for different antenna architectures.
-
M&A and alliance playbook — thresholds and signals that suggest consolidation opportunities, bolt‑on targets, or partnership candidates aligned with rapid network densification and tech integration.
-
Regulatory risk register — jurisdictional blockers, permitting accelerators, and compliance actions operators and vendors must prioritize to preserve deployment timelines.
Competitive Landscape — How to Read the Field
The BTS antenna market sits in a moderately concentrated structure. Top tier players command a meaningful share of supply, with the leading three firms constituting a majority position and the top five consolidating well over half of market supply. That concentration creates both stability and opportunity: incumbents offer scale and integrated solutions, while specialist vendors and regional champions provide differentiation through cost, form‑factor innovation, or vertical specialization.
-
Ericsson (Stockholm): A leader in high‑performance active and passive base station antennas and Massive MIMO systems. Their recent launch of AI‑ready radios and an expanded software portfolio underscores a shift to combined hardware + AI orchestration as a competitive axis.
-
Huawei Technologies (Shenzhen): Known for AAUs and FDD tri‑band Massive MIMO that reduce tower loading and energy. Vendor designs that are lighter and more power‑efficient materially affect total operating costs for tower‑dependent deployments.
-
Amphenol Corporation (Wallingford): Focuses on high‑performance BTS and small cell antennas, including venue and stadium solutions that address unique sidelobe and coverage constraints in dense venues.
-
CommScope (Claremont): Offers integrated active/passive solutions and DAS infrastructure — a meaningful play for neutral host and enterprise repeatable deployments.
-
ZTE Corporation and Comba Telecom (Shenzhen): Aggressive in AI integration, AIR RAN concepts, and energy‑efficient Massive MIMO designs tailored for rapid capacity builds in high‑growth markets.
-
Radio Frequency Systems (Germany): Longstanding passive panel expertise — attractive for macro coverage bids where field‑proven reliability and serviceability are prioritized.
Recent product activity is a strategic signal: vendors are investing in ultra‑massive MIMO arrays, AI‑integrated beamforming, and venue‑optimized antenna families. Notable recent moves include ZTE’s GigaMIMO evolution (with operator co‑development announced in 2026) and Ericsson’s AI‑ready radio and passive antenna portfolio extensions, which together illustrate the industry’s dual focus on capacity scale and energy efficiency.
Technology & Deployment Dynamics to Watch in 2026
-
Massive/ultra‑massive MIMO and AAU modularity: The competitive premium shifts toward solutions that reduce tower loading, support multi‑band aggregation, and enable software upgrades.
-
Small cell and indoor DAS economics: Venue and indoor solutions are increasingly a distinct procurement track with different KPIs — coverage fidelity, sidelobe control, and interference management trump raw gain.
-
Energy and TCO optimization: Demonstrable per‑site energy reductions and lower output power requirements are buyer priorities; vendors that can quantify kWh savings and lifecycle OPEX advantages win procurement tenders.
-
AI and orchestration: Antennas that integrate with RAN automation and AI for dynamic beam management create operational value by boosting realistic capacity and reducing manual tuning cycles.
How to Use This Intelligence — Practical Next Steps for 2026
-
Procurement leaders: Use our supplier scorecards to re‑benchmark RFPs against energy and software upgradeability criteria; require life‑cycle TCO scoring, not just upfront CapEx.
-
Product and R&D chiefs: Prioritize modular AAU architectures and software hooks for third‑party orchestration; accelerate lab‑to‑field validation with operator partners to shorten commercialization time.
-
Corporate development teams: Monitor vendor product launches and partnerships as M&A signals; the market’s concentration profile suggests M&A activity will be selective but meaningful around capability gaps.
-
Investors and PE firms: Look for targets that combine differentiated antenna IP with scalable supply chain execution and service‑capable business models that convert equipment into recurring revenue streams.
Accessing the Full Report
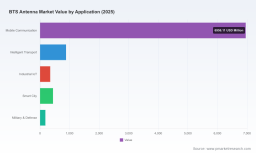
This briefing highlights the strategic contours you need to act in 2026 — but the full PW Consulting BTS Antenna Market report contains the operational detail that converts insight into executable plans: comprehensive segmentation tables, regional and application‑level forecasts, supplier financial overlays, scenario models, installer economics, and playbooks tailored to operators and vendors. To review the proprietary segment matrices and vendor deep dives that we intentionally withheld here, please access the full report through our official distribution channel.
Our team stands ready to translate the report into a bespoke workshop, scenario planning session, or supplier due‑diligence package to accelerate your 2026 decisions. Contact our advisory desk for a confidential briefing and to secure the complete dataset and modelling tools behind this strategic preview.
For detailed analysis of this topic, please visit the official page: BTS Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com