

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Cable Assembly Market to Reach USD 251.8B by 2032 at 6.12% CAGR

Cable Assembly Market — 2026 Strategic Preview
Executive overview
As companies recalibrate supply chains and product roadmaps for a post-pandemic, high‑speed‑connectivity world, the global cable assembly market stands out as a foundational enabler across automotive, data communications, industrial automation and medical electronics. Our PW Consulting analysis uses a 2025 base and a 2026–2032 forecast window to quantify this transition: the industry expanded materially through the early 2020s, reaching broadly high‑double‑digit billions by 2025, and is projected to continue at a steady mid‑single‑digit compound annual growth rate (CAGR) through 2032. That combination of scale and sustained growth makes cable assemblies both a defensive procurement priority and an offensive product play for original equipment manufacturers (OEMs), contract manufacturers and component suppliers alike.
Cable Assembly Market
Why this study matters for 2026 decision cycles
-
Capital allocation and plant strategy — With predictable growth and rising technical complexity, the right mix of greenfield capacity, retrofit automation and contract manufacturing partnerships will determine winners in 2026–2028.
Cable Assembly Market -
Product roadmap alignment — High‑speed interconnects, co‑packaged solutions and fiber adoption are no longer niche. Firms must prioritize capability bets now to avoid multi‑year qualification delays.
Cable Assembly Market -
Supply‑chain resilience — Volatility in copper and optical fiber markets, along with region‑specific manufacturing economics, requires firms to lock in raw material strategies and alternate sourcing lanes.
-
Regulatory readiness — Export controls, defence solicitations and industry standards (including hazardous‑environment certifications) are erecting new barriers to entry for suppliers and new checkpoints for OEM procurement teams.
-
M&A and partnership timing — The market’s concentrated but not consolidated profile creates opportunities for bolt‑on deals that add technical depth, scale or geographic reach.
Data‑driven context
Readers should anchor their plans to a simple, objective yardstick: the cable assembly market reached a substantial baseline by the 2025 reporting year and is forecast to expand materially over the 2026–2032 horizon at a CAGR of approximately 6.12%. This trajectory reflects the combined effects of faster data links in compute and telecom infrastructure, the electrification and sensor proliferation in vehicles, the reshoring of certain industrial supply chains, and an ongoing modernization of medical and industrial instrument platforms. Market concentration metrics also matter: the top three and five players account for a meaningful share of revenue, indicating a landscape where scale confers advantage, but specialization and local footprint still create white‑space opportunities.
Key market dynamics to incorporate into 2026 planning
-
High‑speed interconnect acceleration — Recent product introductions and standards work indicate an industry pivot toward higher aggregate channel speeds and denser interconnect topologies. Compression‑based on‑substrate connectors and assemblies supporting PAM‑4 signaling are examples of near‑term technical enablers for next‑gen compute and semiconductor test applications.
-
Copper and fiber supply tension — Price and availability trends for copper and optical fiber are increasingly relevant inputs to cost models. Procurement teams should model multi‑scenario sourcing and hedging, and product teams should evaluate hybrid designs that optimize for both performance and bill‑of‑materials stability.
-
Standards and certification friction — IEC and other domain‑specific certifications (including those for hazardous environments) are becoming gating factors for market access in industrial segments and certain defense contracts. Early investment in certification pathways accelerates time to qualified status.
-
Geographic manufacturing calculus — Tariff treatment, labour productivity, and export‑supportive policy in manufacturing hubs affect landed cost and speed to market. Contract manufacturing footprints in Southeast Asia continue to offer leverage, while nearshoring remains attractive for high‑mix, low‑volume custom work.
-
Defense and public‑sector demand signals — Government solicitations and export‑control regimes introduce episodic demand — and procurement complexity — that suppliers must be prepared to address through compliance processes and secure supply lanes.
Competitive landscape — strategic implications
The competitive map mixes large, diversified interconnect players with nimble, specialist EMS and harness manufacturers. This mix shapes where to compete and how to partner:
-
Global interconnect leaders — Firms with broad product portfolios and scale are extending into higher‑speed assemblies and sensor interconnects. These incumbents compete on engineering depth, global supply networks and direct OEM relationships.
-
Technical challengers — Companies focused on high‑speed and co‑packaged solutions are creating new performance baselines that raise customer expectations and shorten product cycles.
-
Regional and contract manufacturers — Several Asia‑based manufacturers and specialized US suppliers are prioritizing rapid turnaround, custom harnessing and PCB integrations to serve EV, robotics and medical OEMs. Their cost structures and agility make them attractive partners for high‑mix, low‑volume programs.
Recent industry moves reinforce these dynamics: a leading connector supplier launched a compression‑based co‑packaged copper solution supporting advanced PAM‑4 signaling; another specialized manufacturer announced capacity expansions targeting automotive and aerospace contract work; industry forums continue to spotlight manufacturing process improvements for copper and fiber assembly. PW Consulting’s competitive profiles in the full report synthesize these moves into supplier scorecards, capability heatmaps and preferential partner lists tailored to different buyer archetypes.
What the full PW Consulting report delivers (practical toolkit)
-
Scenario‑based financial model — interactive demand and cost scenarios that stress raw material volatility, regional footprint shifts and speed‑to‑market assumptions.
-
Supplier scorecards — comparative capability and risk assessments across engineering, quality, capacity, lead time and compliance readiness.
-
Product‑market fit matrices — prioritized roadmaps mapping connector and cable technologies to end‑market adoption timelines and qualification effort.
-
M&A and partnership playbook — target archetypes, valuation heuristics, integration risk checklists and a shortlist of acqui‑build candidates.
-
Procurement negotiation levers — indexed pricing strategies, long‑term supply contracting templates and inventory optimization approaches for critical raw materials.
-
Regulatory and compliance checklist — stepwise actions to meet export control, defense procurement and IEC certification requirements that commonly delay program ramps.
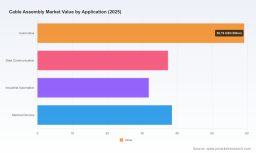
These deliverables are designed as operational tools to be used directly in budgeting, sourcing RFIs, and board‑level strategy sessions. To preserve commercial sensitivity and the integrity of supplier data, core segment tables and granular regional or application breakouts are available only in the full report.
Actionable recommendations for 2026 (prioritized)
-
0–6 months — Lock in raw material arrangements for copper and fiber via a mix of forward contracts and qualified alternates; initiate engineering pilots for high‑speed assembly approaches that reduce downstream qualification time.
-
6–18 months — Invest selectively in automation for high‑mix harness assembly and in test capabilities for PAM‑4 and equivalent signaling; pursue at least one strategic partnership or alliance to accelerate co‑packaged optics or high‑density cable solutions.
-
18–36 months — Evaluate M&A to acquire scale in targeted geographies or verticals (medical, aerospace defense, data‑center interconnects) and implement a regional manufacturing mix that balances cost, lead time and compliance risk.
-
Cross‑timeline — Build a compliance and defense‑contracting competency if pursuing government work; incorporate dynamic pricing clauses tied to raw material indices to protect margins in volatile markets.
Conclusion — positioning for competitive advantage
For executives making 2026 investment decisions, the cable assembly market presents a classic incumbency‑plus‑innovation challenge: incumbent scale and engineering breadth matter, but differentiated capabilities in high‑speed interconnects, supply‑chain resilience, and regulatory readiness will decide who captures the next wave of demand. PW Consulting’s full Cable Assembly Market report provides the granular segmentation, supplier benchmarking, and scenario analytics you need to convert these strategic imperatives into executable plans. The executive summary here highlights the trends; the complete report contains the line‑level data, validated supplier profiles and modelling templates required to act with confidence.
Next step
Contact PW Consulting to access the full report and the interactive forecast model — gain the segment‑level forecasts, supplier scorecards and procurement playbooks you will need to operationalize your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Cable Assembly Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com