

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thermoplastic Prepreg Market to hit USD 0.96B by 2032 at 12.53% CAGR

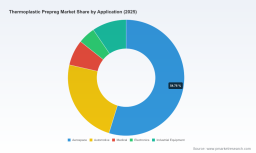
Thermoplastic Prepreg Market — Strategic Outlook for 2026 Decision‑Making
As thermoplastic prepreg solutions move from niche to commercial scale, the decisions you make in 2026 will determine whether your organization captures the structural, throughput and sustainability advantages that the technology promises. PW Consulting’s market study uses a 2025 base year, traces historical dynamics from 2020–2025, and provides a granular forecast through 2032. The headline macro view: the global thermoplastic prepreg market is on a sustained expansion path (CAGR ~12.53% across the forecast window), growing from an early commercial base in 2025 to a market approaching USD 1.0 Billion by 2032. This briefing outlines why that growth matters to executives and how the full report equips teams to act — while holding back the segmented line‑by‑line minutiae to encourage access to the full dataset and models.
Thermoplastic Prepreg Market
Why this research is mission‑critical for 2026 decisions
-
Timing of capacity investments — The market’s double‑digit CAGR creates a window in 2026 where first‑mover investments in production capacity, tooling and certification can lock in multi‑year revenue streams. The study identifies the demand inflection points and the realistic lead times required to monetize new lines.
Thermoplastic Prepreg Market -
Technology selection and product roadmap alignment — Thermoplastic prepregs span a range of resin systems and fiber architectures. Our analysis clarifies which resin classes and curing strategies are commercially proven today and which are poised for adoption, enabling R&D and product management to prioritize projects with the strongest near‑term ROI.
Thermoplastic Prepreg Market -
Supply‑chain risk management — Specialist resins and continuous fiber reinforcements are core inputs. The research quantifies supply concentration, identifies pinch points and provides contracting and hedging strategies to maintain production continuity while containing input cost volatility.
-
Compliance and market access — Certification pathways (notably aerospace NADCAP, and emerging carbon accounting standards) are a gating factor for many end markets. The study maps certification timelines, costs and competitive advantages tied to compliance.
-
M&A and partnership playbooks — With a market that is meaningful but not highly consolidated, the study outlines acquisition targets, JV structures and valuation benchmarks that support inorganic strategies to scale quickly.
What the PW Consulting report contains (practical, executable content)
-
Top‑down market sizing and a 2026–2032 forecast model built on scenario engines that allow executives to stress test demand drivers, pricing paths and supplier disruption events.
-
Segmentation by geography, resin family and end‑use application — presented with interpretive commentaries, demand drivers and qualitative growth vectors. (Note: detailed segment share tables are reserved for the full report.)
-
Competitive landscape and supplier playbooks — in‑depth company profiles, capability maps, product stacks and go‑to‑market strengths for leading vendors to support partner selection and RFx strategies.
-
Manufacturing, processing and cycle‑time benchmarks — empirical comparisons between thermoplastic and thermoset processes with implications for capital equipment, factory layout and throughput economics.
-
Raw material cost analysis and procurement levers — price sensitivity models for specialized resins and fibers, plus recommended contracting structures to reduce exposure to short‑term price swings.
-
Regulatory and sustainability roadmap — stepwise requirements for NADCAP accreditation and carbon accounting (ISO 14067) with estimated time‑to‑certification and likely commercial benefits.
-
Commercial frameworks — sample supplier scorecards, term sheet templates for long‑lead resin supply, customer qualification checklists and pilot program roadmaps to accelerate qualification in aerospace and EV applications.
-
Advanced analytics and valuation tools — downloadable financial models for business case development, break‑even calculators for CAPEX investments and acquisition valuation heuristics calibrated to actual deal activity.
High‑level, data‑driven takeaways (the “need‑to‑know”)
-
Market trajectory: The market is growing rapidly from a relatively small commercial base in 2025 toward near‑billion‑dollar scale by the end of the forecast horizon — a growth path consistent with broadening adoption across aerospace, automotive electrification and industrial applications.
-
Consolidation potential: Market concentration is moderate — the top three players do not dominate the market entirely, and the top five capture less than half of total value. This structure creates space for entrants that combine technological differentiation with regulatory qualification to gain share quickly.
-
Value drivers: Winning firms combine three capabilities — advanced resin systems, repeatable manufacturing processes that reduce cycle times, and recognized certifications that unlock high‑value end markets (notably in aerospace and defense).
-
Near‑term commercial windows: Rapid‑cure thermoplastic systems and applications that demand damage tolerance and recyclability (e.g., EV powertrain components, selected aerospace substructures) are the most actionable targets for commercialization in 2026–2028.
Competitive landscape: who to watch (profiles and strategic posture)
-
Toray Industries, Inc. (Japan) — Offers a broad portfolio of thermoplastic UD tapes and prepregs across PEI, PAEK, PESU and PA‑based matrices, with clear emphasis on aerospace and automotive applications. Toray’s product breadth and ongoing trade show presence signal both R&D depth and aggressive market engagement. Recent activities include major conference exhibition in May 2025 and a product launch in February 2026 that extended their aerospace‑grade prepreg systems.
-
Teijin Limited (Japan) — Focused on thermoplastic UD and woven prepregs across PEEK, PPS, PAEK and PA matrices. Teijin’s positioning underscores fiber‑resin system integration, with strengths in industrializing prepreg formats for high‑volume applications.
-
Hexcel Corporation (USA) — Known for rapid‑cure and aerospace‑grade thermoplastic systems (including PEKK-based offerings). Hexcel’s presence at recent industry showcases reflects a strategy to translate aerospace pedigree into multi‑market opportunity, backed by NADCAP‑aligned manufacturing processes.
-
SGL Carbon SE (Germany) — Supplies thermoplastic‑compatible prepregs and towpregs with a particular focus on automotive and industrial segments where assembly and damage tolerance are critical.
-
Ensinger GmbH (Germany) — Delivers a range of semi‑prepregs and prepregs for carbon/glass fiber‑reinforced thermoplastics, focusing on tailored materials for specific manufacturing routes.
Recent vendor activity that shapes 2026 choices
-
May 2025 — Toray exhibited thermoplastic composite solutions at a major industry conference, highlighting EV rotor sleeve and aerospace use cases. The presence underscores market education and customer engagement as an on‑ramp for adoption.
-
February 2026 — Toray launched next‑generation PEI UD tape prepregs and a new prepreg system aimed at aerospace and space markets — an example of product advancement tied to certification‑oriented markets.
-
March 2026 — Hexcel showcased new PEKK/IM7 thermoplastic systems focused on structural aerospace applications, emphasizing both material innovation and rapid processing capabilities.
Supply‑chain, raw‑material and regulatory dynamics
-
Raw materials: Specialized thermoplastic resins and continuous carbon/glass fibers are the linchpin of value creation. Continuous fiber reinforcement enables faster cycle times and higher damage tolerance relative to traditional thermosets; however, resin supply chains are narrower and require strategic sourcing.
-
Manufacturing & certification: NADCAP accreditation is increasingly becoming a prerequisite for aerospace qualification and is a clear entry barrier. ISO 14067 carbon footprint tracking is emerging for select product lines and impacts procurement decisions among sustainability‑driven OEMs.
-
Commercial implications: Buyers and OEMs will increasingly select suppliers that combine certified processes with verifiable lifecycle footprints. That creates a premium for suppliers who invest in accreditation and transparent emissions accounting early.
Recommended strategic moves for 2026 (prioritized)
-
Secure strategic resin and fiber agreements now. Given lead times and concentrated suppliers, execute multi‑year supply contracts or develop backward integration options for critical resin chemistries.
-
Pursue certification‑first product development. If aerospace or defense is a target market, budget certification track time and cost into your 2026 roadmap — NADCAP alignment can be the difference between pilot orders and production contracts.
-
Establish pilot programs with tier‑one OEMs focused on high‑value use cases (EV structural components, aerospace substructures). Use pilots to build qualification data and to optimize processing parameters for scale‑up.
-
Prioritize modular, rapid‑cure systems in capital planning. Factory investments that reduce cycle times and support versatile resin systems will produce superior throughput economics as demand scales.
-
Pursue selective M&A or JVs to acquire missing capabilities (certification, resin expertise, factory capacity). Given the current market concentration profile, targeted acquisitions can accelerate market entry without bearing full R&D costs.
-
Integrate carbon accounting into commercial proposals. Early adoption of ISO 14067‑style reporting will win procurement shopping lists where lifecycle emissions are a procurement criterion.
Conclusion — how PW Consulting accelerates your 2026 roadmap
Thermoplastic prepregs are transitioning from specialist applications to a phase of broader commercial adoption. For 2026, the imperative is clear: move from exploratory projects to credentialed, supply‑assured production strategies that align with regulatory and sustainability requirements. PW Consulting’s full report provides the detailed segment tables, supplier scorecards, unit‑cost models and downloadable forecast engines you need to convert strategic intent into executable programs. To access the complete dataset, segmented demand models and vendor playbooks essential for board‑level decision making, request the full report from PW Consulting’s market intelligence team.
For detailed analysis of this topic, please visit the official page: Thermoplastic Prepreg Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com