

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Track Geometry Systems Market to Reach USD 563.5M by 2032 at 5.23% CAGR

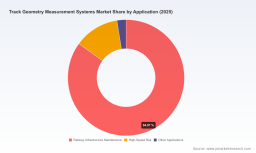
Track Geometry Measurement Systems Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
As rail operators, infrastructure owners, OEMs and investors enter 2026, Track Geometry Measurement Systems (TGMS) are moving from niche monitoring tools to mission‑critical infrastructure assets. PW Consulting’s latest study — with base year 2025 and a forecast window through 2032 — projects continued, steady expansion driven by regulation, network renewal programmes and a wave of sensor-driven automation. The global market, tracked in USD (Million) terms, rose materially over the 2020–2025 period and is forecast to grow at a compound annual growth rate (CAGR) of approximately 5.23% through 2032.
Track Geometry Measurement Systems Market
Why this briefing matters for 2026 strategy
Decisions made in 2026 will lock in technology platforms, procurement frameworks and data architectures that remain in place for a decade or more. The TGMS market is at an inflection point where three structural forces intersect:
Track Geometry Measurement Systems Market
- Regulatory tightening and a shift toward data‑driven compliance models;
- Rapid maturation of sensor suites and autonomous collection platforms; and
- Capital allocation choices by rail owners between preventative digital monitoring and traditional manual maintenance.
PW Consulting’s research quantifies the market trajectory and maps actionable options for stakeholders making these 2026 investments — from equipment selection and integration to service economics and M&A prioritisation.
Track Geometry Measurement Systems Market
Market trajectory at a glance (context, not a substitute for the report)
Over the historical window (2020–2025) the market demonstrates steady recovery and expansion, reflecting both infrastructure spend and replacement cycles. Our base‑year sizing captures a market that established a new baseline in 2025; from that foundation the forecast envelope through 2032 shows sustained growth as digital track monitoring becomes a standard component of asset management strategies. The report models multiple demand channels, scenario stress‑tests and a central forecast that embeds a 5.23% CAGR.
What the full study delivers (practical, operational intelligence)
This publication is not an academic overview — it is a tactical playbook intended for leaders who must decide procurement, deployment and partnership strategies in 2026. Key deliverables include:
- Validated market sizing and trend decomposition (historical and forecast) expressed in USD (Million) with base‑year 2025 and a 2026–2032 forecast horizon.
- Decision matrices for technology selection (laser, IMU, non‑contact optical, and integrated autonomous systems), including operational pros/cons and integration risk assessments.
- Vendor benchmarking and competitive positioning frameworks (product capability, rail compatibility, service footprint, and go‑to‑market models).
- Deployment case studies and field ROI templates showing total cost of ownership over common procurement lifecycles.
- Regulatory compliance playbook aligned to recent rule changes and likely near‑term policy shifts.
- M&A target screening and supplier due‑diligence checklists tailored for strategic acquirers and private equity.
Note: This briefing intentionally summarises the report’s thrust. Detailed segment tables, granular regional and application splits, and line‑by‑line vendor revenue comparisons are available exclusively in the full report to preserve primary‑source integrity and proprietary modelling detail.
Competitive landscape — who sets the pace
The TGMS market is moderately concentrated: the three largest providers capture a material share of industry revenues, and the top five firms deepen that control. This concentration produces clear implications for pricing power, channel reach and technology standards.
- Holland LP (Crete, IL, USA) — strong in portable inspection and UGMS solutions that service hi‑rail vehicles and locomotives. Recent product iterations position Holland to win contracts where portability and rapid field inspection are priorities.
- Protran Technology (West Columbia, SC, USA) — focuses on hy‑rail integration and FRA‑compliant, real‑time geometry capture. Their systems appeal to operators seeking retrofit options that minimize vehicle downtime.
- ENSCO Rail (USA) — a strategic integrator with both TGMS and autonomous variants (ATGMS). ENSCO’s recent contract awards and international deliveries underscore its ability to scale complex installations across rolling stock types.
- ADTS Srl (Noale, Italy) — specialist in non‑contact measurement systems designed for robust performance in diverse environmental conditions; competitive in markets demanding continuous, high‑precision scans.
- Avante International Technology, Inc. (Princeton Junction, NJ, USA) — positions itself around real‑time autonomous systems mounted on locomotives, with emphasis on continuous defect detection.
- Plasser & Theurer (Austria) — integrates sensor suites into heavy maintenance and high‑speed machines, targeting operators that combine measurement and immediate corrective action.
Recent vendor activity — product launches, exhibition showings, and contract wins — signals three dynamics: (1) modular product roadmaps that facilitate retrofits; (2) emphasis on autonomous and continuous monitoring platforms; and (3) geographic expansion via service partnerships and targeted fleet deliveries.
Regulatory, supply and operational headwinds
A set of non‑market forces will materially affect both procurement timing and technology adoption in 2026:
- Regulation: The release of updated compliance guidance in 2026 (covering gage, alignment and surface requirements) tightens expectations around measurement frequency and data fidelity. Parallel rule‑change petitions seek to allow TGMS outputs to substitute some visual inspections — creating both compliance opportunity and transitional ambiguity.
- Raw materials and cost inflation: Elevated steel pricing and tariff dynamics have pushed input costs higher for maintenance machines and track repair campaigns, increasing the relative appeal of condition‑based monitoring but also squeezing capex budgets.
- Labor and workforce pressures: Operator associations are actively seeking relief by substituting automated measurement datasets for certain manual inspection frequencies — a trend that will accelerate demand for certified, auditable TGMS outputs.
Strategic implications for 2026 procurement and investment
For executives planning purchases or strategic moves in 2026, the study recommends treating TGMS as both a hardware and a data investment. Specific implications include:
- Prioritise interoperability: Select platforms with open data architectures and industry standard outputs to future‑proof investments and ease integration with asset management systems.
- Design procurement around lifecycle economics: Evaluate sensor lifetime, calibration cadence, and software subscription costs alongside unit price; total cost of ownership frequently reverses initial “cheapest” choices.
- Accelerate pilot deployments tied to regulatory use cases: Use targeted pilot programmes to validate the substitution of TGMS data for defined visual inspection tasks where regulators are receptive.
- Consider strategic partnerships: Where OEMs lack systems integration capabilities, partnerships with established integrators can shorten time‑to‑value and reduce operational risk.
- Map consolidation and M&A opportunities: Market concentration and technology fragmentation create arbitrage for larger players and financial sponsors seeking economies of scale in services and software.
How PW Consulting’s report supports 2026 decisions
Executives who use our report receive more than forecasts. They gain operational tools and board‑level artefacts to defend investment choices in 2026. Deliverables include vendor shortlists matched to specific use cases, scenario models that stress test budgets against commodity shocks and regulatory pivots, and executable roadmaps for moving from pilot to fleet‑wide deployment.
Closing and next steps
The TGMS market in 2026 presents a classic strategic trade‑space: near‑term capital constraints versus long‑term risk mitigation and efficiency gains. PW Consulting’s study documents the market’s size, growth trajectory, competitive contours and the tactical levers available to buyers and investors. For readers evaluating procurement, partnerships or acquisition targets this year, the report provides the granular segmentation, scenario runs and vendor economics necessary for decisive action.
To access the detailed segment breakdowns, vendor scorecards and proprietary financial models that underlie these strategic recommendations, consult the full PW Consulting Track Geometry Measurement Systems Market report — the only place where our complete tables, step‑by‑step deployment templates and source datasets are published in full.
For detailed analysis of this topic, please visit the official page: Track Geometry Measurement Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com