

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 1,6-Hexanediol Market to Reach USD 2,391M by 2032 at 7.5% CAGR

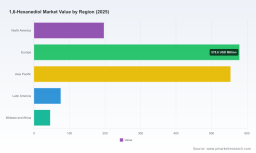
1,6-Hexanediol Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concise, high-value briefing that frames the strategic levers corporate leaders must prioritize in 2026. This preview synthesizes the macro trajectory, competitive dynamics, supply-chain stress points, and technology inflection that will determine winners and laggards in the 1,6-Hexanediol market over the 2026–2032 forecast window. It is designed as a decision-support primer: deep enough to inform immediate strategic choices, intentionally withholding granular segment-by-segment tables and proprietary model outputs that are available in the full study.
1,6-Hexanediol Market
Market snapshot: trajectory, scale and concentration
After a steady recovery from 2020, the global 1,6-Hexanediol market reached approximately USD 1,450 million in 2025 (base year). Our model projects a compound annual growth rate (CAGR) of 7.5% through the 2026–2032 forecast period, taking total market value to roughly USD 2,391 million by 2032. The market climbs to about USD 1,559.6 million in 2026 and accelerates into the early 2030s as higher-value applications and formulation innovations expand demand.
1,6-Hexanediol Market
Market structure remains moderately concentrated: the three largest producers control roughly 45% of global capacity, with the top five accounting for approximately 58%. That concentration creates zones of pricing power and capacity-driven cycles that buyers and investors must factor into scenario planning.
1,6-Hexanediol Market
Why this matters for 2026 corporate strategy
- Timing of investment decisions: With the market expanding meaningfully in 2026, capex choices made this year will influence competitiveness through the next capacity cycle. Firms that secure feedstock-integrated positions or differentiated, low-carbon product streams can lock in margin advantages.
- Procurement posture: Given periodic tightness episodes and transport-cost volatility, procurement strategies should move from single-year spot tactics to multi-year, index-linked arrangements and strategic inventory buffering tailored to product-grade requirements.
- Product and portfolio prioritization: End-markets that value performance or sustainability premiums will determine where to focus higher-margin product development and marketing; commodity-grade channels require different risk-management tactics.
- M&A and partnership timing: Moderate concentration and regional capacity imbalances create mid-term M&A opportunities—particularly for buyers seeking backward integration or novel process IP.
Competitive landscape — what the preview reveals
The competitive map is dominated by established chemical majors and regionally strong producers. Key industry participants include LANXESS, BASF SE, Huntsman Corporation, Perstorp AB, Mitsubishi Chemical Corporation, Eastman Chemical Company, and a number of Asian producers such as Shandong Huasheng Group, Prasol Chemical Ltd, and Zhejiang Jianye Chemical. Each brings distinct strategic advantages:
- LANXESS (Germany) — Known for high-purity grades and a growing suite of sustainability-focused variants (Scopeblue®). Recent commercial moves include a price increase in February 2024 amid market tightness, signaling disciplined pricing when capacity utilization climbs.
- BASF SE (Germany) — A broad industrial platform that has secured verification for a lower-carbon product variant (certified in November 2024, with verification valid into 2026). This creates an immediate marketing and procurement differentiator for sustainability-conscious customers.
- Huntsman (USA), Eastman (USA), Mitsubishi (Japan), Perstorp (Sweden) — These firms combine global distribution with application expertise in polyurethanes, polyesters, coatings and specialty chemistries, enabling cross-selling and formulation partnership opportunities.
- Regional manufacturers (China, India) — Firms such as Shandong Huasheng, Prasol, and Zhejiang Jianye provide price-sensitive supply and regional agility. Their presence keeps global spot dynamics competitive, especially for large-volume buyers in Asia.
Our competitive analysis in the full study includes supplier scorecards, capital-cost estimates, and scenario-driven margin curves; this preview limits those detailed matrices, but the strategic implications are clear: scale, product differentiation (purity and low-carbon claims), and secured feedstock access will define relative performance in 2026.
Supply-chain and technology dynamics shaping 2026
- Feedstock and process tech: The predominant production route remains adipic-acid based chemistry. Technology platforms such as Johnson Matthey’s esterification process enable near-complete conversion of adipic feedstock and are central to improving yield and unit economics for new and retrofit plants.
- Environmental and regulatory pressure: Stringent emissions and lifecycle scrutiny around adipic-acid-derived processes are accelerating efforts to reduce raw-material carbon intensity and improve catalyst systems. Academic and industrial research in 2024–2025 highlighted catalyst improvements as a near-term pathway to both cost and environmental performance gains.
- Logistics and cost volatility: Early 2026 transport surcharges and broader specialty-chemical logistics inflation have materially impacted landed costs for diols. For buyers and integrated producers alike, this raises the strategic value of localized supply, flexible packaging, and transport-contract innovations.
- Commercial levers: Price adjustments, like LANXESS’s 2024 increase, show vendors’ willingness to pass through tightness into the market. Simultaneously, sustainability-verified SKUs (e.g., BASF’s verified lower-carbon product) are beginning to command premium positioning in bid situations.
What the full PW Consulting report delivers (practical, actionable content)
Our full study is structured as a practitioner’s playbook. Key modules are:
- Comprehensive market model (historical 2020–2025 and detailed 2026–2032 forecast) with scenario toggles for demand, price and feedstock shocks.
- Demand-by-application and regional build-up with sensitivity testing against automotive electrification, construction cycles, electronics miniaturization and footwear material shifts. (Note: This preview intentionally withholds the explicit segmentation tables and value splits; they are available in the full report.)
- Supplier benchmarking and a proprietary scorecard covering capacity, purity grades, sustainability credentials, and commercial flexibility.
- Capex and capacity map identifying brownfield/greenfield opportunities and time-to-market estimates for incremental supply.
- Price outlook and volatility scenarios incorporating transport-cost stress, raw-material feedstock scenarios, and likely competitive responses to sustained tightness.
- Regulatory and sustainability tracker mapping relevant certifications, lifecycle claims, and regional compliance risks impacting sourcing and product claims through 2026.
- Strategic playbook: procurement approaches, partnership structures, M&A screens, and go-to-market strategies for differentiated product SKUs.
Each module pairs data-driven output with practical templates—supplier RFP scorecards, emissions-accounting checklists, and capex payback calculators—so teams can convert insight into action quickly.
Strategic imperatives for 2026
- Secure feedstock optionality: Whether through feedstock integration, long-term contracts, or co-processing agreements, reducing exposure to adipic-acid market swings and transport surcharges must be prioritized.
- Differentiate on sustainability and performance: Verification and lower-carbon labeling are not marketing niceties; they are procurement filters for many OEMs and formulators. Investing in verified low-carbon grades or gaining certification through recognized schemes presents near-term commercial upside.
- Optimize capacity timing: With market growth accelerating and concentration favoring large incumbents, timing greenfield investments to anticipated tightness windows and leveraging modular, fast-deploy technologies can yield outsized returns.
- Adopt dynamic procurement and pricing playbooks: Contract structures that blend indexation with flexibility, and a playbook for short-term tactical buys during dislocations, will protect margins without sacrificing supply continuity.
- Monitor catalyst and process innovations: As environmental restrictions push producers to refine catalyst systems, companies that partner with licensors or invest in demonstrated process improvements can gain both cost and compliance advantages.
How to use this preview and where to go next
This briefing is intended to frame the critical strategic questions you should be asking today. The full PW Consulting 1,6-Hexanediol Market study (base year 2025; historical 2020–2025; forecast 2026–2032) contains the granular segmentation, supplier-by-supplier financial profiles, and downloadable modelling files required to operationalize the recommendations above.
If your priority in 2026 is to move from insight to implementation—whether that is negotiating supplier agreements, planning a targeted capacity expansion, or developing a sustainability-led product roadmap—the full report supplies the actionable datasets and templates. The preview purposely omits the detailed segmentation tables and raw model exports to preserve the integrity of our proprietary analysis and to guide stakeholders to the full, interactive deliverable.
Closing
In a market growing at an expected 7.5% CAGR and moving from USD ~1.45 billion in 2025 toward a substantially larger global opportunity in the early 2030s, the right combination of supply-security, sustainability differentiation, and tactical commercial agility will define winners. PW Consulting’s full report equips decision-makers with the models, scenarios and playbooks needed to convert market signals into profitable action in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: 1,6-Hexanediol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com