

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vegetable Seed Market to hit USD 10,888.79M by 2032 at 6.5% CAGR

Vegetable Seed Market — Strategic Preview for 2026 Decision-Making
Executive summary
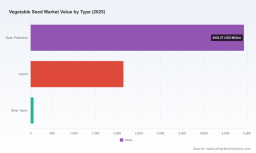
The vegetable seed market entered 2026 from a position of steady expansion and structural change. Using a 2025 base year, our modeling traces growth from approximately USD 5,252 million in 2020 to roughly USD 7,143 million in 2025, and projects a continuation of that trajectory to about USD 10,889 million by 2032 under a 6.5% compound annual growth rate for the forecast window. That topline trajectory masks important structural shifts — evolving grower economics, new regulatory constraints, concentrated supplier power and accelerating breeding and distribution innovations — all of which materially affect near‑term strategic choices for seed companies, input distributors and large commercial growers.
Vegetable Seed Market
Why this matters for 2026 corporate strategy
- Capital allocation should be selective and scenario‑based. With growth intact but market outcomes sensitive to regulatory and trade shocks, investment committees must prioritize projects that improve breeding throughput, shorten time‑to‑market for high‑value traits, or materially reduce per‑unit production costs.
- Portfolio prioritization will determine margin capture. Companies that can align R&D pipelines to fast‑growing value pools (quality, disease resistance and traits for controlled‑environment production) will outpace peers even without expanding acreage.
- Distribution and contract strategy are becoming a competitive lever. As buyers seek traceability, certification and reliable supply, firms that lock in integrated distribution agreements or exclusive service bundles will preserve pricing power.
- Regulatory readiness is an operational necessity. Labeling, certification and interstate/ cross‑border rules introduced or amended in 2025–2026 can increase compliance cost and time‑to‑market unless proactively managed.
- M&A and partnerships should be executed with precision. The market’s midstream concentration and the premium on breeding platforms imply targeted bolt‑on acquisitions or co‑development contracts can accelerate capability builds at lower risk than greenfield R&D.
Market dynamics shaping outcomes
Several cross‑cutting dynamics will define winners and losers in 2026:
Vegetable Seed Market
- Price inflation and input cost pressure. The sector has seen notable increases in pack and commercial seed prices; commercial packets have risen materially over recent years. Companies must decide whether to pass costs through, absorb margin compression, or redesign product packs and service models to retain customers.
- Regulatory tightening and fragmentation. Recent and pending regulatory actions — from federal seed labeling requirements to state seed certification regimes and amendments to labelling rules in major markets — are increasing compliance complexity. Firms with disciplined regulatory affairs functions will win time‑to‑market and avoid costly reworks.
- Geopolitical trade shifts. Tariff and trade policy changes enacted in 2025 and enforced in 2026 are re‑routing seed flows and redefining sourcing risk. Supply diversification and nearshoring are now legitimate strategic options for reducing exposure to import disruption.
- Technological acceleration in breeding and treatments. Investments in breeding platforms, gene editing adjacency, and seed treatment technologies are shortening development timelines. The opening of new R&D facilities and targeted field days by major players underscores an industry pivot to speed and demonstrable product performance.
- Market concentration amplifies strategic pricing and access dynamics. The market exhibits meaningful supplier concentration among leading firms. This concentration creates both barriers to entry in certain channels and opportunities for mid‑size players to specialize in niche varietals or service bundles.
Competitive landscape — what to watch in 2026
The competitive topology of the vegetable seed sector blends global incumbents with strong regional specialists. Key firms are deploying complementary strategies: scale via portfolio breadth, capability via breeding investments, and reach via distribution partnerships.
Vegetable Seed Market
- Syngenta (Basel, Switzerland) — A global leader continuing to invest heavily in innovation, most recently visible through its field days and the commissioning of new R&D infrastructure aimed at compressing breeding cycles.
- Bayer (Leverkusen, Germany) — Operating through established brands, the company’s strategy emphasizes premium varieties and integrated solutions for commercial growers.
- Sakata Vegetable Seed (Woodland, California, USA) — A commercial‑market focused supplier that leverages strong regional relationships and trade show presence to maintain grower connectivity.
- Enza Zaden (Enkhuizen, Netherlands) — Specialist producer with a strategic global production footprint designed to balance seasonality and quality standards.
- BASF / Nunhems (Ludwigshafen, Germany) — Offering a broad crop portfolio, recent distribution collaborations underscore a drive to strengthen greenhouse category presence.
- Vilmorin (Paris, France) — Emphasizes professional grower relationships and varietal reliability.
- Regional and specialty suppliers — Firms such as Harris Seeds, Seedway, Renee’s Garden, Park Seed and Jung Seed continue to command loyalty in their niches through catalog depth, organic/heirloom options and grower support services.
Recent industry actions illustrate two immediate strategic themes: (1) heavy, visible investment in R&D platforms and field demonstration programs to shorten adoption cycles (examples include new tech centers and ‘future of veg’ field days), and (2) distribution partnerships and workshop consortia that de‑risk adoption of new varieties in protected and open systems.
What the report delivers — practical, decision‑grade modules
PW Consulting’s full Vegetable Seed Market study is designed as a toolbox for 2026 execution. Highlights include:
- Transparent market architecture and methodology. Clear definitions, base‑year calibration and reproducible forecasting logic for demand and supply dynamics.
- Topline and scenario forecasts. Multiple demand scenarios to stress‑test investment cases across macro, soft‑path (technology adoption) and downside (trade/regulatory shock) outcomes.
- Regulatory & trade risk matrix. Actionable maps of jurisdictional obligations and trade exposures with mitigation playbooks for each major market.
- Grower economics and pricing frameworks. Worksheets and decision trees that translate varietal performance into per‑acre economics for both open‑field and controlled‑environment growers.
- Supply chain and procurement playbook. Sourcing strategies, contract templates and near‑term tactics for hedging raw material and certification risk.
- Competitive intelligence dossiers. Condensed but operationally framed profiles of leading firms, plus signals to monitor for opportunistic M&A or partnership windows.
- Commercial playbooks and KPI dashboards. Go‑to‑market sequencing, channel optimization tools, and scorecards for trial conversion, grower retention and margin recovery.
- M&A and partnership screening tools. A short list of capability gaps and due‑diligence checklists designed to accelerate inorganic value capture while limiting integration drag.
How to use this intelligence in 2026 — a pragmatic checklist
- Run a 90‑day “strategic triage” using the report’s scenario models: identify top 3 exposures and top 3 investable opportunities.
- Establish a regulatory watch cell to manage labeling, certification and trade developments highlighted in the study.
- Prioritize breeding and product launches that improve yield per hectare or command premium pricing in controlled‑environment systems.
- Reassess distribution contracts with the top 10 channel partners using the commercial scorecard from the report to preserve margin and service levels.
- Screen potential bolt‑on assets using the M&A checklist and concentration analysis to determine whether to pursue capability buys or co‑development arrangements.
Final note — the trailer promise
This article is intended as a strategic preview: it demonstrates the type of insight, operational tools and scenario analytics PW Consulting brings to executive teams planning for 2026. The full report contains the granular segmentations, detailed regional risk maps, downloadable financial templates and company‑level appendices necessary to convert insight into board‑level decisions. For leaders preparing 2026 roadmaps — particularly those focused on R&D investment prioritization, distribution resilience and regulatory compliance — the full study provides the decision‑grade inputs you need to move from strategy to execution.
For detailed analysis of this topic, please visit the official page: Vegetable Seed Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com