

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Advanced Packaging surges to USD 80.4B by 2032 at 8.6% CAGR

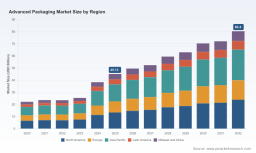
Advanced Packaging Market 2026: Strategic Implications for Executives — A PW Consulting Preview
Executive preview
Advanced packaging has moved from a niche enabler to a strategic battleground. Between 2020 and 2025 the global advanced packaging market more than doubled in scale, and our modeling — anchored on a 2025 base year and a 2026–2032 forecast horizon — indicates sustained expansion at an 8.6% CAGR. By 2032 the addressable market crosses the magnitude that turns advanced packaging from an operational consideration into a core determinant of semiconductor competitiveness.
Advanced Packaging Market
This briefing is written for C-suite leaders, corporate strategists, and investment committees preparing decisions in 2026. It presents the actionable intelligence and strategic framing our full Advanced Packaging Market study provides while intentionally withholding granular segment-level breakdowns. Think of this as the trailer: enough to inform immediate choices, and designed to lead you to the full report for the proprietary data, scenario models, and playbooks needed to execute.
Advanced Packaging Market
Why 2026 is an inflection year
-
Capital intensity accelerates. Major players are moving from pilot runs to volume deployments and large-scale packaging capacity buildouts. These actions compress lead times for capacity expansion and materially affect bargaining power between foundries, OSATs, and OEMs.
Advanced Packaging Market -
Technology heterogeneity broadens risk and opportunity. Heterogeneous integration (2.5D/3D, chiplets, fan-out and advanced wafer-level approaches) is now a functional requirement for AI, HPC and premium mobile applications — creating differentiation pathways but also technical complexity for supply chains and test flows.
-
Policy and trade dynamics are reshaping market access. Recent regulatory shifts and export controls are changing how companies plan capacity, route supply, and manage compliance risk. Tariff measures and licensing policies are functioning as de facto industrial policy instruments in several important end markets.
-
Materials and labor constraints are emerging as gatekeepers. Adoption of new substrates (notably the growing emphasis on glass) and persistent talent shortages in advanced packaging engineering and operations create non-trivial bottlenecks — even where capital is available.
What this means for corporate decision-making in 2026
-
Revisit capital-allocation frameworks. The right response is not simply “more capacity” but targeted capacity that aligns to technology nodes, assembly/test proficiency, and geopolitical risk profiles. Investment decisions taken in 2026 will determine competitive positioning for at least a decade in premium segments.
-
Adopt a modular technology posture. Companies that converge on chiplet-enabled architectures, standardized interposers, and interoperable packaging stacks will accelerate time-to-market and reduce vendor lock-in risk.
-
Prioritize supply-chain security and compliance. Licensing regimes and tariff policies are elevating the value of onshore or allied-country capacity and creating a premium for partners with validated compliance frameworks.
-
Make materials and talent strategies explicit. Strategic partnerships with substrate suppliers, focused workforce development, and automation investments are now core to execution risk management — not optional cost centers.
Competitive dynamics — the shape of rivalry and opportunity
The competitive landscape is a mix of integrated device manufacturers, leading-edge foundries expanding packaging services, and large OSATs scaling capabilities. Market concentration remains moderate: the top three players do not dominate the industry outright, but the top five have a growing combined heft. This creates a dual reality — sustained competition at the top coupled with whitespace for specialized providers.
-
Foundry leaders: Foundries that integrate advanced packaging (through proprietary stacks and dedicated packaging fabs) are creating high-margin value chains for heterogeneous integration. Their scale enables rapid qualification with hyperscalers and datacenter customers but requires continual capex to defend technological leadership.
-
OSAT consolidation and specialization: Large OSATs are investing aggressively in fan-out, panel-level processes, and high-density interposers. Expect increased vertical partnerships with substrate suppliers and test houses as OSATs broaden their value proposition beyond pure assembly and test.
-
Regional players and national policy: Domestic OSATs and foundries are being incentivized to capture upstream and downstream value. For multinational firms, this raises complex make-or-buy and partnership choices driven as much by policy as by cost.
Recent moves that crystallize 2026 strategies
-
Large foundries have announced major, multi-facility expansions that include dedicated advanced packaging campuses — an explicit signal that packaging is moving into factory-first long-range planning.
-
IDMs and foundries are transitioning advanced process nodes from qualification to volume manufacturing, reducing technical risk for leading-edge packaging solutions and making high-performance packaging more commercially accessible.
-
OSATs are materially increasing capital intensity — both in new plants and in multi-year capex programs — driven by demand from AI and premium automotive applications. These investments are reshaping capacity availability in the near term.
-
Regulators have broadened controls on equipment and certain chip categories, and tariff regimes have been introduced in key markets. These changes are influencing both sourcing decisions and the economic calculus of cross-border investments.
What our Advanced Packaging Market study delivers (practical content)
Our full report is built to be operational. It includes:
-
Market sizing and growth trajectories with transparent assumptions (historical 2020–2025, base year 2025, forecast 2026–2032, presented in USD Billion and incorporating an 8.6% CAGR for forward-looking scenarios).
-
Scenario-driven demand models by technology stacks, applications, and regions — delivered with interactive worksheets so you can test different product mixes, pricing trends, and policy outcomes. Note: granular regional and application splits are excluded from this executive preview to preserve the investigative value of the full study.
-
Supply-side mapping: capacity overlays, CAPEX timelines, utilization assumptions, and supply chokepoints across substrates, test, and automation equipment.
-
Competitive profiles and strategic positioning maps of the major players, including capability gaps, partnership vectors, and probable moves under different market regimes.
-
Regulatory and trade-impact assessments with mitigation playbooks — from re-routing supply chains to contractual protections and compliance architectures.
-
Actionable playbooks: supplier selection criteria, M&A and JV checklists, build-versus-buy decision matrices, and execution timelines aligned to 2026 board cycles.
Strategic checklist for 2026 leadership teams
-
Run a rapid scenario stress-test of your current roadmap against three policy scenarios (status quo, partial restrictions, and hardened controls). Prioritize options that preserve customer continuity under each case.
-
Fast-track a materials and substrate strategy focused on next-generation glass adoption and supplier diversity to mitigate single-source exposure.
-
Design a tiered capacity plan: short-cycle tactical partnerships to handle immediate volume, plus selective greenfield or brownfield investments for differentiated capabilities.
-
Invest in modular architectures and chiplet strategies to reduce product redesign cycles and accelerate multi-sourcing of intellectual property.
-
Build an executable talent plan: targeted upskilling, automation investments, and incentive structures that align packaging engineering with product development timelines.
-
Embed a cross-functional trade-compliance governance layer in all sourcing and investment approvals to reduce regulatory friction during execution.
Why PW Consulting’s study matters now
Decisions made in 2026 will disproportionately determine competitive outcomes in the decade that follows. The forces shaping advanced packaging are simultaneously technological, geopolitical, and operational — creating both asymmetric upside for first movers and material downside for late adjustments. Our study converts this complexity into executable options: quantified scenarios, prioritized investments, and pragmatic playbooks for production, procurement, and policy risk.
Next steps
This preview surfaces the strategic contours you need to debate in the boardroom. The full Advanced Packaging Market study contains the detailed segmentation, company-level market shares, unit-cost models, sensitivity analyses, and downloadable scenario tools you will need to convert strategy into execution. For access to the complete dataset and bespoke briefing sessions tailored to your corporate context, contact your PW Consulting engagement lead or request the report through our client services desk.
For detailed analysis of this topic, please visit the official page: Advanced Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com