

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Post-Tensioning Market to Reach USD 27.75 Billion by 2032 at 8.3% CAGR

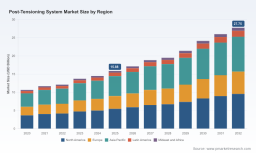
Post-Tensioning System Market — 2026 Strategic Preview (PW Consulting)
Executive snapshot
The post-tensioning systems market is at an inflection point. Our proprietary market model, anchored on a 2025 base year, shows the market expanding from an estimated USD 15.9 Billion in 2025 to a materially larger opportunity by the end of the 2026–2032 forecast window. The near‑term CAGR is projected at c. 8.3% over the forecast period, underpinned by steady historic growth since 2020 and accelerated demand across both new-build and retrofit infrastructure spend. Market concentration is moderate: the three largest suppliers account for a meaningful share of supply, while the top five further extend that influence — a structure that creates both barriers and openings for scale and specialist players.
Post-Tensioning System Market
Why this research matters for 2026 corporate decisions
-
Capital allocation under uncertainty — Boards and investment committees need granular scenarios to justify plant expansion, regional footprint changes, or new product lines. Our research converts headline growth into investible business cases by linking demand drivers to unit-volume, input-cost and margin sensitivities.
Post-Tensioning System Market -
Supply‑chain and procurement strategy — Tendon steel, anchorage systems, and certified fabrication capacity are the choke points. The report provides actionable sourcing pathways and tender evaluation templates to de‑risk multi-year supply agreements and index exposure to steel cycles.
Post-Tensioning System Market -
M&A and partnership screening — Given the market’s mix of vertically integrated global players and nimble regional specialists, stakeholders need a prioritised target universe and diligence checklists. We translate macromarket momentum into acquisition valuation scenarios and integration playbooks.
-
Regulatory and certification planning — PTI, national standards and building authority approvals materially affect time‑to‑market and contract eligibility. Our analysis maps certification requirements to timing, cost and operational implications for 2026 programmes.
-
Product and service portfolio decisions — Whether to invest in bonded vs. unbonded systems, internal vs. external bridge solutions or into specialist decarbonised materials requires demand and margin modelling. The study provides comparative profitability and risk metrics to guide R&D and commercial prioritisation.
What the report delivers — practical, transaction‑grade content
-
Proprietary market sizing and forecast model (2020–2032) with scenario variants. The model is available in a client workbook for sensitivity runs against steel prices, construction activity, and regulatory shifts.
-
Demand-driver decomposition linking infrastructure programmes, urban real‑estate dynamics, bridge maintenance cycles, and renewable energy (notably wind tower frameworks) to tender pipelines.
-
Supplier landscape and capability matrix covering fabrication, installation, certification and after‑sales maintenance. Includes a barrier-to-entry assessment and a strategic heat map for new entrants.
-
Commercial playbooks: specification-level procurement templates, contract terms that protect against material volatility, and unit-cost build-ups for capex budgeting.
-
Regulatory and standards digest: practical compliance checklists for PTI certification, major national standards and approvals that affect permanent use and tender eligibility.
-
Operational checklists for quality, site logistics, and workforce certification to reduce installation risk and lifecycle maintenance exposure.
-
M&A and JV evaluation frameworks: valuation templates, integration risk matrices, and post-acquisition priorities specific to post‑tensioning businesses.
Competitive landscape — who matters and why
The market is characterised by a mixture of global systems houses and highly capable regional specialists. PTI plant and field certifications, in‑house manufacturing of strands and ancillaries, and bundled design–installation–maintenance service models are differentiators that determine contract access and margin capture. Key players covered in the report include recognised global and regional names with distinct strategic postures:
-
General Technologies, Inc. (United States) — Single‑source provider reputation with a focus on components and equipment for concrete post‑tensioning; positions itself on completeness of supply and PTI‑certified production.
-
Structural Technologies (United States) — Exclusive distributor/manufacturer of a leading international system in the US, combining product supply with structural repair solutions; recently expanded capabilities through a strengthening‑solutions launch that broadens retrofit and repair addressable market.
-
Freyssinet (France) — Specialist full‑service player with in‑house strand manufacturing and integrated design/stress/installation capabilities; strong presence in civil projects and high‑complexity workstreams.
-
DYWIDAG (Germany) — Technology development focus across multiple tendon formats and approvals from global standards bodies; recent operational certification upgrades support geographic expansion and supply reliability.
-
Suncoast Post‑Tension, Advanced Post Tension, Builders Post‑Tension, AMSYSCO (United States) — Regional specialists focused on slab‑on‑ground, residential and commercial slabs, and barrier cable systems; they compete on service speed, local fabrication and PTI‑aligned quality.
Strategic implication: scale players capture system-level contracts and framework agreements, but regional specialists retain advantages in rapid execution and niche segments. This creates acquisition opportunities for scale players seeking local access, and for agile specialists to partner with OEMs for product innovation and distribution reach.
Market dynamics and regulatory context
Three structural forces are shaping the 2026 agenda:
-
Standards and certification intensity — Ongoing PTI certification programmes for both plant and field personnel continue to be gatekeepers for quality and contract eligibility; major systems maintain listings or approvals under ASTM, AASHTO, Eurocodes and equivalent national standards. Organisations that under-invest in certification face delayed tender access and elevated warranty risk.
-
Sectoral demand heterogeneity — Growth is not uniform across building types and infrastructure. Renewable energy structures (notably wind towers), bridge retrofits, and urban high‑rise construction are accelerating demand for specialised tendon formats and installation expertise.
-
Supply and capability bottlenecks — Fabrication capacity, certified field crews and logistics for long tendons are recurring constraints. Leading suppliers are responding with product and service extensions, certification of additional plants, and participation in trade and technical forums to secure pipeline access.
Recommendations for corporate leaders in 2026
Translate the market opportunity into executable priorities with a three‑horizon roadmap:
-
Near term (0–12 months) — Secure multi‑year supply frameworks for critical inputs; accelerate PTI and other plant/field certifications; run portfolio stress‑tests against price shocks and labour constraints; and bid selectively for framework contracts where certification and scale create defensible margins.
-
Mid term (12–36 months) — Invest in modular prefabrication and digital monitoring (e.g., tendon health sensors and digital twins) to differentiate on lifecycle performance; pursue bolt‑on acquisitions to plug geographic or capability gaps; and deploy indexed pricing in long‑term contracts to protect margins.
-
Long term (36+ months) — Target vertical integration where return on invested capital exceeds hurdle rates (fabrication + logistics + field services), pursue strategic partnerships in renewable energy infrastructure, and develop low‑embodied‑carbon tendon solutions as a market entry point to sustainability‑minded clients.
How PW Consulting positions to support your 2026 agenda
We combine a detailed, scenario‑ready market model with transaction experience in the built‑environment and infrastructure supply chains. Our deliverables for clients include: a downloadable model to run bespoke sensitivity analysis; a due‑diligence pack with operational checklists, certification roadmaps and integration playbooks; and a director‑level briefing tailored to capital allocation committees.
This preview surfaces the strategic steerings you need to act in 2026. To access the full dataset—region and application splits, subsegment revenue curves, supplier financials, and our interactive scenario workbook—please refer to the full Post‑Tensioning System Market report on our website. The report contains the primary research and granular tables required to convert market direction into investment decisions and commercial execution plans.
For detailed analysis of this topic, please visit the official page: Post-Tensioning System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com