

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
API Market to Reach USD 379.6B by 2032, Growing at 5.8% CAGR — PW Consulting Insight

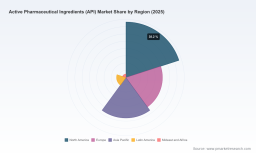
Active Pharmaceutical Ingredients (API) Market 2026: Strategic Imperatives for Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a synthesis of our 2026 Active Pharmaceutical Ingredients (API) Market study — a practitioner’s briefing designed to inform executive decision-making across manufacturing, procurement, R&D and public policy. This shortform introduction outlines why the report matters for leaders making capital, sourcing and transactional choices in 2026, and what practical intelligence you will need to convert market trends into defensible actions.
Active Pharmaceutical Ingredients (API) Market
Why this study matters in 2026
The API market has entered a new phase of calibrated growth and strategic rebalancing. After robust expansion in the first half of the decade, the global API sector measured in our base year (2025) stands at a materially larger scale than in 2020. Our forecast through 2032 captures continuing expansion at a compound annual growth rate (CAGR) of 5.8%, with market momentum driven by an intersection of therapeutic demand, regulatory reforms and re-shoring initiatives. By 2032 the market is projected to be substantially larger than it was in 2025, reflecting both sustained underlying demand and cyclical capacity investments coming online.
Active Pharmaceutical Ingredients (API) Market
For corporate leaders, that macro trajectory translates into three immediate strategic implications for 2026: (1) the need to recalibrate capacity and partner strategies to balance growth with resilience, (2) the imperative to navigate a shifting regulatory and policy environment that rewards domestic capabilities in selected markets, and (3) the opportunity to extract value through targeted M&A, greenfield investment, or advanced CDMO partnerships where differentiation (e.g., high‑potency APIs, complex small molecules, bioconjugates) matters.
Active Pharmaceutical Ingredients (API) Market
Key dynamics shaping 2026 decisions
-
Policy and security: Government interventions introduced in 2025–2026 have raised the strategic priority of supply‑chain resilience. Notably, national initiatives to create strategic API reserves and public‑private programs advocating domestic capacity expansion change the risk calculus for multinational procurement and for firms evaluating localized manufacturing investments.
-
Regulatory acceleration: Pilot programs aimed at streamlining reviews for domestically produced generics and APIs are reducing time‑to‑market for qualifying facilities. These pilots impact the relative value of investing in compliant local capacity versus continuing to rely on overseas suppliers for critical lines.
-
Technical specialization: Demand is bifurcating. Large-volume, commodity APIs remain core to many generics portfolios, while higher-margin segments — high‑potency APIs (HPAPIs), complex small molecules and emerging biotech-derived ingredients — are driving differentiated returns for specialized manufacturers and CDMOs.
-
Consolidation and competition: The market remains moderately concentrated, with the largest incumbents holding meaningful but far-from-total share. This creates room for focused players — whether regional champions, specialty CDMOs or new entrants backed by strategic investors — to capture adjacent opportunities by offering speed, compliance and technical capability.
What the report delivers — practical outputs for executives
This research is structured to move beyond descriptive analysis to actionable decision support. The full report contains:
-
Top‑down market sizing from 2020 through our 2025 base year and forward‑looking projections to 2032 with scenario‑based sensitivities (policy shock, demand shock, supply disruption).
-
Driver maps linking therapeutic demand trends, regulatory shifts and capital flows to segment‑level investment cases and margin profiles.
-
Operational playbooks: make‑vs‑buy decision frameworks, capacity hedging strategies, supplier scorecards and an API procurement playbook tuned for 2026 market conditions.
-
Transaction support tools: valuation heuristics for asset purchases and CDMO partnerships, integration risk checklists, and a prioritization matrix for brownfield vs greenfield investment in target regions.
-
Regulatory pathway mapping for firms seeking to leverage accelerated review pilots — outlining compliance checkpoints, recommended audit timelines and resource planning to shorten approval timelines for qualifying facilities.
-
Risk registers and contingency templates that embed supply‑chain stress testing against realistic disruption scenarios — operationally reversible playbooks you can run at the board level.
To preserve competitive value for subscribers, the report highlights the analytical approach and delivers executive tools while withholding granular segmented revenue breakdowns and vendor‑level unit economics in this public overview. Those detailed exhibits are available in the full study.
Competitive landscape — who to watch and why
The 2026 competitive map features a mix of long‑standing integrators, specialized CDMOs and regionally strong manufacturers. Several corporate moves and facility ramps in late 2025 and early 2026 exemplify how strategy is translating to market positioning:
-
Wanbury Limited (Hyderabad): The commissioning of a new commercial facility and first European shipments of anesthetic APIs in early 2026 evidence a deliberate push into higher‑value, regulated export markets. This is a textbook example of a regional manufacturer leveraging new capacity and regulatory approvals to move up the value chain.
-
Lonza Group (Basel): Ongoing expansions and site ramp‑ups targeting high‑potency and bioconjugate capabilities position established CDMOs to capture demand from innovators and specialty generics alike — particularly where technical complexity and regulatory compliance are gating factors.
-
Large integrated CDMOs and pharmaceutical manufacturers (e.g., Pfizer CentreOne, Thermo Fisher/Patheon, Cambrex): These players continue to compete on global scale, quality systems and the breadth of end‑to‑end services. For clients prioritizing reliability and complex project management, these suppliers remain default choices.
-
Specialists and regional champions (e.g., Grünenthal PRO, Ampac Fine Chemicals, several Indian API producers): Their technical niches — pain therapeutics, energetic chemistries or low‑cost large‑scale production — mean they can deliver differentiated margins or cost leadership in targeted therapeutic pockets.
-
Nonprofit and public‑private actors (API Innovation Center and similar initiatives): These entities are reshaping the policy and funding environment for domestic API capacity, acting as accelerators for domestic investment and as intermediaries between government procurement programs and industry.
For buyers and investors, the immediate implication is clear: supplier selection must now weigh not just price and quality but also strategic alignment with national policy programs, accelerated regulatory pathways and resilience metrics. For suppliers, the path to premium positioning runs through demonstrable compliance, technical specialization and the ability to deliver to public procurement frameworks.
Near‑term signals to watch in 2026
-
Facility approvals and first commercial shipments from newly commissioned sites — these are leading indicators of near‑term capacity additions and where competitive pressure will emerge.
-
Regulatory pilot outcomes — programs designed to expedite domestically produced APIs will shift the economics of where to produce certain molecules; track qualification criteria and timeline gains.
-
Public procurement directives and strategic reserve purchases — government buying for strategic stockpiles will create pockets of demand and may distort pricing for affected molecules.
-
M&A and partnership activity among mid‑tier CDMOs — consolidation here presages an acceleration in specialized capacity aggregation and can be a prelude to larger strategic plays.
How to use this study in 2026
Executives should treat this report as a tactical and strategic toolkit. Use the market sizing and scenario outputs to stress‑test capital allocations and procurement strategies. Use the supplier scorecards and regulatory mapping to update vendor panels and audit priorities. Use the transaction heuristics and integration risk checklists to underwrite deals or partnerships with practical, board‑grade analyses.
If you are planning capital deployment, consider starting with a narrow set of test assets or partnership pilots that de‑risk execution while positioning for scale if policy or demand scenarios play out favorably. If you are a buyer, revise contracting standards to include resilience clauses and qualifying criteria tied to accelerated regulatory pilots.
Closing — the strategic imperative
2026 is a pivot year for the API market: structural growth continues, but policy and operational changes have recalibrated how value is created and preserved. Profit pools are shifting toward technical complexity and compliance-enabled supply. Those who read the market correctly — and move early to align capacity, regulatory readiness and partner ecosystems — will capture disproportionate value over the next investment cycle.
For a full breakdown of our model, detailed segment tables, supplier revenue breakdowns and the step‑by‑step operational playbooks referenced above, please access the full PW Consulting Active Pharmaceutical Ingredients Market report. The comprehensive exhibits and vendor scorecards are available only in the complete study.
For detailed analysis of this topic, please visit the official page: Active Pharmaceutical Ingredients (API) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com