

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vinyl Tile Market to hit USD 326.77M by 2032 at 6.1% CAGR

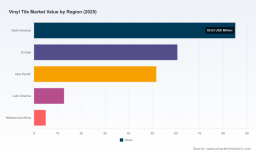
Vinyl Tile Market — 2026 Strategic Brief
As companies set budgets, capital plans, and product roadmaps for 2026, the vinyl tile market presents both clear opportunity and complexity. Our new market study — grounded in five years of historical data (2020–2025) and a forward-looking forecast through 2032 — shows a resilient market expanding at a steady compound annual growth rate of 6.1%. The industry is projected to grow meaningfully from its 2025 base, underscoring near-term investment cases for suppliers, distributors, and institutional buyers alike. This brief synthesizes the study’s strategic value for executive decision-making while deliberately withholding granular segment tables to encourage direct access to the full report for transaction‑level intelligence.
Vinyl Tile Market
Why this study matters for 2026 decision cycles
- Macro clarity to underwrite capital decisions: With an explicit base year and multi‑year forecast horizon, the study reconciles demand trajectories against capacity movements, enabling finance teams to stress‑test new plant investments, debottlenecking projects, or third‑party capacity agreements.
- Risk framing for procurement and pricing: The report quantifies how feedstock, tariff, and standardization dynamics translate into landed cost variability — an essential input for sourcing and pricing models in 2026.
- Go‑to‑market playbooks for 2026 launches: For product and commercial teams, our research pairs market sizing with channel intelligence and buyer preferences to prioritize SKU rationalization, premiumization, or value plays in target verticals.
- M&A and partnership scouting: The study’s competitive overlays and plant‑level capacity maps identify acquisition targets and buy‑vs‑build scenarios optimized for near‑term scale or niche technology access.
Headline market context
Using 2025 as the base year, the study models a market that is both mature and expanding — a profile that favors strategic consolidation, selective capacity investments, and differentiated product strategies. The forecast period to 2032 provides scenario windows for stress testing assumptions around raw material supply, tariff regimes, and adoption curves for premium resilient formats.
Vinyl Tile Market
Report contents — practical modules included
- Executive summary with scenario-based forecasts and sensitivities (base, upside, downside).
- Proprietary demand model calibrated to shipment flows, installer demand signals, and construction activity indices.
- Plant‑level capacity and utilization maps with lead times and regional logistics overlays.
- Supply‑chain heat map, including PVC resin price exposure, alternative polymer readiness, and supplier concentration risk.
- Regulatory and standards impact assessment — VOC testing, FloorScore implications, ISO testing specifics, and tariff exposures.
- Commercial playbooks: channel segmentation, margin waterfall analyses, and customer value maps for residential vs. commercial transformations.
- Competitive landscape profiles and M&A opportunity matrix (strategic fit, valuation multiple ranges, integration risk checklists).
- Implementation checklist and 100‑day tactical plan templates for rapid market entry or defense strategies.
Key market dynamics and strategic implications
- Demand drivers and product evolution: Demand continues to be driven by renovation cycles, moisture‑resistant product innovations, and the migration of commercial segments to resilient formats that offer faster installation and lower lifecycle disruption. In 2026, suppliers who can credibly demonstrate performance in wet or high‑traffic environments will capture disproportionate consideration from builders and specification teams.
- Raw material volatility and procurement levers: Feedstock trends remain a central earnings lever. For example, observed decreases in PVC resin spot prices through early 2026 have eased some margin pressure versus 2025 highs, but substitution risk and vendor concentration mean procurement teams should maintain multi‑sourcing protocols and strategic hedges.
- Regulatory and standards pressures: Indoor air quality certifications such as FloorScore (aligned to specific VOC test standards) are increasingly embedded in procurement specs for institutional projects. Concurrently, origin‑based tariff exposures — including additional duties on certain imports — are forcing manufacturers and importers to reroute supply or seek preferential origin arrangements.
- Supply-side reinvestment and consolidation: The market is in the midst of capacity shifts driven by targeted capital projects and acquisitions by large incumbents. Recent capacity expansions and acquisition playbooks are compressing lead times in select geographies, sharpening competition on rapid replenishment and bespoke finishes.
- Moderate market concentration: From a competitive economics perspective, the market exhibits a moderate level of concentration at the top — enough to influence pricing dynamics and standard‑setting, but also leaving space for regional specialists and innovative entrants to scale via niche propositions or service‑led models.
Competitive landscape — insights and implications
Our analysis profiles the major players and decodes strategic intent based on product portfolios, manufacturing footprints, and recent moves. Below are high‑level strategic takeaways for the key firms examined in the report.
Vinyl Tile Market
- Armstrong Flooring — With a domestic manufacturing focus and proprietary wear‑surface technologies, Armstrong is positioned for specification wins where scratch and stain performance are prioritized. Strategy implication: prioritize channel partnerships with commercial installers and leverage domestic lead‑times as a premium service offering.
- Mohawk Industries — Offering a wide LVT/LVP portfolio across residential and commercial segments, Mohawk’s scale supports aggressive retail and distributor programs. Strategy implication: smaller competitors should defend via differentiated designs, local service or sustainability credentials.
- Shaw Industries — Recent capital expenditure programs have materially expanded SPC and LVT capacity and upgraded embossing capabilities. Strategy implication: expect intensified competition on photorealistic visuals and short lead, high‑mix orders; nonintegrated players should consider contract manufacturing or co‑packing deals.
- Interface — With a commercial focus and modular product set, Interface competes on sustainability and long‑cycle projects. Strategy implication: product teams should translate sustainability achievements into measurable total cost of ownership (TCO) benefits for institutional buyers.
- TOLI Corporation — Specialization in resourced and slip‑resistant products positions TOLI well for niche safety and outdoor‑adjacent applications. Strategy implication: pursue specification in sectors where safety standards or outdoor adjacency are key procurement filters.
- Reward Flooring, Magna‑Lock, Paramount Vinyl Tile, RC Vinyl — These manufacturers occupy distinct niches from value plays to technology‑specialized systems (e.g., magnetic bonding systems for access floors or eco‑formulations). Strategy implication: incumbents should monitor these specialists for partnership or bolt‑on acquisition opportunities to fill portfolio gaps.
Recent developments shaping near‑term strategy
- Major capacity projects and acquisitions have reshuffled available domestic SPC/LVT supply and will affect lead times and price elasticity in 2026.
- New product introductions focused on wet‑space performance reflect an adjudication of feature demands that will matter in bathroom, kitchen, and multi‑family specifications.
- Tactical procurement actions will be required to manage tariff differentials and import duty regimes that have raised landed cost variability for certain origin sources.
Actionable strategic playbook for 2026
- Hedge and diversify feedstock exposure: Secure multi‑source supply contracts and pursue forward procurement for PVC and other critical inputs. Evaluate co‑investment in upstream capacity where scale warrants.
- Prioritize specification economics: Translate performance metrics (durability, VOC certification, moisture resistance) into TCO narratives for architects and facility managers to win specification share.
- Lean on speed to market: Use domestic or near‑source capacity as a differentiator for quick replenishment SKUs, especially in high‑mix decorative lines.
- Pursue selective M&A: Target acquisitions that provide either capacity flexibility, access to sustainable formulations, or technical differentiation such as magnetic or slip‑resistant systems.
- Embed compliance and sustainability into product roadmaps: Make certifications and test compliance a baseline requirement for new SKUs to avoid specification exclusion in the institutional channel.
- Commercial segmentation and channel incentives: Align pricing and promotional investments to high‑value channels (specifiers, national distributors, large remodel chains) and develop installer loyalty programs to reduce churn.
How to use the full PW Consulting study
The full report contains the segment‑level analytics, plant maps, SKU‑level price elasticity models, and a granular M&A heatmap that executives use to operationalize the brief strategies above. Because the most actionable intelligence hinges on those segment splits and location‑specific figures, we intentionally limit those tables here to preserve the value of the proprietary dataset.
For executive teams preparing 2026 plans, the combination of our base/future market sizing, supplier scorecards, regulatory impact assessments, and tactical 100‑day playbooks creates a fast path from insight to implementation. Accessing the full report will provide the transaction‑grade detail — segment revenues, regional dynamics, and competitor share tables — necessary for investment approvals and bilateral negotiations.
PW Consulting’s vinyl tile market study is built for leaders who need both the strategic panorama and the operational blueprint. If you are assessing capacity investments, supply‑chain hedges, or acquisition targets for 2026, this research will frame your decisions with quantitative rigor and executable options.
For detailed analysis of this topic, please visit the official page: Vinyl Tile Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com