

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
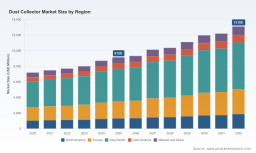
PW Consulting: Dust Collector Market Poised for 5.37% CAGR; Asia‑Pacific Tops at ~USD 4,185M

Dust Collector Market 2026: Strategic Preview for Executive Decision‑Making
As regulatory pressure tightens, industrial activity normalizes post‑pandemic, and operators accelerate equipment refresh cycles, the dust collector market is entering a phase of steady, technologically driven expansion. PW Consulting’s latest market research — with a 2025 base year, historical analysis covering 2020–2025, and forecasts through 2032 — frames that transition quantitatively and pragmatically. The headline: the global market reached approximately USD 9.15 billion in 2025 and is projected to grow at a compound annual growth rate (CAGR) of roughly 5.37% over the forecast window, reaching the low‑to‑mid‑teens (in USD billions) by 2032. For leaders planning capital allocations, product roadmaps, M&A screening, or channel investments in 2026, the study provides a focused, actionable evidence base — while reserving the proprietary segment matrices to subscribers.
Dust Collector Market
Why this study matters for 2026 decisions
- Compliance is no longer optional: Recent regulatory updates — from EPA NESHAP particulate standards to NFPA 660’s consolidated combustible dust rules and OSHA’s tightened PELs for hazardous particulates — are forcing plant operators and integrators to accelerate upgrades or face plant downtime and liability exposure. The research models the regulatory compliance-driven portion of demand and quantifies typical replacement and retrofit cycles across industries.
- Hardware plus services = durable revenue: The market’s growth path shows accelerating aftermarket and service opportunities (installation, filter media, predictive maintenance) that materially augment capital equipment margins. Our financial scenarios demonstrate how service attach rates and consumption economics can lift enterprise-level gross margins for suppliers that successfully migrate from a one‑time sale model to recurring revenue streams.
- Technology polarization: Incremental improvements in filter media, pulse-cleaning algorithms, and small‑form portable units are reshaping product tiers. The study identifies where premiumization is occurring (e.g., high-efficiency fine‑dust capture, explosion‑mitigation features, and integrated IoT monitoring) and where low‑cost commoditized units will continue to compete on price.
- Supply chain and labor constraints: Our field research captures how skilled labor shortages for installation and servicing (typical project delays of 4–8 weeks) and critical component supply risks affect lead times, pricing dynamics, and customer selection criteria — a pattern many procurement teams are already witnessing in 2025–2026.
Market structure and competitive dynamics
The dust collector market sits in a moderately consolidated landscape: the top three players account for roughly 42.5% of market share while the top five approach just over half of the market. That concentration translates into a competitive environment where established OEMs command pricing power in premium segments and niche players compete on customization, lead time, and application‑specific credentials (e.g., combustible dust, food‑grade construction, or heavy abrasive particulate). PW Consulting’s competitive suite evaluates both the scale advantages of global suppliers and the agility of regional specialists.
Dust Collector Market
- Donaldson Company, Inc. (Minneapolis, MN) — A global manufacturer noted for Torit® baghouse and cartridge lines, including modular PowerCore™ and DownFlo™ platforms that target industrial filtration across manufacturing and process industries. Their strength lies in broad product breadth and established service networks.
- Nederman (Sweden) — Known for workshop and metalworking filtration solutions (S‑Series shaker, LBR SmartFilter). Nederman competes effectively in applications requiring localized extraction and combustible dust handling with demonstrable compliance credentials.
- Camfil (Sweden) — Positioned in fine dust and fume control with modular Gold Series collectors and a focus on premium filter media and energy‑efficient designs; Camfil’s advantage is high‑efficiency filtration for stringent indoor air quality requirements.
- A.C.T. Dust Collectors (New Ulm, MN) — A U.S. manufacturer with a strong presence in cartridge and LaserPack offerings; competitive in metalworking and thermal spray sectors where application‑tailored solutions are critical.
- Airex Industries, C&W DustTech, WAMGROUP WAM® AIR, Oneida Air Systems — Each of these players competes in specific verticals: high‑volume baghouse applications, concrete and aggregate industries, modular global systems, and portable/light industrial niches respectively. Their strategies range from OEM partnerships to localized installation services.
Recent product and trade‑show activities (e.g., new compact units for food processing and portable accessory launches) underscore two parallel currents: incumbents refreshing product lines for regulatory and energy‑efficiency gains, and smaller innovators pursuing adjacent niches with low‑capex, rapid‑deployment solutions. The full report dissects strategic moves, product roadmaps, and comparative performance across the leading vendors, providing a clear scorecard for sourcing and partnership decisions.
Dust Collector Market
Key demand drivers and risks to monitor in 2026
- Regulatory tailwinds: Mandatory compliance timelines create predictable retrofit waves in industries such as metal processing, foundries, and cement. Decision calendars for 2026–2028 should prioritize units that meet forthcoming NFPA 660 and EPA opacity requirements.
- Retrofit and retrofit economics: Many existing installations are functionally sound but non‑compliant or inefficient; retrofits often deliver fast paybacks. Our scenarios quantify typical payback bands and suggest which upgrades (filter media, pulse-control systems, explosion venting) produce the most attractive ROI.
- Aftermarket and digital services: Digital monitoring and predictive maintenance reduce unplanned downtime and optimize filter replacement cycles. Vendors that can offer connected hardware and service SLAs capture higher lifetime value — a core takeaway for 2026 commercial strategies.
- Labor shortages and project execution risk: Skilled installation and service capacity constraints are lengthening lead times and increasing implementation costs. Contracting strategies, modularized designs, and training partnerships are practical mitigants.
- Commodity and input price volatility: Filter media, polymer components, and fan motors are subject to raw material swings; procurement teams should secure long‑lead items and consider hedged supplier agreements in capital planning for 2026 projects.
What the report contains (practical, operational intelligence)
- Market sizing and growth trajectories: base year 2025, historical 2020–2025 trends, and forecast scenarios through 2032, with sensitivity testing around regulatory acceleration and macroeconomic shocks.
- Segment‑level modeling by geography, product type, and application — fully detailed with forecasted volumes, ASP trends, and replacement cycles (note: segment tables and granular figures are available in the full report).
- Competitive benchmarking: product matrices, pricing bands, channel structures, and a capability heatmap for leading vendors to support sourcing and partnership decisions.
- Commercial playbook: go‑to‑market recommendations for OEMs, distributors, and service providers, including product bundling, subscription pricing models, and installation partnerships to close the labor gap.
- Regulatory and safety compliance compendium: mapped timelines, likely enforcement hotspots, and practical engineering responses to NFPA 660, EPA NESHAP, and other regionally relevant standards.
- Case studies and implementation templates: retrofit budgeting worksheets, service contract templates, and a prioritized project roadmap to accelerate decision cycles in 2026.
- Methodology and sources: primary interviews with plant managers, integrators, and OEMs; financial statement analysis; and a bottom‑up market sizing approach calibrated against trade flows and filter media consumption.
Recommended 2026 playbook for executives
- Prioritize compliance retrofits with high ROI: Map existing assets against regulatory deadlines, and sequence retrofits by payback and enforcement risk. Allocate capital to those projects that both mitigate regulatory exposure and unlock energy savings.
- Invest in aftermarket and digital services: Build or acquire capabilities in remote monitoring, spare‑parts logistics, and predictive services to create recurring revenue and defend margin erosion from commoditization.
- Target bolt‑on M&A for capability gaps: With the market moderately concentrated, tactical acquisitions of niche specialists (portable units, combustible‑dust-certified designs, or regional service networks) can accelerate channel reach and technical depth more cost‑effectively than organic development.
- De‑risk execution: Lock supply agreements for critical components, modularize designs to reduce on‑site labor, and develop certified training programs with channel partners to shorten installation lead times.
- Differentiate on energy and safety economics: Customers increasingly value total cost of ownership. Offer measured TCO analysis and financing options to convert capital‑constrained prospects into immediate orders.
Final note — what you’ll gain from the full study
PW Consulting’s Dust Collector Market study is designed as a decision‑grade asset for 2026 planning. It combines robust quantitative forecasting (rooted in the 2025 base year and reflecting a 5.37% CAGR through the forecast horizon) with actionable commercial guidance, vendor scorecards, and regulatory playbooks. This preview surfaces the high‑level patterns you need to know now; the full report delivers the granular segment matrices, region‑application breakouts, and executable templates required to convert insight into investment. For procurement, strategy, and product teams that must execute in 2026, the complete dataset and appendices provide the exact figures and scenario outputs necessary to finalize budgets, shortlist partners, and prioritize programs.
If your 2026 planning cycle includes compliance upgrades, aftermarket expansion, or M&A screening in the dust collector ecosystem, PW Consulting’s full report equips you to act with calibrated risk and competitive foresight.
For detailed analysis of this topic, please visit the official page: Dust Collector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com