

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: DMSO Market to Hit USD 385.3M by 2032 at 5.8% CAGR

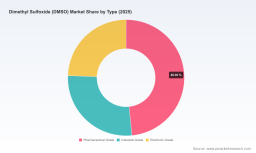
Dimethyl Sulfoxide (DMSO) Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
By 2025 the global Dimethyl Sulfoxide (DMSO) market reached approximately USD 263.0 Million (base year 2025), up from roughly USD 211.0 Million in 2020. Our analysis projects the market to grow at a compound annual growth rate (CAGR) of about 5.8% through the 2026–2032 forecast window, with the market approaching an estimated USD 385.3 Million by 2032. These headline dynamics reflect demand resilience across high-purity pharmaceutical and electronics applications, alongside steady industrial consumption and targeted growth pockets such as advanced battery electrolyte processing.
Dimethyl Sulfoxide (DMSO) Market
Why this briefing matters for 2026 corporate strategy
- Timing: 2026 is a pivotal year in which upstream cost pressures (feedstock and logistics) and downstream electrification and semiconductor cycles will materially influence profitability and capacity planning. Companies that align investment and procurement strategies to the projected 5.8% growth path will capture disproportionate value.
- Focus: DMSO is a niche specialty solvent where product-grade differentiation (pharmaceutical vs. electronic vs. industrial) and supply-chain security trump scale alone. Strategic choices made in 2026 — on purification capacity, contract terms with feedstock suppliers, and targeted customer segments — will set the winners for the remainder of the decade.
- Risk-reward balance: The market displays high concentration among a few incumbents (market CR3 ~79%; CR5 ~82%), so late movers face barriers. But the concentration also creates opportunities for differentiated entrants that offer ultra-high-purity or sustainability-backed value propositions.
High-level market dynamics (what’s driving change)
- Feedstock economics and sourcing: The principal industrial route to DMSO runs through dimethyl sulfide (DMS), itself commonly derived as a by-product of kraft pulp processing or by methanol-based syntheses. Sulfur-based feedstocks continue to underpin a majority share of global production because of cost efficiency, but that linkage creates exposure: volatility in sulfur supplies or disruptions in petroleum refining and trade flows can quickly transmit to upstream unit costs and availability.
- Logistics and handling: DMSO’s physical and regulatory handling requirements (classified with flammability and toxicology precautions in many jurisdictions) elevate logistics complexity. Specialised packaging, temperature- and hazard-compliant transport lanes, and additional insurance or surcharges increase landed costs — a structural factor that favors integrated or regionally proximate suppliers.
- Regulation and end‑use constraints: In several markets DMSO is restricted largely to research or controlled industrial uses because of regulatory concerns over skin penetration and human exposure. These regulatory classifications shape go‑to‑market strategies for suppliers and the procurement behavior of end-users — particularly in pharmaceuticals and regulated manufacturing.
- Application-side demand inflection: High‑purity uses — notably in pharmaceutical production, advanced electronics, semiconductor processing, and emerging battery electrolyte processing — are increasingly the primary growth drivers. Industrial-grade and commodity solvent demand remains important for volume, but higher-margin opportunities are concentrated in ultra‑high‑purity streams.
Competitive landscape — who matters and why
The DMSO market is dominated by a small group of specialised producers and chemical majors. These players differ by strategic focus (dedicated high-purity producer vs. industrial-scale commodity supplier), geographic footprint, and capabilities in purification and certification.
Dimethyl Sulfoxide (DMSO) Market
- gChem (Tuscaloosa, Alabama, United States) — A focused leader in pharmaceutical-grade and high-purity DMSO. The company’s recent rebrand and publicised strategic collaboration with a major automaker to supply ultra-high-purity DMSO for lithium-ion battery electrolyte processing highlight two themes: vertical end‑market expansion (batteries) and an explicit move toward sustainability and innovation-led differentiation.
- Hubei Xingfa Chemicals Group (Xingshan County, Hubei, China) — A major Chinese producer and exporter, competitive on cost through proximity to local sulfur feedstocks. Their position underscores the structural arbitrage between low-cost integrated producers and high‑specification Western suppliers; buyers must weigh total cost of ownership, quality certification, and logistics risk.
- Arkema S.A. (Colombes, France) — A global chemicals player that supplies high-purity grades for semiconductor and pharmaceutical industries. Its broad supply chain network and regulatory reach make it a preferred partner for multinational OEMs seeking multi‑region continuity.
- Toray Fine Chemicals (Tokyo, Japan) — A key supplier for high‑purity grades used in electronics and specialized chemical processes. Recent capacity expansions for ultra‑high‑purity DMSO highlight the close coupling between semiconductor demand cycles and capacity investment timing.
- Spectrum Chemical Manufacturing (Gardena, California, United States) — A supplier that targets research and laboratory channels with certified grades and diverse packaging. Spectrum’s model emphasizes traceability and certification — features which command premiums in regulated end uses.
Recent developments that change the strategic calculus
- gChem: Rebranding and strategic collaborations in early 2026 signal a deliberate pivot to high-value, proprietary applications (e.g., battery electrolyte processing) beyond traditional pharmaceutical markets. This signals potential margin expansion and new demand vectors for ultra‑high‑purity DMSO.
- Toray: Commissioning purification capacity for ultra‑high‑purity grades during 2024–2025 suggests supply-side tightening for the highest-quality streams, validating supplier investments in technology to serve semiconductor and electronics OEMs.
- Input volatility and logistic surcharges: Ongoing pressure from sulfur feedstock price swings and transport compliance costs is expected to sustain unit‑cost volatility in 2026. Firms with hedging capabilities, backward integration, or long-term supplier agreements will have a strategic edge.
What PW Consulting’s full report delivers (operationally useful content)
Our full DMSO market study (base year 2025; historical 2020–2025; forecast 2026–2032) is structured to convert market intelligence into executable choices. Highlights include:
Dimethyl Sulfoxide (DMSO) Market
- Validated market sizing and growth scenario mapping aligned to macro and end‑market drivers, including sensitivity analyses that show upside/downside outcomes under alternative feedstock and demand shocks.
- Granular supplier benchmarking that evaluates capacity, grade portfolios, regulatory certifications, geographic risk, and total cost of ownership — presented as decision-ready matrices for procurement and corporate development teams.
- Investment playbooks for producers and investors: capacity expansion checklists, purification technology options, capex phasing simulations, and go/no-go triggers keyed to semiconductor cycles and battery adoption milestones.
- Commercial strategies for buyers: procurement contracting templates, multi‑sourcing models, and risk transfer mechanisms (e.g., tolling, buffer inventory, or JVs) to mitigate upstream volatility.
- Regulatory and logistics intelligence: a practical guide to compliance, classification, and handling implications across major jurisdictions, plus implementation steps to reduce transportation premiums and delay risk.
- Case studies and M&A heat maps that identify realistic acquisition targets and partnership archetypes, reflecting the market’s concentrated structure and the premium for integrated feedstock positions or ultra‑purity capabilities.
Strategic implications and recommended decision levers for 2026
- Protect margin via feedstock strategies: Prioritise backward integration, long‑term sulfur or DMS contracts, or financial hedging mechanisms. Given the market’s sensitivity to sulfur supply and refining trade flows, buyers and suppliers should lock price and supply terms where practical.
- Tiered product strategy: Maintain industrial-grade capacity for volume stability while selectively investing in ultra‑high‑purity and pharmaceutical-grade purification where margins and growth prospects justify capital deployment.
- Logistics and regulatory optimization: Invest in compliant packaging and preferred carrier programs to reduce surcharges and access restricted corridors. For exporters, focus on triaging markets where regulatory classification permits commercial deployment beyond research use.
- Partnerships to enter new end markets: Look for strategic collaborations that marry supplier purification capabilities with OEM process know‑how (battery, semiconductor, pharma) — the Hyundai-gChem example is illustrative of the value in targeted alliances.
- Market entry & M&A posture: Given the industry’s CR3/CR5 concentration, small and mid-sized players should evaluate bolt-on acquisitions that add purification capabilities or regional logistics hubs to improve competitiveness against established leaders.
How to use this briefing and where it leads
This note is designed as a focused, strategy-oriented preview. It surfaces the macro growth trajectory (CAGR ~5.8% through 2032) and the critical operating factors that will determine winners in 2026 and beyond, while preserving the granular segment and company‑level datasets that underpin executable decisions. PW Consulting’s detailed datasets (regional and application splits, supplier share tables, and scenario‑level P&L impacts) are provided in the full report and accompanying models — the inputs that procurement, corporate development, and strategy teams need to finalize 2026 plans.
Conclusion — the 2026 inflection and an invitation
For companies with exposure to specialty solvents, DMSO represents a classic “quality-over-quantity” opportunity: modest overall market size but outsized returns for firms that can control feedstock exposure, demonstrate certified purity, and lock in strategic partnerships with high-growth end-users. 2026 is the year to translate market visibility into binding commercial arrangements and targeted capacity plays. To convert this strategic overview into operational action, access to the full PW Consulting report is required — it contains the transactional numbers, regional and application splits, and supplier scorecards you will need to implement the decision levers outlined here.
For detailed analysis of this topic, please visit the official page: Dimethyl Sulfoxide (DMSO) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com