

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Camping Coolers Market Poised for USD 1,311M by 2032 at 6.3% CAGR — PW Consulting

Camping Coolers Market 2026: Strategic Preview and Executive Guide
As outdoor recreation continues its post-pandemic ascent, the camping coolers market has moved from niche utility to a strategic battleground for premiumisation, supply-chain optimisation, and regulatory compliance. PW Consulting’s upcoming full report (base year 2025) synthesizes five years of historical performance and a seven-year forecast to 2032, offering the granular playbook senior executives need to convert 2026 market momentum into durable advantage. This preview highlights the report’s strategic value without disclosing the detailed segment-level datapoints reserved for subscribers.
Camping Coolers Market
Market trajectory: What the headline numbers tell you
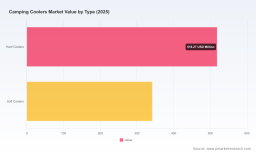
By PW Consulting’s base year (2025) the global camping coolers market reached an estimated USD 860.0 Million. The study projects a compound annual growth rate (CAGR) of 6.3% over the forecast window beginning in 2026, driving the market toward roughly USD 1.31 Billion by 2032. The near-term step from 2025 to 2026 continues an established growth trend that has accelerated with greater frequency of outdoor activity, product innovation in insulation and materials, and a consumer willingness to pay for performance and durability.
Camping Coolers Market
These headline figures conceal significant structural shifts: consolidation among premium rotomolded hard-cooler brands, an expanding addressable market for soft-sided and portable models, and an emergent cohort of electric/thermoelectric offerings for extended trips. The macro trajectory is robust—but the path to outperformance requires reading beneath the averages.
Camping Coolers Market
Three structural forces shaping 2026 decisions
- Demand-side evolution:
Outdoor participation has surged, with sector sources noting recreational engagement increases in recent years. Consumers are trading up—prioritising ice retention, durability, and convenience features such as bear resistance and wheeled mobility. This shift amplifies premium segments but also creates space for value players to carve volume-driven niches.
- Input volatility and manufacturing economics:
Almost all manufacturers rely on pressure-injected polyurethane foam for core insulation. Ongoing volatility in foam-resin markets is driving unit cost variability and production planning risk. For 2026, manufacturers that secure diversified resin supply, lock favorable contract terms, or redesign for alternative insulating materials will hold margin advantage.
- Regulatory and safety headwinds:
New regulatory signals are material. Notably, the Interagency Grizzly Bear Committee (IGBC) continues to formalise bear-resistant listing requirements, while the EU has announced energy efficiency and environmental standards for camping coolers effective within its jurisdiction by 2027. At the same time, large-scale recalls—such as the expanded recall of rolling-handle models by a major incumbent—remind executives that product safety and proactive risk management are fundamental to brand equity and distribution continuity.
Competitive landscape: incumbent strengths and points of disruption
The market remains moderately concentrated: the top three players account for a meaningful share of demand, and the top five collectively control an even larger portion of revenue. This concentration reflects brand equity around performance and durability, plus the scale benefits of rotomolding and distribution reach.
- YETI Holdings, Inc. (Austin, Texas): Market leader in premium, rotomolded hard coolers and insulated bags—focuses on product performance and lifestyle positioning.
- RTIC Outdoors LLC (Austin, Texas): Competes on price-for-performance with lightweight rotomolded and soft options—affects pricing dynamics across channel partners.
- Igloo Products Corp. (Bryan, Texas): Large legacy manufacturer with broad SKU breadth across hard and soft variants and rolling models—recent product safety events have amplified brand risk management topics.
- The Coleman Company, Inc. (Wichita, Kansas): Strong mass-market access and breadth through partnerships and private-label channels—important to consider for channel strategy.
- Other notable competitors: Grizzly, Pelican, Bison, Engel, Stanley, and rising specialist brands such as RovR, Canyon and K2—each pursuing niches (extreme durability, portability, powered cooling) that incrementally reshape feature expectations.
For 2026, competitive differentiation will be less about simply extending insulation claims and more about packaging integrated value: multi-channel fulfilment, robust safety and compliance traces, and lifecycle propositions (repairs, replacement parts, sustainability credentials).
Recent developments that change priorities
- Product recalls and safety notifications have elevated supplier audits and aftermarket remediation as board-level issues. The expanded recall of a major rolling-cooler model in 2025 underscores how design details (tow handles, pinch points) can translate into material reputational and financial costs.
- Product line expansions among emerging brands and private-label suppliers are compressing the pricing ladder while increasing SKU complexity in retail assortments.
- Regulatory moves—especially the EU’s forthcoming standards and IGBC listing requirements—will raise the bar on documentation, testing regimes, and potentially product redesigns for certain markets.
Why this report matters for 2026 corporate planning
Executives and strategy teams planning activity in 2026 face three interlinked tasks: allocate R&D and capex to the right product platforms, redesign supply chains to absorb raw-material volatility, and shape go-to-market to optimise for a bifurcated demand environment (premium performance vs. cost-sensitive volumes). PW Consulting’s full study provides the evidence base and scenario analysis needed to make those calls with confidence.
- Portfolio rationalisation: The report models how incremental R&D spend on insulation, lid seals, and rotomold efficiencies converts to competitive positioning and margin uplift across plausible demand scenarios.
- Supply-chain hedging: We provide actionable supplier segmentation and procurement playbooks that reduce exposure to polyurethane-resin shocks, including alternative insulation pathways and contract structures that preserve working capital.
- Regulatory compliance planning: The study maps the operational and cost impacts of IGBC and EU requirements, delivering a compliance calendar, testing budget guide, and redesign triggers to keep market access intact.
- Channel and pricing simulations: Detailed scenario tools enable CFOs and commercial teams to simulate promotions, private-label inroads, and MSRP adjustments while protecting perceived value of premium SKUs.
What the PW Consulting report contains (operationally oriented)
- Five-year historical demand analysis and SKU-level growth vectors.
- Bottom-up revenue and volume forecasts to 2032 with scenario sensitivity to raw-material shocks and regulatory outcomes.
- Competitive benchmarking and product-mapping across performance, durability, weight, and feature sets (bear-resistance, wheels, powered cooling).
- Supplier and manufacturing landscape: vendor scorecards, cost-to-serve analytics, and near-shore vs. off-shore capacity trade-offs.
- Commercial playbooks for premiumisation versus volume strategies, including retail assortment optimisation and digital-first launch frameworks.
- Regulatory impact assessment for IGBC and the EU energy/environment standards, including recommended testing protocols and cost estimates for compliance read-throughs.
- M&A and strategic partnership screening: candidate archetypes, valuation multipliers observed in the category, and integration risk checklists.
Strategic recommendations for 2026 (what to prioritise now)
- Lock critical resin supply and diversify insulation options: Negotiate multi-year supply agreements with indexed pricing and invest modestly in R&D pilots of alternative insulation systems to hedge material cost and availability risk.
- Invest selectively in safety engineering and documentation: Treat design-for-safety as a top-line enabler—avoid short-term SKU cost-outs that create recall risk. Build a remediation reserve and robust field-feedback loop.
- Segment the portfolio for clarity: Create clear, defendable product tiers (e.g., expedition, lifestyle premium, value portable) with tailored go-to-market and margin models rather than broad feature overlap that cannibalises your own SKUs.
- Capitalize on regulatory compliance as differentiation: Achieve early certification (IGBC, EU standards) for flagship models and use this as a commercial credential in both retail and institutional channels.
- Use aftermarket and services monetisation: Explore warranty extension, parts kits, and authorised repair networks to increase lifetime value and brand stickiness without heavy capex.
Next steps and how to use the full PW Consulting study
Team leaders preparing 2026 budgets should treat the full report as an operational playbook rather than a high-level industry primer. The appended scenario models are designed to be dropped into internal financial systems to stress-test product investments and channel plans. PW Consulting also offers tailored workshops to translate the findings into a 90–180 day activation plan: SKU pruning, supplier renegotiation, and compliance roadmaps that align product, operations, and sales.
For executives considering M&A or strategic partnerships, the study’s acquisition archetypes and integration risk matrices will help prioritise targets that either accelerate access to new materials technologies or broaden distribution in priority channels.
Final note
The camping coolers market blends durable-goods engineering with lifestyle consumer dynamics and increasingly complex regulatory overlays. The 2026 inflection point is not about volume alone; it is a test of who can manage input volatility, operationalise safety and compliance, and convert product performance into enduring brand value. PW Consulting’s comprehensive report aggregates the quantitative forecasts, competitive intelligence, and actionable playbooks that decision-makers need to ensure 2026 is not merely another year of growth, but a year of strategic value capture.
Access to the full dataset, segment-level forecasts, and the downloadable scenario models is available on PW Consulting’s report page—where the detailed inputs to these strategic recommendations are published for subscribers and corporate partners.
For detailed analysis of this topic, please visit the official page: Camping Coolers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com