

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Heparin Market to Expand at 4.57% CAGR Through 2032

Heparin Market 2026: Strategic Preview for Executive Decision‑Making
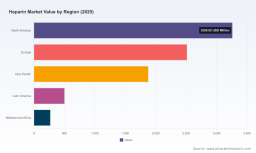
As the heparin market enters 2026, PW Consulting’s latest industry study — with a base year of 2025 and a forecast horizon through 2032 — crystallizes the commercial and operational pressures that will shape procurement, manufacturing and regulatory strategy. The market has grown from approximately USD 6.75 billion in 2020 to USD 8.42 billion in 2025, and our forward view begins at about USD 8.6 billion in 2026 with a compound annual growth rate (CAGR) of 4.57% across the 2026–2032 forecast window, taking the market into the low‑to‑mid double digit billions by 2032. These topline dynamics are foundational for 2026 planning, but the tactical value of the study lies in translating that macro momentum into executable moves across supply chain, product portfolios and regulatory engagement.
Heparin Market
Why this research matters for 2026 decisions
- Timing of investment decisions: Manufacturers and investors face a narrow window to mobilize capacity and secure raw material pathways. The report’s scenario models translate the stated CAGR and near‑term growth inflection into capacity funding timetables and payback windows.
- Supply chain resilience: With upstream concentration and animal‑sourced raw material risks, procurement teams need concrete diversification playbooks. Our analysis converts market growth into quantified sourcing gaps and prioritizeable mitigation options.
- Regulatory readiness: Emerging FDA guidance and evolving product determinations materially affect time‑to‑market and compliance costs. The study maps likely regulatory paths and their cost & schedule impact for 2026 actions.
- Competitive positioning: The market is moderately concentrated (CR3 ≈ 35%; CR5 ≈ 50%), which creates differentiated opportunities for mid‑sized players to scale through targeted tactics — from formulary access to specialty presentations. The study helps identify structural advantages and executional risks by player archetype.
What the report delivers — actionable content (select highlights)
- Executive summary with decision checkpoints tied to 2026 fiscal calendars and capital approval cycles.
- Market sizing & methodology: transparent reconciliation of historical 2020–2025 performance to the 2026 baseline, and the assumptions underlying the 4.57% CAGR.
- Supply chain map and risk heat map: origin points for porcine and alternative bovine raw materials, processing nodes, and critical single‑point failures.
- Regulatory impact assessment: interpretable pathways for reintroducing bovine heparin, anticipated FDA quality expectations, and compliance cost ranges for new entrants.
- Commercial scenarios (three discrete plays): base‑case growth, constrained supply shock, and accelerated diversification — each with P&L, cash‑flow and inventory implications tailored to manufacturers, distributors and wholesalers.
- Competitor playbooks and supplier scorecards — benchmarking capability sets (e.g., premix/prefill manufacturing, domestic production footprint, global supply networks) and recommended counterstrategies.
- M&A and partnership screen: prioritization matrix aligning strategic acquirers with target attributes, and a valuation sensitivity suite based on supply scarcity premiums.
- Procurement & sourcing playbook: contracting templates, inventory stratification (safety stock vs cyclical buffer), and a graduated supplier‑qualification fast track for emergency qualification.
- Implementation roadmap and 90/180/365‑day checklists for critical stakeholders (procurement, quality, regulatory, manufacturing).
Market dynamics to monitor in 2026
- Upstream concentration and feedstock risk: A large share of porcine‑sourced heparin raw material has historically traced to a limited number of geographies. Recent animal health shocks have exposed this vulnerability and forced an industry pivot toward diversification, including renewed interest in bovine‑sourced heparin. The implications are strategic — from capital allocation for alternative sourcing to long‑lead time validation programs.
- Regulatory signals: The FDA’s early‑2026 encouragement for prospective bovine heparin manufacturers, together with mid‑2025 determinations on specific product listings and continued shortage monitoring, signals both opportunity and compliance burden. Companies planning to enter or expand must budget for heightened process and analytical controls.
- Product & channel innovation: Demand for differentiated presentations — such as premixed bags and prefilled syringes — is a vector for margin protection. Recent product expansions by established manufacturers demonstrate how presentation diversity is being used to capture end‑user share.
- Price pressure and cost inflation: Short‑term forecasts anticipate raw material‑driven price increases in the single‑digit to low‑double‑digit percentage range annually. Procurement teams should embed indexed cost clauses and hedging mechanisms into contracts.
- Shortage management: Allocation risk remains real through late 2026 for certain presentations. The strategic playbook must include clinical prioritization frameworks and alternate anticoagulant pathways for health‑system partners.
Competitive landscape: profiles and strategic posture
The market features a mix of large, diversified pharmaceutical companies alongside specialized injectables manufacturers and US‑based sterile fill operations. The study distills the competitive implications for each company archetype and for their likely strategic moves in 2026.
Heparin Market
- Major diversified pharma (e.g., Pfizer, Sanofi): Leverage brand, distribution and regulatory capabilities. Strategic focus: portfolio optimization, tender capture and global channel expansion. Risk: lower relative agility in niche manufacturing shifts.
- Specialist injectables manufacturers (e.g., B. Braun, Baxter, Fresenius Kabi): Strengths include premix/prefill technology, established hospital relationships and domestic manufacturing capacity. Strategic focus: premium presentation expansion and hospital formulary entrenchment.
- Generics and CDMO players (e.g., Dr. Reddy’s, Teva, Hikma): Competitive on cost and scale; well‑positioned to capitalize on price recovery if raw‑material premiums normalize. Strategic focus: scale economics, contract manufacturing services and geographic arbitrage.
- US domestic sterile fillers and niche suppliers (e.g., Sagent, Techdow, AdvaCare): Provide critical fill/finish capacity, enabling near‑term supply resilience for domestic purchasers. Strategic focus: fast qualification channels with customers and potential to command scarcity premiums for on‑shore supply.
Collectively, the market’s CR3 and CR5 levels indicate meaningful market share held by top players, yet ample room for mid‑tier and specialist firms to expand via presentation differentiation, localized production and targeted partnerships.
Heparin Market
Strategic implications and recommended actions for 2026
- Prioritize dual‑track raw material strategies: Initiate parallel qualification for alternative animal sources and non‑animal processes where feasible. For organizations with limited capital, secure long‑term offtake agreements with contingency pricing clauses.
- Invest in presentation‑led differentiation: Expand premixed and prefilled options where clinical use and hospital economics favor convenience and safety. This supports formulary leverage and reduces exposure to commodity price cycles.
- Fast‑track regulatory engagement: Establish early dialogues with regulatory authorities where bovine or new source introductions are planned. Incorporate FDA quality expectations into early process design to shorten approval timelines.
- Negotiate supply contracts with scenario triggers: Include clauses for allocation, escalation, and substitution protocols tied to regulatory shortage declarations to protect revenue and ensure continuity for critical care customers.
- Assess strategic partnerships over greenfield builds: For near‑term capacity, prioritize CDMO partnerships or tolling arrangements that can be converted to JV or acquisition if scarcity persists into the medium term.
- Embed scarcity pricing into commercial models: Prepare tiered pricing and tender strategies to capture value during constrained supply windows while protecting long‑term volume commitments.
How to use this research in Q1–Q4 2026
- Reference the 90/180/365 day roadmap aligned to corporate budgeting cycles to inform capital approvals and supplier negotiations.
- Use our supplier scorecards and scenario P&Ls to stress‑test board‑level alternatives (capacity build, acquisition, long‑term purchasing agreements).
- Deploy the procurement playbook to reclassify inventory into tactical buckets and to negotiate contingency terms with top‑tier suppliers.
- Leverage the regulatory assessment to prioritize low‑friction submissions and to resource analytical labs for new source validation.
This industry preview is intentionally selective: it sets the strategy, frameworks and immediate actions that executives need to take in 2026 while preserving the granular segment‑level analytics and commercial models that drive transaction‑level decisions. For the complete dataset — including the detailed regional, type and application segmentation, supplier scorecards, scenario spreadsheets and executable templates — please consult the full PW Consulting Heparin Market report on our publication page.
For detailed analysis of this topic, please visit the official page: Heparin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com