

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Panel PC Market to Reach USD 310M by 2032 at 6.5% CAGR

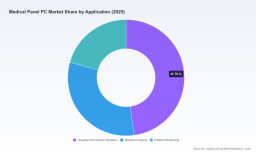
Medical Panel PC Market — 2026 Strategic Preview
As PW Consulting’s lead industry analyst, I present a focused strategic preview of our new Medical Panel PC Market study — a decision-grade briefing designed to inform executive choices across product development, procurement, and corporate development in 2026. Grounded in a multi-year demand model (historical 2020–2025; forecast 2026–2032), the research surfaces the structural forces shaping buyer behavior, the certification and cost thresholds that gate market access, and the practical playbooks that separate winning vendors from commodity suppliers.
Medical Panel PC Market
Executive snapshot — what the macro view means for strategy
The Medical Panel PC market is currently transitioning from a component-driven niche into a solutions-led healthcare IT segment. Our base-year analysis (2025) shows a market scale that positions vendors to invest in differentiated hardware and software capabilities while preserving margin discipline; the market is expected to grow at a steady mid-single-digit CAGR (6.5%) through our forecast window to 2032. That pace creates both runway and a finite window for strategic moves: firms that execute certification, productization, and channel alignment in 2026 will be best placed to capture disproportionate share over the following six years.
Medical Panel PC Market
Why this research matters to 2026 decision-makers
- Product roadmaps: The interplay between clinical certification, ingress protection, and edge compute determines allowable feature sets in hospital environments. Our report quantifies the trade-offs between processor tier, touch/display choices, and certification scope so R&D leaders can prioritize features with the highest return on investment.
- Go-to-market & procurement: Hospital group purchasing behavior has hardened around certification baselines. Procurement and sales leaders need concrete scripts and tender-ready documentation to win in competitive bid processes — the research translates market requirements into actionable GTM checklists.
- M&A and partnerships: Given the market’s moderate concentration and the capital intensity of certification, the report highlights the economic thresholds that make tuck-in acquisitions or strategic alliances attractive in 2026.
- Cost & pricing strategy: With average selling price dispersion by SKU tied closely to screen size, processing tier, and certification breadth, pricing teams can use our elasticity and cost-modeling frameworks to defend margin while expanding volume.
Market dynamics that will shape vendor success in 2026
- Certification is a commercial gatekeeper: In 2025, a large majority of U.S. hospital GPO tenders explicitly mandated IEC 60601-1 plus ingress and regional safety approvals as baseline vendor qualifications. This has moved certification from a compliance checkbox to a commercial prerequisite that materially affects addressable opportunity.
- High certification cost and lead time: Bringing a new platform through full IEC 60601-1 (fourth/third-edition transition considerations) carries non-trivial costs and timelines — on the order of hundreds of thousands of dollars and measured in quarters. These dynamics favor vendors that either amortize certification across multiple platforms or acquire already-certified assets.
- Component and ASP pressure: Certified medical panel PCs span a wide ASP window depending on feature and certification scope. Procurement negotiators are sophisticated; vendors that can map price to clinical value and document lifecycle TCO win incremental shelf space in hospital sourcing lists.
- Demand drivers shifting to compute & AI: Edge AI and higher-performance processors are migrating from “nice-to-have” to “must-have” in imaging, diagnostic, and perioperative workflows. Platforms that can safely host inferencing while meeting medical safety standards will command premium positioning.
- Security and data stewardship: Market requirements now expect hardware-rooted security options (e.g., TPM) and documented lifecycle support for clinical deployments. This is increasingly part of vendor qualification in major tenders.
Competitive landscape — actionable takeaways
The market exhibits moderate concentration: the top three vendors control a meaningful share of market value, and the top five capture an even larger portion. That structure creates distinct roles for market leaders, regional champions, and niche innovators. Below is a synthesis of incumbent positioning and near-term moves to watch in 2026.
Medical Panel PC Market
- Advantech (Taiwan)
Strengths: Broad platform portfolio and strong systems-integration capability. The POC series — now leveraging modern high-performance Intel processors and Edge AI support — targets diagnostic and nursing workflows that demand local inferencing. Strategic implication: Advantech’s scale and component sourcing advantages allow it to expedite AI-enabled productization, but it must continue to demonstrate clinical validation pathways to convert technical capability into hospital procurement wins.
- Cybernet Manufacturing (United States)
Strengths: Focused medical all-in-one systems with explicit IEC 60601-1 certification and proven hospital integrations. Recent product showcases tied to clinical partners (e.g., endoscopy solutions exhibited at DDW 2025) underscore the commercial value of device-to-device partnerships. Strategic implication: Cybernet’s route-to-market via OEM clinical partners is a replicable model for vendors seeking to bypass long-selling cycles to GPOs.
- Portwell (United States)
Strengths: Medical-grade hardware engineered for clinical environments (e.g., IP65 front panels) and operating-room-ready specifications. Strategic implication: Physical robustness combined with timely certification makes Portwell a preferred supplier for procedure-centric device makers and systems integrators where infection control and serviceability are decisive.
- Avalue Technology (Taiwan)
Strengths: Differentiation through hygiene-focused features (antibacterial coatings) and multitouch interfaces for bedside and nursing station use. Strategic implication: For deployments where infection prevention and user ergonomics are procurement priorities, aesthetic and hygiene differentiators materially shorten evaluation cycles.
- Wincomm Corporation (Taiwan)
Strengths: High-resolution touch solutions with ingress protection ratings designed for surgical and diagnostic settings. Strategic implication: Premium display and imaging credentials are a pathway to partnerships with imaging OEMs and advanced clinical suites where display fidelity is non-negotiable.
- ADLINK (Taiwan)
Strengths: Medical-certified lines targeting PDMS, HIS, and vital sign monitoring with medical-device-class certifications. Strategic implication: ADLINK’s embedded-software and certification depth make it a compelling partner for device manufacturers seeking a certified compute foundation rather than a custom do-over.
Recent vendor developments that change the 2026 playbook
- Product showcases at clinical conferences and co-marketing with clinical OEMs accelerate product validation cycles and shorten sales timelines.
- New CPU/GPU generations and availability of certified hardware platforms reduce the time-to-market for edge-AI capable solutions if certificates and documentation are planned upfront.
- Optional security modules (e.g., TPM) are becoming a procurement expectation rather than a differentiator; vendors should standardize secure options across mid- and high-tier SKUs.
What PW Consulting’s full report contains (practical, executable content)
- Proprietary market model with topline market sizing (historical and forecast through 2032), demand drivers, and scenario-based sensitivity to certification timelines, component cost inflation, and clinical adoption rates.
- Regulatory & procurement map that translates IEC 60601-1, ingress ratings, and regional safety approvals into concrete product development milestones and budget envelopes.
- Supplier benchmarking matrix that compares certification footprint, ingress compliance, lifecycle support, channel coverage, and software integration capability across leading vendors.
- Commercial playbooks: tender-response templates, technical datasheet checklist, clinical validation roadmaps, and a pricing architecture tuned to hospital TCO considerations.
- Productization blueprint outlining modular platform strategies to lower certification cost per SKU and reduce time-to-market for CPU/GPU refresh cycles.
- M&A and partnership guide with screening criteria calibrated to certification assets, installed-base defensibility, and route-to-clinical-channel synergies.
Note: While the report includes detailed segmentation by region, screen-size/type, and clinical application — including granular demand drivers and channel dynamics — this preview intentionally omits core segmented datapoints to preserve the commercial value of the underlying models. Clients interested in the full segmentation, downloadable data tables, and vendor scorecards may access the full study.
2026 strategic checklist — immediate actions for executives
- Prioritize certification investment or acquisition: map a realistic 12–24 month timeline and budget for IEC 60601-1 compliance if not already certified.
- Align R&D and product management around modularity: separate certified safety-critical elements from add-on compute/display layers to shorten refresh cycles.
- Lock in channel and clinical partnerships early: co-development with imaging or procedural OEMs can materially shorten adoption curves.
- Implement a procurement navigation plan: prepare tender-ready documentation and standardized compliance artifacts for GPOs and hospital procurement teams.
- Stress-test pricing against the ASP distribution in clinical procurement: demonstrable TCO savings and lifecycle support are the most defensible justifications for premium pricing.
Final note — why PW Consulting’s analysis is different
Our Medical Panel PC market study blends rigorous, bottom-up demand modeling with frontline commercial intelligence from procurement, clinical engineering, and product teams at hospitals and device OEMs. It is designed not as an academic report but as a playbook for 2026 execution: you receive the numbers and the how-to. If your 2026 strategic plan includes product launches, certification investments, channel re-engineering, or M&A, the full report provides the templates, vendor scorecards, and financial sensitivities needed to move from hypothesis to action.
To obtain the full study, including the complete segmentation tables, vendor benchmarking matrix, and downloadable financial model, please visit our report access page or contact the PW Consulting research desk for enterprise licensing and tailored advisory engagements.
For detailed analysis of this topic, please visit the official page: Medical Panel PC Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com