

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Chip Power Inductor Market to Reach USD 1,404.32 Million by 2032 at 4.1% CAGR

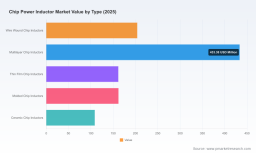
Chip Power Inductor Market: Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused briefing designed to equip executives, product leaders, and investors with the strategic context they need to act confidently in 2026. Our Chip Power Inductor Market study (base year 2025, historical window 2020–2025, forecast 2026–2032) distills complex technological shifts, supply-chain stressors, and competitive moves into a set of actionable implications. The market reached approximately USD 1,070 million in 2025 and is modeled to expand at a compound annual growth rate of 4.1% through 2032, when it is projected to be in the order of USD 1,400+ million. This report functions as a decision amplifier — revealing where value pools are forming and what capabilities will be required to capture them — while reserving the granular, proprietary segmentation data for subscribers.
Chip Power Inductor Market
Why this study matters for 2026 strategic choices
-
Investment timing: 2026 is a pivot year. Incremental improvements in inductor design and material processing are concentrated in high-growth automotive and power-management pockets; mis-timed capacity builds risk margin compression amid ongoing raw-material volatility.
Chip Power Inductor Market -
Portfolio prioritization: With steady overall growth but differentiated performance across form factors and qualification cycles, product roadmaps must align conserved R&D dollars with applications that offer the fastest payback and defensible technical barriers.
Chip Power Inductor Market -
Supply security: Metal and ceramic inputs (notably ferrite and copper) are on volatile trajectories. Manufacturers and OEMs must re-evaluate sourcing strategies, hedging, and strategic inventory to maintain continuity for automotive and industrial customers with long qualification lead times.
What the market numbers mean in practice
The market’s steady expansion at ~4.1% CAGR masks distinct operational realities. For incumbent suppliers, the moderate growth rate does not translate into uniform margin expansion: raw-material inflation, energy costs and tariff regimes create asymmetric pressure across product types and geographies. For new entrants, the path to commercial scale is gated by qualification cycles, capital intensity for advanced SMT lines or wire-wound capacity, and the ability to deliver consistent high-yield performance at automotive temperature grades.
Our forecast model integrates historic demand volatility through 2020–2025 and simulates supply shocks and regulatory changes through 2032. The headline market size increase to roughly USD 1.4 billion by 2032 principally reflects steady adoption of higher-efficiency multi-layer designs, incremental penetration of power inductors in emerging edge-compute and electric-vehicle domains, and continued replacement demand in industrial power modules.
Competitive landscape — who matters and why
The market remains moderately consolidated: a group of global suppliers control meaningful share, while a diverse set of regional players compete on cost, customization and speed-to-market. Our report presents an evidence-based supplier framework that scores firms across technology domain, manufacturing depth, customer mix, and go-to-market reach. Key strategic observations include:
-
Japanese engineering leaders (e.g., TDK, Murata, Taiyo Yuden, Panasonic) continue to lead on miniaturization, zero-defect processes, and automotive-grade qualification. Their investments in flat-wire and high-frequency multilayer technologies create high entry barriers in safety-critical applications.
-
European and US specialists (e.g., Würth Elektronik, Bourns) compete on modular system reliability, shielded designs, and strong distribution networks servicing industrial and IoT segments where reliability and availability trump absolute unit cost.
-
Taiwanese and Chinese suppliers (e.g., Chilisin, Shenzhen Sunlord, Fenghua) focus on cost-competitive multilayer and wire-wound variants, moving rapidly into automotive-tier supply chains through localized qualification and aggressive lead-time guarantees.
-
Sumida and other niche players emphasize high-current wire-wound solutions for industrial power electronics, targeting performance characteristics and custom solutions rather than commodity volume.
Recent product initiatives underscore how the competitive battle is evolving. New launches of high-reliability SMT series, ultra-small prototypes reaching unprecedented volumetric reductions, and part families optimized for automotive ECUs demonstrate supplier efforts to climb the value chain. Each of these moves has implications for long-term dynamics: tighter specifications raise customer switching costs, while miniaturization creates new opportunities in wearable and edge compute devices.
Supply-chain and regulatory dynamics shaping 2026
A handful of structural inputs are reshaping the economics of chip power inductors:
-
Raw-material inflation: Ferrite powder prices have experienced substantive increases in recent years, driven by constrained supply and energy-inflation pressures. This trend compresses margins for manufacturers that cannot pass through costs or optimize material usage.
-
Magnet and rare-earth policy: Tariff regimes and industrial policy in key markets — including continuing measures to expand domestic magnet production capacity — are altering sourcing decisions and creating incentives for near-shoring certain production stages.
-
Copper and commodity tightness: Elevated copper spot prices and supply competition with other tech sectors create premium spot markets. Inductor makers with flexible procurement or alternatives engineering capture resilience advantages.
-
Qualification and regulatory time: Automotive and industrial buyers enforce stringent qualification windows. Suppliers that can compress time-to-qualify through dedicated capability (testing labs, automotive-grade process control) unlock higher-margin contracts.
Report contents — pragmatic deliverables for 2026
Our full study provides a layered set of tools tailored for boardrooms and product teams. Highlights include:
-
Validated market sizing and 2026–2032 scenario models with sensitivity to commodity shocks and regulatory outcomes.
-
Technology trend analysis that maps design trade-offs (e.g., multilayer vs. wire-wound vs. molded) to application-level requirements and expected price trajectories.
-
Strategic supplier profiles and a proprietary supplier-scorecard that combines manufacturing footprint, product breadth, qualification credentials, and financial resilience.
-
Go-to-market playbooks for incumbents and challengers, including channel strategies, OEM engagement frameworks, and target customer archetypes by use case.
-
Commercial diligence pack for M&A or JV activity: unit economics, capex sizing for capacity expansion, and risk checklists tied to raw-material and trade-policy scenarios.
-
Practical implementation guides: short‑term hedging approaches, qualification-acceleration protocols, and sample inventory strategies to bridge multi-quarter supply shocks.
Note: While the study discloses aggregated market sizes and growth trajectories, it intentionally withholds certain granular segmentation tables and proprietary pricing curves from this preview. These datasets are included in full in the subscription report and are essential for precision tactical planning.
Implications and recommended actions for executives in 2026
-
Re-scope product roadmaps to prioritize modules with favorable return-on-capex and defensible technical differentiation — i.e., designs that require bespoke process expertise or raw-material know-how.
-
Lock strategic supply: enter selective long-term contracts for ferrite and copper, explore backward integration opportunities, or partner with upstream suppliers to stabilize input cost and availability.
-
Accelerate qualification pipelines for automotive and industrial customers through focused investments in test labs and cross-functional qualification teams; this shortens time-to-revenue for higher-margin segments.
-
Consider bolt-on M&A to rapidly acquire manufacturing depth in strategic geographies or to access proprietary materials know-how — especially for firms seeking to move from commodity to value-add positions.
-
Implement scenario-based pricing and contract clauses: index price escalators to specific commodity baskets and adopt graduated pass-through mechanisms to protect margins during spikes.
How PW Consulting’s research reduces execution risk
Our approach prioritizes decision-centric analytics over encyclopedic data dumps. The study blends bottom‑up component-level analysis with top‑down demand modeling, and embeds stress-tested scenarios for supply shocks and regulatory shifts. For commercial teams, the supplier scorecard accelerates shortlist creation. For financial sponsors, the M&A pack gives a play-by-play on capex, pro-forma synergies, and integration risks. For product leaders, the technology mapping connects component choices to system-level power efficiency and thermal budgets.
Next steps — where to get the full playbook
This briefing is designed as an executive “trailer”: it surfaces the strategic inflection points and operational levers that matter most in 2026, while preserving the proprietary segmentation and granular supplier economics for subscribers. If your strategic plan for 2026 hinges on optimizing product portfolios, securing supply, or pursuing M&A in the chip power inductor space, the full report contains the calibrated datasets and step-by-step recommendations you will need.
-
Access the full market models, supplier scorecards, and scenario toolkits via the PW Consulting report page — the only place where the granular regional and application splits, pricing curves, and product-level forecasts are available.
-
For bespoke support, PW Consulting offers tailored workshops that translate the report’s findings into a 90‑day execution plan aligned to your organization’s operating rhythm.
In sum, the chip power inductor market presents predictable growth at a system level but strategic complexity at the margins. Companies that combine disciplined portfolio choice, supply-chain savvy, and accelerated qualification capabilities will convert modest market growth into outsized returns. Our full study equips you to make those choices with confidence.
For detailed analysis of this topic, please visit the official page: Chip Power Inductor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com