

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Android POS Market to Reach USD 35.28B by 2032 at 17.48% CAGR

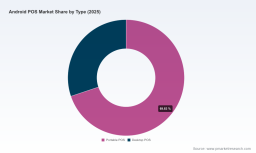
Android POS Market 2026: Strategic Imperatives — A PW Consulting Preview
Executive summary
The Android POS market has entered a decisive growth phase. After expanding from approximately USD 5.1 Billion in 2020 to roughly USD 11.5 Billion in 2025, our baseline model — using 2025 as the base year — projects continued acceleration through the 2026–2032 forecast window, reaching an estimated USD 35.3 Billion by 2032. That trajectory reflects a compound annual growth rate of about 17.5% and signals structural shifts in hardware platforms, software ecosystems and the services that wrap around them. For senior executives, procurement leads, product managers and private equity investors, this study translates those macro dynamics into actionable choices for 2026 planning cycles.
Android POS Market
Why this report matters for 2026 decision-making
-
Timing procurement and capitalization decisions: With a high-growth profile and notable component-cost volatility, timing matters. Our analysis links demand curves with supplier lead times to help procurement teams optimize inventory and contract terms for the coming 12–24 months.
Android POS Market -
Platform and software strategy: Android’s openness accelerates innovation but increases integration complexity. The report decodes which Android-based form factors and software-configurations are generating sustainable margins and which are becoming cost centers.
Android POS Market -
Partnership and M&A playbooks: Consolidation is underway — the top vendors account for a high share of market revenue (our concentration metrics show a dominant leading group). We map where strategic partnerships and tuck‑ins deliver the greatest ROI, and where scale or vertical specialization is essential.
-
Regulatory, tariff and supply-chain stress-testing: Major trade policy moves and component shortages are not background noise — they materially affect sourcing, pricing and go‑to‑market timing. The report embeds scenario analysis so you can stress-test budgets and route-to-market plans under plausible 2026 shocks.
Market trajectory — what the numbers reveal (high level)
The market’s compound annual growth rate of ~17.5% conveys more than scale: it reflects faster adoption of smart, software-centric point-of-sale solutions across retail, foodservice and new commerce touchpoints. Between 2020 and 2025 we observed a near-doubling in market size, and our forecast through 2032 signals continued expansion driven by higher per-terminal feature sets (payments, loyalty, analytics), omnichannel consolidation, and the migration of legacy POS estates toward Android-native systems. The pace of growth creates windows for capture but also raises the cost of delay — incremental share gains are attainable now but require investment in integration, support and verticalized offerings.
Competitive dynamics — what to watch in 2026
The competitive landscape is a mix of global platform vendors, specialists and vertically-focused OEMs. Market share is concentrated among a few leaders, but disaggregation on the value chain (hardware, payment processing, cloud services, partner ecosystems) creates niches for rapid entrants.
-
Square, Inc. — Leveraging Android in handheld and countertop devices, Square’s expansion into AI-driven analytics and omnichannel payment orchestration strengthens its SME footprint. Their tactics emphasize platform stickiness via software services, making them a high-priority competitor for customer-facing software partners.
-
NCR Corporation — Deep in retail and hospitality integrated systems, NCR’s Android-powered terminals are part of broader estate modernization plays. Their strength is systems integration and a services-heavy revenue mix that appeals to large retailers and chains seeking single-vendor solutions.
-
Diebold Nixdorf — Focused on self-service and countertop deployments, Diebold leverages Android to penetrate banking-adjacent retail and unattended commerce. Expect continued innovation at the intersection of security and user experience.
-
Worldline — Recent launches demonstrate a move to combine payments with loyalty and customer-engagement features in one SmartPOS. This converged value proposition targets SMEs and shifts competitive dynamics from pure payments to customer-relationship platforms.
-
PAX Technology, Ingenico (Landi Group), Verifone — These payments-native OEMs are scaling Android SmartPOS offerings, betting on multi-application ecosystems and global payments integration. Their global installed bases make them strong partners for acquirers and processors.
-
Sunmi, Telpo, Newland, Centerm, SZZT, PAX and Chinese OEMs — Cost-competitive, rapid product cycles and integrated value propositions characterize this group. They are increasingly relevant for volume-driven retail deployments and for solution providers seeking localized production flexibility.
-
Zebra Technologies, Advantech, MicroTouch — These players focus on ruggedized, enterprise-grade mobile computers and all-in-one systems. Recent product introductions (including GMS-certified Android 14 devices and larger all-in-one touch systems unveiled at NRF 2026) indicate a trend toward high-performance, platform-certified hardware targeted at larger retail and city-service deployments.
Recent vendor moves and why they matter
-
Worldline’s late-2025 SmartPOS launch illustrates the monetization of loyalty and engagement features on Android devices — a vector that turns hardware into a recurring revenue gateway for software and services.
-
MicroTouch’s 2026 Mach series announcement signals product refresh cycles accelerating toward higher-performance, multifunction terminals — an important consideration for enterprises evaluating refresh timelines and depreciation models.
-
Square’s early-2026 AI and omnichannel enhancements demonstrate that analytics and data-driven services will be central to differentiation, not just hardware form factor. This redefines TAM for software partners embedded in POS ecosystems.
-
Advantech’s GMS-certified Android 14 all-in-one launch highlights the importance of platform certification and tap-to-pay readiness — compliance and standards will influence enterprise procurement and risk assessments.
Supply chain, regulation and pricing dynamics
2025–2026 supply-chain dynamics are a principal driver of near-term strategic decisions. Industry studies indicate widespread tariff impacts and component-cost increases that have extended lead times and changed vendor economics. For example, corporate supply-chain surveys reveal a material share of firms reporting tariff-driven sourcing changes; fiscal and trade policy moves in 2025 triggered notable shifts away from a single-country dependency model toward diversified manufacturing footprints. Concurrently, chip and component pricing pressures have lengthened production lead times and prompted OEMs to adjust pricing and inventory strategies.
For decision-makers, this means that total cost of ownership (TCO) assumptions made in 2024 are often invalid in 2026 unless stress-tested. The report provides a set of supply-chain scenarios tied to procurement levers (contract terms, minimum order quantities, buffer inventory, nearshoring options) that directly translate into CAPEX/OPEX sensitivities for 2026 budgets.
What the PW Consulting report delivers (practical contents)
-
Granular market-sizing and a transparent forecast model (historical 2020–2025 base, detailed projections 2026–2032) with configurable assumptions for price, unit volumes and replacement cycles.
-
Vendor scorecards and a strategic heat-map covering technology, services, go-to-market reach and partner ecosystems to identify best-fit suppliers by use case.
-
Procurement playbooks, including RFP templates, certification checklists (security, GMS, payment compliance), and a TCO calculator that incorporates tariff and lead-time scenarios.
-
Go-to-market and product-roadmap recommendations for device manufacturers, independent software vendors and systems integrators, including partnership and distribution models likely to scale in 2026.
-
Scenario-based risk analysis tied to regulatory moves, tariff escalations and component shortages — designed to be operationalized directly into annual planning cycles.
-
M&A and investment playbooks with target archetypes, due diligence checklists for Android POS assets, and integration risk matrices aligned with consolidation dynamics.
How to use this preview to act now
-
Procurement: Shortlist two sourcing scenarios (best-cost and nearshore-ready) and run them through the report’s TCO model to set FY2026 budgets.
-
Product strategy: Prioritize modular software architectures that enable rapid updates and cross-sell of analytics/loyalty services — these yield higher lifetime revenue per terminal.
-
Partnerships: Identify top-3 vendor archetypes from our scorecards for piloting integrations; use the vendor negotiation playbook to secure longer warranty and certification SLAs.
-
Investors: Use the concentration and scenario outputs to identify consolidation targets and to value recurring revenue potential embedded in software-enabled POS offerings.
Next steps — where to find the full intelligence
This preview outlines the strategic contours and immediate actions relevant to 2026 planning. The full PW Consulting Android POS Market report contains the detailed segmentations, heat maps, forecast workbooks and executable templates referenced here. Those granular elements are intentionally gated to preserve their commercial value and to ensure you access up-to-date data and interactive models. Clients and subscribers can download the complete analysis and model pack from our report page or contact the PW Consulting advisory desk for a tailored briefing.
Closing perspective
The Android POS market’s rapid growth creates both opportunity and complexity. Winning in 2026 will require combining disciplined procurement, a clear product and services monetization strategy, and the agility to navigate supply-chain and regulatory headwinds. PW Consulting’s study converts the market’s growth and disruption signals into practical, executable choices — enabling leaders to convert market momentum into durable advantage.
For detailed analysis of this topic, please visit the official page: Android POS Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com