

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Lubricant Viscosity Index Improvers to Hit USD 330M by 2032 at 5.2% CAGR

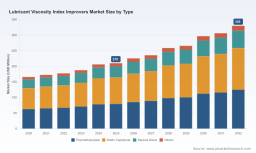
Lubricant Viscosity Index Improvers Market — Strategic Preview for 2026 Decision-Makers
Executive teaser
As companies position for the next cycle of product reformulation, regulatory compliance, and powertrain transformation, our latest PW Consulting study delivers a focused intelligence package on the Lubricant Viscosity Index Improvers (VII) market. Anchored on a 2025 base year and a multi-scenario forecast into 2032, this preview explains why the VII landscape will matter to capital allocation, R&D roadmaps, and commercial strategies in 2026 — and how to convert market momentum into durable competitive advantage. The full research contains the granular segmentation, supplier scorecards, and downloadable financial models referenced below.
Lubricant Viscosity Index Improvers Market
Market trajectory — the macro view
Between 2020 and 2025 the VII market demonstrated steady expansion, moving from the low‑hundreds of millions of dollars to an estimated USD 210.0 million in our 2025 base year. Our model projects continued growth through 2032, reaching an estimated USD 330.0 million under the central scenario — an effective compound annual growth rate (CAGR) of 5.2% from 2026–2032. The first forecast year (2026) shows uplift vs. 2025, reflecting recovery in mature transport segments, rising treat-rates in response to tighter specifications, and incremental demand from new industrial applications.
Lubricant Viscosity Index Improvers Market
Why this study is strategically material for 2026 planning
- Portfolio prioritization: The market expansion implied by a mid-single-digit CAGR creates meaningful margin and scale opportunities for additive formulators and base‑oil blenders. Deciding which polymer chemistries and product families to scale in 2026 will determine market share trajectories into 2030.
- Capital allocation and capacity timing: Capacity investments and third‑party tolling agreements require lead times measured in quarters. Our scenario timelines and demand ramp profiles translate growth expectations into commissioning windows that finance and operations teams can act on this year.
- Regulatory risk mitigation: New and evolving lubricant specifications are driving reformulation. The study maps likely specification trajectories and treat‑rate implications so product development teams can prioritize low‑risk, compliant platforms.
- M&A and partnership targeting: Fragmented but concentrated dynamics create buy-and-build opportunities. Our competitive overlay and valuation sensitives allow corporate development teams to sieve targets that deliver strategically accretive capabilities (e.g., shear‑stable PMAs, renewable-feedstock polymers).
- Commercial execution: Pricing elasticity, channel leverage, and differentiated product messaging for energy‑efficiency or hydrogen applications are all addressed with playbooks and war‑gaming scenarios tailored for 2026 deployment.
Demand drivers and disruption vectors
The VII market is being pulled and pushed by a small set of powerful forces that will shape supplier economics and customer requirements in 2026:
Lubricant Viscosity Index Improvers Market
- Regulatory tightening: Global lubricant specifications are increasing technical demands on VII chemistries — requiring higher oxidation stability, lower phosphorus carryover and increased dispersancy. These shifts are already prompting reformulation and higher treat rates in several lubricant classes.
- Downspeeding and lower-viscosity oils: The adoption of ultra-low-viscosity oils for fuel economy places premium performance expectations on shear stability and viscosity retention — a research priority for additive houses and OEM-approved formulators.
- Powertrain evolution: While electrification reduces some lubricant volumes, new mechanical systems (hybrid drivetrains, hydrogen-fueled engines) introduce niche growth pockets. Recent product launches targeted at hydrogen heavy-duty engines are indicative of how VII suppliers are hedging forward.
- Raw‑material and feedstock dynamics: Petroleum derivatives remain the primary feedstock for many VII polymers, but renewable-feedstock alternatives are emerging as regulatory and corporate carbon targets push formulators toward lower lifecycle emissions.
- Supply-side capacity shifts: Announced greenfield expansions and debottlenecking projects reshape regional availability and create windows for pricing and market-share moves; supply timing will matter for 2026 contracting cycles.
Competitive dynamics — what the market structure means
The market shows a concentrated top tier: our concentration metrics indicate that the three largest players account for a substantial share of global volumes, and the top five further strengthen that grip. This combination of scale advantage and technological differentiation produces a two-tier competitive environment in 2026: global majors who compete on R&D, global distribution and OEM approvals, and a set of regional specialists who win on cost, speed and tailored formulation services.
Player-level strategic lenses
- Lubrizol Corporation — a leader in both OCP and PMA platforms with a broad automotive and industrial footprint. Their emphasis on oxidation and thermal stability positions them well for higher-spec engine oils and long-drain applications.
- Chevron Oronite — known for olefin copolymer platforms and global manufacturing scale. Capacity expansions underway in Asia signal intent to defend commercial positions as regional demand grows.
- Infineum International — differentiated by work on ultra-low-viscosity and styrene-diene copolymer chemistries, making them a key contender for OEMs specifying very low SAE grades.
- Evonik and BASF — European specialty chemical strength focused on shear stability and energy‑efficiency polymer solutions, offering engineered PAMA/PMA technologies tuned for driveline and gear applications.
- Afton Chemical — rapidly moving into new application frontiers (e.g., dedicated hydrogen engine additives) and maintaining a broad HiTEC® portfolio across fuel and lubricant systems.
- Sanyo Chemical and regional producers such as Nanjing Runyou — operate with focused PMA offerings and competitive local service models that make them attractive partners for regional blenders and formulators.
Collectively, recent product launches and capacity commitments show incumbents accelerating both product development and regional footprint plays. For 2026, the strategic implication is clear: technical differentiation plus timely local availability will be decisive.
What the full report delivers — practical, transaction-ready outputs
This study is designed for executives and functional leaders who need immediately actionable materials for 2026. Highlights include:
- A calibrated market model (2020–2025 historicals; 2026–2032 forecast) with scenario toggles for demand elasticity, specification adoption rates, and feedstock shocks.
- Supplier scorecards and capability maps covering technology platforms, production footprints, product portfolios, and go-to-market channels.
- Formulation matrices that translate VII chemistries into treat‑rate guidance, performance trade-offs, and compatibility notes for common lubricant basestocks.
- Regulatory and specification impact assessment that quantifies likely reformulation vectors and identifies “safe” vs. “risky” chemistries under different standards trajectories.
- Supply‑chain heatmaps and inventory recommendations — highlighting potential pinch points for feedstocks and polymer intermediates through 2026 planning cycles.
- A commercial playbook and three ready-to-run go‑to‑market strategies: defend with scale, differentiate on performance, or partner for local acceleration.
- Valuation and M&A screening tools tuned to sector multiples, technology premiums, and synergies typical of the VII supplier universe.
90 / 180 / 360-day activation plan for 2026
- 90 days — Technical triage and quick wins: prioritize reformulation trials for products most likely to face new specifications; lock conditional offtake or tolling capacity for near-term supply risk mitigation.
- 180 days — Commercial and sourcing moves: finalize supplier qualification for key chemistries, execute pilot supply agreements, and begin targeted OEM engagement for co‑development of low‑viscosity shear‑stable blends.
- 360 days — Strategic scaling and portfolio bets: decide on capex vs. contract manufacturing for capacity needs, initiate M&A or JV discussions where inorganic scale would materially accelerate access to required polymer platforms.
Why PW Consulting — methodology and credibility
Our base dataset uses a 2025 anchor and reconciles historical market flows (2020–2025) with primary supplier interviews, OEM validation, policy scenario inputs, and proprietary demand models. We apply stress-testing across commodity feedstock scenarios and regulatory adoption curves. The result is a forecast suite (2026–2032) that is both defensible in governance and practical for executive decision-use.
Trailer — what we are intentionally withholding here
To preserve the report’s commercial value as a decision tool, this preview omits the granular segment tables (regional and end‑use splits by revenue and percent), the full company scorecards with technology-weighted ratings, and the downloadable financial model that lets you run bespoke scenarios. These elements are available in the full report and the accompanying data pack on our website.
Next steps — unlock the full analysis
If your 2026 planning requires scenario-ready forecasts, supplier-level risk matrices, or a transaction playbook tailored to viscosity index improvers, PW Consulting can provide the full report and a short executive briefing to translate insights into actionable commitments. The central market projection (anchored at USD 210.0 million in 2025 and projecting to USD 330.0 million by 2032 at a 5.2% CAGR) is only the starting point for a structured, executable strategy — access to the full model is the step that turns insight into impact.
For detailed analysis of this topic, please visit the official page: Lubricant Viscosity Index Improvers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com