

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Phycocyanin Market to Hit USD 285M by 2032 at 7.3% CAGR

Phycocyanin Market 2026: Strategic Imperatives for Decision-Makers
Executive teaser
As natural colorants continue to reshape formulation roadmaps across food, nutraceuticals, cosmetics and select pharmaceutical niches, phycocyanin has moved from niche ingredient to a strategic category with measurable market momentum. Our latest PW Consulting market study—anchored on a 2025 base year and extending through 2032—captures the commercial and regulatory inflection points that will materially influence boardroom choices in 2026. This article previews the study’s strategic value: it highlights the macro trajectory, exposes where profit pools are concentrating, and outlines the concrete decision levers executives should be ready to pull. To preserve actionable differentiation for subscribing clients, we intentionally withhold granular regional and application breakouts here; the full report contains those operationally decisive details.
Phycocyanin Market
Market trajectory: growth, scale and concentration
Phycocyanin’s global market moved from a measured specialty in 2020 to a clearly ascending growth profile through 2025. Our modeled series shows the market rising from approximately USD 121.5 Million in 2020 to a USD 175.0 Million base in 2025. Under a 7.3% compound annual growth rate (CAGR) for the 2026–2032 forecast window, the category advances further—reaching a projected market scale in the high hundreds of millions by 2032 (the forecast culminates near USD 285.0 Million). This combination of steady historical performance and sustained projected expansion frames phycocyanin as a mid-sized but strategically important ingredient for “naturalness” agendas.
Phycocyanin Market
Two structural features are especially noteworthy for strategy formation. First, the market is not atomized: three to five established players account for a meaningful share of supply (our CR3 and CR5 measures are roughly 48% and 58% respectively). Second, growth is not linear across all use-cases—some commercial segments are accelerating faster than others and are driving premiumization of higher-purity extracts and specialty formulations. These dynamics create room for scalable incumbents and well-capitalized challengers to capture differentiated margins.
Phycocyanin Market
Why 2026 is a pivot year for corporate strategy
-
Regulatory inflection: The U.S. regulatory timeline in early 2026 exemplifies how regulatory outcomes can rapidly alter addressable markets. A favorable amendment to the U.S. color additive listing materially expands permitted uses for Spirulina Extract (phycocyanin), but subsequent procedural delays underscore ongoing uncertainty. Executives must therefore treat regulatory developments as binary triggers for commercialization timing, pricing strategies, and inventory positioning.
-
Supply-side volatility and feedstock economics: Spirulina biomass—the primary feedstock for phycocyanin—remains a key cost driver. Industry techno-economic benchmarks indicate a broad quality-dependent price band for spirulina biomass (approximately USD 6–18 per kg). That range implies wide variability in extraction economics and margin profiles for downstream phycocyanin products, making feedstock sourcing strategy and vertical integration critical levers.
-
Consolidation and capacity investments: The category is at a crossroads where capex-backed capacity expansions (including smart-farming and integrated extraction plants) can rapidly tilt commercial advantage toward scale-oriented players. Recent capacity investments by established producers signal a bifurcation between commodity suppliers and integrated premium specialists.
Strategic actions for 2026
For corporate leaders building 2026 plans, five pragmatic strategic responses should be prioritized—each of which is unpacked with operational playbooks in the full PW Consulting report.
-
Regulatory readiness and scenario planning: Establish a cross-functional regulatory war room that maps jurisdictional approval states, trigger points for market entry, and pre-emptive labeling strategies. Plan for at least two commercialization scenarios tied to U.S. FDA timing (accelerated approval vs. delayed effective dates) and stress-test inventory, marketing, and distribution plans against both.
-
Feedstock and supplier strategy: Develop a dual-track sourcing approach: (1) near-term tactical contracts to secure volume and manage price volatility; and (2) medium-term investments in farming partnerships or partial vertical integration to capture extraction margin and quality control. Where purity and traceability are commercially differentiating, prioritize suppliers with verified cultivation practices and certifications.
-
Product & formulation roadmap: Differentiate by combining functional claims (e.g., antioxidant positioning) with sensory and stability improvements. Higher-purity extracts command premium positioning but require complementary formulation know-how—invest in application labs or co-development agreements to reduce time-to-market.
-
Commercial footprint and channel selection: Reassess go-to-market channels regionally: where regulatory clarity aligns with consumer demand for natural ingredients, prioritize rapid commercial launches in food and beverage. For markets with higher regulatory friction, focus on nutraceutical and cosmetic uses that can tolerate longer adoption cycles and higher per-unit pricing.
-
M&A and strategic partnerships: With a concentrated supplier base, targeted M&A or minority investments can secure feedstock, capability, or proprietary purification technology. Look for bolt-on acquisitions that provide either capacity scale or intellectual property that shortens time-to-purity thresholds.
Competitive landscape: how incumbents are positioning
The supply map today is a mix of vertically integrated producers, specialty color houses, and nimble regional manufacturers. Leading corporates are pursuing three observable plays:
-
Vertical integration and capacity scaling: Producers with upstream cultivation control aim to lock in quality and lower extraction costs. Recent facility expansions demonstrate a wager on tighter control of biomass supply and on modern, lower-footprint cultivation technologies.
-
Product standardization and industrialization: Specialty colorants providers are introducing standardized extract grades to facilitate industrial scale beverage and processed food use, reducing formulation headaches and accelerating adoption among large CPG customers.
-
Geographic and regulatory arbitrage: Regional players leverage lower-cost cultivation ecosystems and proximity to large ingredient pools to win export opportunities, while established multinationals focus on regulatory-compliant supply and branded solutions.
The net effect: competitive intensity is rising, but barriers remain. Purity, supply chain traceability, and regulatory-compliant documentation are differentiators that sustain margin separation. Our competitive profiles of core suppliers spotlight differentiable capabilities (e.g., integrated farming and patented purification vs. standardized industrial grades), and map those to opportunity spaces in food, nutraceutical, cosmetic and select pharma uses.
Regulatory and trade considerations
Regulation is the single most consequential externality in 2026. Recent federal-level activity in the U.S.—including a change in the color additives listing for Spirulina Extract followed by a temporary delay in effective date—illustrates both upside and procedural risk. Companies must plan for variable regulatory timing, maintain rigorous documentation of cultivation and extraction processes, and be prepared for jurisdiction-specific labeling and use limitations.
On trade and tariff matters, standard HS code treatment for natural pigments applies to spirulina blue exports, which means international trade flows are subject to routine customs classification and the associated logistical frictions—important for procurement and landed-cost modeling. Tariff exposure, clearance timelines, and country-of-origin considerations should be built into sourcing scorecards.
What PW Consulting’s full study provides (high-level)
-
Proprietary demand-supply model (2020–2032) with scenario levers for regulatory timing, feedstock price shocks, and accelerated application adoption—delivered with interactive dashboards for rapid sensitivity analysis.
-
Supplier and technology scorecards that evaluate capacity, vertical integration, purity grades, certifications, and commercial references—designed for procurement and M&A diligence.
-
Actionable commercial playbooks: go-to-market blueprints for each major application cluster, launch checklists, price-mix optimization heuristics, and sample co-development contracting templates.
-
Capital and operating benchmarks for cultivation and extraction facilities, including capex / opex ranges and payback scenarios under multiple feedstock price and purity outcomes.
-
A regulatory risk matrix linked to practical mitigations—compliance documentation templates, accelerated approval pathways, and labeling contingencies.
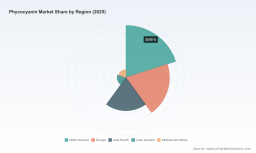
For confidentiality and commercial value protection, we have omitted the granular regional and application-level split tables from this public preview. Those tables—together with supplier-level contact intelligence and downloadable financial models—are included in the comprehensive report package.
Immediate next steps for leaders
-
Embed phycocyanin scenarios into 2026 revenue and sourcing plans now; treat regulatory milestones as explicit go/no-go gates.
-
Initiate supplier audits focused on traceability, extraction yields and certifications if pursuing premium applications.
-
Assess capex options for near-term capacity control versus long-term partnerships; quantify margin sensitivity to spirulina price bands.
-
Prioritize one pilot product launch in a targeted channel where regulatory clarity exists and consumer willingness-to-pay is established—use it as a proof point for scale-up decisions.
Conclusion
Phycocyanin is transitioning from specialty curiosity to a strategically important natural ingredient with clear commercial pathways for firms that can master supply consistency, regulatory timing, and formulation differentiation. The market’s macro path—anchored at roughly USD 175.0 Million in 2025, with a projected trajectory to approximately USD 285.0 Million by 2032 at a 7.3% CAGR—creates tangible opportunity. Yet the winners in 2026 will be those who convert regulatory and sourcing intelligence into concrete operational moves: securing feedstock, selecting the right commercialization windows, and investing in the purity and formulation capabilities that deliver customer value.
PW Consulting’s full Phycocyanin Market report provides the operational intelligence and decision-support tools executives need to act confidently in 2026. For access to the complete dataset, supplier scorecards, and executable playbooks, please visit our report page or contact our industry team to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Phycocyanin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com