

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Data Loggers Market to hit USD 621M in 2025, growing at 7.1% CAGR

Data Loggers Market 2026 Preview: Strategic Imperatives for Decision‑Makers
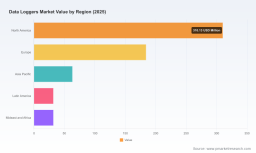
As organizations across healthcare, life sciences, cold chain logistics and industrial segments re‑engineer operations for post‑pandemic resilience, the data loggers market has evolved from a point‑solution category into a node of regulatory compliance, digital assurance and recurring‑revenue opportunity. PW Consulting’s latest study — anchored on a 2025 base year and an expanded 2026–2032 forecast horizon — quantifies a market that grew from roughly USD 440 million in 2020 to USD 621 million in 2025, and is projected to expand at a compound annual growth rate (CAGR) of 7.1% thereafter. That trajectory puts the market on course to breach the USD 1 billion mark by the early 2030s, creating near‑term and strategic inflection points for vendors, buyers and investors entering 2026.
Data Loggers Market
Why this research matters for 2026 decisions
2026 is the first full operating year after several harmonizing regulatory and reimbursement changes that materially affect procurement and product design for data loggers. The FDA’s Quality Management System Regulation (QMSR), effective February 2026, formalizes alignment with ISO 13485 for medical device quality systems. Parallel moves — WHO prequalification acceptance of specific logger series for vaccine programs, VFC program requirements for NIST‑calibrated continuous monitoring, and updated CPT guidance expanding Remote Patient Monitoring (RPM) coverage for device supply and monitoring services — are collectively shifting buyer preference toward certified, networked and auditable logging solutions.
Data Loggers Market
For corporate leaders planning capital allocation, procurement, product roadmaps and M&A through 2026, the practical implication is clear: regulatory compliance and data lineage are now non‑negotiable design drivers. Our analysis demonstrates that market growth is concentrated where compliance, lifecycle services and connectivity intersect. Companies that can translate certificate‑level assurance into operational simplicity for users will capture disproportionate share of growth as the market expands from a defined installed‑base to ubiquitous, cloud‑enabled monitoring.
Data Loggers Market
Market dynamics: what’s driving growth — and where risk accumulates
-
Regulatory harmonization and certification demand: With ISO 13485 alignment embedded in FDA QMSR and WHO/UNICEF programs requiring approved loggers for immunization programs, procurement teams prioritize traceability, validated software and calibrated hardware. This increases go‑to‑market complexity (and opportunity) for vendors that sell validated solutions and managed calibration services.
-
Shift to IoT + SaaS: Buyers are moving from single‑use, stand‑alone devices to hybrid models that combine disposable loggers for episodic shipments with multi‑use wireless and BLE devices feeding cloud analytics. SaaS pricing and subscription economics are transforming lifetime value and enabling predictable recurring revenue for suppliers.
-
Clinical trials and biologics cold chain scale-up: Growth in biologic therapies and decentralized trials is creating a floor for demand in validated temperature management across transport and storage, an area where ultra‑low temperature devices and validated cloud platforms carry premium value.
-
Reimbursement and remote monitoring tailwinds: Changes to RPM CPT codes for 2026 expand pathways for devices to be bundled into reimbursable care pathways, opening a new buyer cohort in home‑based therapy and distributed clinical monitoring.
-
Risk vectors: interoperability gaps, device cybersecurity, calibration and lifecycle management, and logistics cost pressures remain structural risks. Vendors that neglect ecosystems — integrations with LMS/WMS, EHRs, and logistics partners — will see slower adoption despite competitive product features.
Competitive landscape: positioning the major players
The data loggers market is best described as commercially active and moderately fragmented. Top vendors have defined niches, but the overall top‑five concentration remains in the low‑30% range, indicating an open field for focused scale plays or roll‑up strategies.
-
Onset Computer Corporation (Bourne, MA) — Onset’s HOBO and InTemp IoT product lines are positioned around cold chain validation and CDC/VFC‑compliant vaccine storage monitoring. Their 2026 introduction of an ultra‑low temperature data logger highlights a deliberate push into biologics and vaccine logistics where cold‑chain assurance is mission critical. For buyers, Onset signals a vendor roadmap that pairs hardware innovation with validated use cases for medical storage.
-
LogTag Recorders (New Zealand) — LogTag’s established role supplying temperature loggers to global immunization programs (including WHO, UNICEF and CDC initiatives) gives it credibility in high‑assurance vaccination and pharmaceutical distribution. For procurement teams focused on global program compliance and supply constraints in emerging markets, LogTag remains a reference vendor with deep operational track record.
-
ELPRO‑BUCHS AG (Buchs, Switzerland) — ELPRO’s LIBERO series (wireless and USB PDF loggers) focuses on GxP/GMP environments supporting pharma, biotech and healthcare customers. Their 2026 free return shipping initiative for single‑use LIBERO devices represents an innovative service play designed to lower TCO for global cold‑chain monitoring and expand addressable market by simplifying logistics for endpoint users.
-
TSS AB (Solna, Sweden) — TSS targets life sciences and clinical trials with TempTracer BLE multi‑use loggers and a cloud SaaS layer. Their event sponsorship activity in 2026 underlines a strategy of partnering with clinical supply chain and trial stakeholders to embed temperature management into trial execution workflows.
Where winners will emerge in 2026
Across vendor models, three strategic approaches are showing the highest probability of success as the market expands at approximately 7.1% CAGR:
-
Compliance‑First Productization: Products that ship with documented, auditable calibration pathways and are architected to meet medical device QMS expectations command faster approval in healthcare procurement cycles. Certification and GxP readiness reduce adoption friction.
-
Services‑Led Monetization: Companies that couple hardware with lifecycle services — bundled calibration, managed returns, software validation packages and analytics subscriptions — unlock higher lifetime value and predictable revenue. ELPRO’s logistics initiative is an example of service innovation that can drive adoption in price‑sensitive channels.
-
Ecosystem Orchestration: Interoperability with TMS/WMS, EHR and clinical trial platforms — plus robust APIs and security practices — creates switching costs and defensibility. TSS’ clinical trial focus reveals the potential of deep vertical integrations versus horizontal feature competition.
How our report helps you act in 2026
PW Consulting’s Data Loggers Market research is designed as an operational playbook for 2026. It blends quantitative market sizing (historical trajectory and a detailed 2026–2032 forecast), scenario planning and vendor due‑diligence with tactical tools that procurement, product and corporate development teams can deploy immediately:
- Validated forecast models and sensitivity analyses that quantify revenue upside under alternative regulatory and reimbursement scenarios.
- Vendor scorecards that compare compliance posture, connectivity stack, service offerings and TCO impacts (note: the report deliberately preserves granular regional and segment-level figures behind our subscriber portal to protect proprietary segmentation models).
- Go‑to‑market playbooks for suppliers — channel strategies for cold chain logistics providers, SaaS packaging for life sciences customers, and clinical trial partnership templates.
- Procurement checklists and RFP templates focused on certificates, calibration pathways, data security and audit trails aligned with FDA QMSR and ISO 13485 expectations.
- Case studies showing ROI of hybrid logger strategies (single‑use + wireless fleet + cloud analytics) in cold chain validation and decentralized clinical trial monitoring.
- Tactical M&A screening criteria for roll‑up opportunities: unit economics thresholds, service penetration targets, and integration playbooks for consolidating calibration and logistics services.
Key considerations for boardrooms and product teams
Boards and product leaders deciding on capital deployment in 2026 should weigh three interdependent considerations: regulatory timing, service economics and ecosystem access. Regulatory moves provide both runway and constraints — they increase demand for certifiable products but also raise compliance costs for new entrants. Service economics transform product pricing; the ability to monetize recurring calibration and SaaS will separate higher‑margin vendors from hardware‑only competitors. Lastly, ecosystem access — measured by a vendor’s ability to plug into logistics providers, trial supply managers and healthcare IT — is a gate to scale. Our research provides the metrics and scenario tools leaders need to quantify these tradeoffs before committing to large investments or acquisitions.
Next steps: using this insight without delay
As the data loggers market transitions from specialized instrumentation to integrated compliance platforms, the decisions organizations make in 2026 will determine who captures the scale and who is relegated to price‑competitive commodity supply. PW Consulting’s report is structured as a guided diagnostic: high‑level readers can validate strategic direction with the executive summary and scenario charts; product and procurement teams can deploy checklists and RFP templates; corporate development can use our vendor scorecards and M&A filters to prioritize targets.
For a complete set of segmented forecasts, vendor ratings, and the full suite of practical playbooks and downloadable templates — including the confidential segmentation matrix that maps product types to application economics and regional demand drivers — consult the full PW Consulting Data Loggers Market report and subscriber portal. The executive preview above is intended to establish the market arc and strategic stakes without disclosing the proprietary, transaction‑level detail that underpins our recommendations.
For detailed analysis of this topic, please visit the official page: Data Loggers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com