

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Explosion Proof Equipment Market to Expand at 6.2% CAGR by 2032

Explosion-Proof Equipment Market — Strategic Outlook for 2026 Decision-Makers
Executive teaser
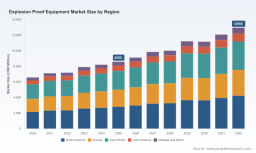
The global explosion-proof equipment market is moving from incremental safety upgrades to strategic infrastructure investment. PW Consulting’s latest study (base year 2025, historical 2020–2025, forecast 2026–2032) quantifies this transition and turns it into actionable choices for executives preparing budgets, product roadmaps, and M&A strategies in 2026. The market expanded from approximately USD 6,580 million in 2020 to USD 8,590 million in 2025 and is forecast to grow at a compound annual growth rate (CAGR) of 6.2% over the 2026–2032 horizon, reaching roughly USD 12,960 million by 2032. This briefing highlights the strategic value of that research without disclosing the granular segmentation reserved for the full report.
Explosion Proof Equipment Market
Why 2026 is a strategic inflection point
-
Capital cycles and retrofit windows converge in 2026. Many operators in heavy industry — from hydrocarbons and chemicals to mining and power generation — face mid‑life asset assessments that prioritize safety, compliance, and digital enablement. That creates a multi-year procurement runway for explosion-proof products and integrated systems.
Explosion Proof Equipment Market -
Regulatory and certification pressures are intensifying. Certifications such as ATEX, IECEx, FM and local approvals are becoming gating criteria for project qualification. Manufacturers with robust certification portfolios will capture more than short‑term orders; they will secure preferred supplier status on multi‑year programs.
Explosion Proof Equipment Market -
Technology convergence — especially the incorporation of sensors, remote actuation, and intrinsically safe communications — is turning a previously product‑centric market into a solutions market. Buyers increasingly prize integrated systems and lifecycle services over commodity enclosures.
What PW Consulting’s report delivers (practical content summary)
The full study is designed as an executive toolkit for 2026 decision-making. Key deliverables include:
-
Top‑line demand model and validated market sizing (historical and projected to 2032) with scenario logic that isolates price, volume, and replacement drivers.
-
Multi-angled growth outlook: baseline, upside, and downside scenarios tied to macro energy trajectories, commodity cycles, and regional CAPEX trends.
-
Procurement playbook for asset owners: tender framing, specification checklists (including certification matrices), and total cost of ownership (TCO) templates spanning capex and aftermarket spend.
-
Go‑to‑market and channel strategies for vendors: partner mapping, distributor scorecards, and regional entry playbooks tailored to differing regulatory regimes.
-
Supply chain resilience diagnostics: critical raw‑material exposure (e.g., cast aluminium, cast iron, stainless steel), single‑source risk flags, and hedging and nearshoring options.
-
M&A and strategic partnership framework: target screening criteria, synergy capture estimates, and integration checklists focused on certification, IP, and aftermarket service footprints.
-
Competitive benchmarking and capability heatmaps across product classes, certifications, and service offerings — presented so buyers and investors can prioritize engagement without getting lost in raw SKU data.
Key market dynamics shaping strategy
-
Safety and compliance are table stakes. Certification burdens (ATEX, IECEx, FM, regional marks) are increasing procurement friction. Suppliers that demonstrate repeatable, auditable compliance workflows command pricing premiums and preferred‑supplier status.
-
Materials and manufacturing footprint matter. Explosion‑proof enclosures and control hardware commonly utilize cast aluminum, cast iron, and stainless steel — materials with distinct supply chain exposures and cost drivers. Decisions on material mix affect long‑term margins and responsiveness to market shocks.
-
Service and aftermarket revenue is a differentiator. With rising installed bases, remote diagnostics, certified inspection cycles, and spare parts logistics are lucrative and sticky revenue streams that improve lifetime customer value.
-
Modular, certified automation is accelerating adoption. Recent product launches in actuator remote control and variable speed actuation demonstrate vendor emphasis on retrofit-friendly, certified automation that extends asset life and reduces downtime — a compelling value proposition for owners in wastewater, power, and process industries.
-
Market fragmentation creates opportunity. The market exhibits modest concentration: the top three players represent roughly 25.8% and the top five about 35.4% of revenue, indicating a competitive landscape with many regional specialists and niche vendors. This opens room for roll‑up strategies and partnership-based scale plays.
Competitive landscape — strategic implications of key players
Understanding the incumbent and emerging players is essential to allocate resources and prioritize partnerships. The report includes granular vendor profiles; below is a strategic read on selected corporate positions.
-
Eaton Corporation plc (Crouse‑Hinds series) — With deep heritage in explosion‑proof lighting, conduit fittings, and enclosures, Eaton leverages broad channel reach and integrated system capabilities. Their strength is product breadth and brand recognition in established end‑markets; strategic moves will likely focus on cross‑selling digital offerings into installed bases.
-
Emerson Electric Co. (Appleton Electric) — A portfolio player with strong product engineering for Class I–III environments. Emerson’s advantage is systems integration and end‑user relationships in critical process segments; watch for bundled instrumentation and services that shift procurement from line‑item buys to long‑term service agreements.
-
nVent HOFFMAN — Specializes in stainless and carbon steel enclosures for process control. Their differentiation is manufacturing scale and corrosion‑resistant offerings — attractive to operators facing harsh environments and long service life requirements.
-
AUMA Riester GmbH & Co. KG — A notable innovator in explosion‑proof actuators. Recent 2026 product launches (remote control RSTX 100 and variable speed actuators) and corporate reorganizations signal a push to combine product innovation with nimble commercial execution. These moves make AUMA a candidate for strategic partnerships in valve automation and long‑term maintenance contracts.
-
TMEIC Corporation — Focused on pressure‑resistant, IECEx‑certified motors suitable for hydrogen and other demanding applications. Their niche strength positions them well in energy transition projects (e.g., hydrogen handling), where specialized certification and robust engineering can command higher margins.
-
KSB SE & Co. KGaA — Strong in explosion‑proof pumps with ATEX certifications; their product focus aligns with OEM and project‑level procurement in water, oil & gas, and industrial fluids markets.
-
Bharat Flameproof Manufacturing — A cost‑competitive, IECEx‑certified supplier from India, well positioned to serve regional projects and international customers seeking price‑sensitive alternatives that meet certification thresholds.
-
HEXLON (Helon) — Chinese manufacturer with ATEX, IECEx, and CCC certifications; competitive in distribution boxes, circuit breakers and control equipment for hazardous areas. Watch their export strategy as certification enables broader market access.
-
Ex‑Machinery B.V. — Specialist in certified HVAC and environmental control systems for hazardous zones (Zone 2/22). Their offerings are increasingly relevant as operators seek integrated thermal management solutions for enclosures and control rooms.
-
POSITAL‑FRABA (rotary encoders and sensors) — Suppliers of ATEX‑certified sensors and encoders are pivotal in enabling digital upgrades and reliable remote monitoring in hazardous areas; such components are often the linchpin in retrofits that convert legacy assets into digital assets.
Recent corporate moves as a window into near‑term competition
-
AUMA’s early‑2026 launches (remote controls and variable speed actuators) show how product innovation is shifting the competitive battleground from purely mechanical reliability to operational flexibility and remote operability.
-
Certification claims across multiple suppliers — IECEx, ATEX, FM, CCC — indicate that certification portfolios are now a litmus test for market access. This favors firms with deliberate certification roadmaps and creates entry hurdles for smaller manufacturers without the compliance resources.
How to use this research in 2026 decision‑making
-
Portfolio prioritization: Use the demand model to allocate R&D and product investments to product families and regions with the highest risk‑adjusted returns — but obtain the full segmentation tables in the report to avoid misallocation based on intuition alone.
-
Procurement optimisation: Adopt the report’s tender templates and certification matrix to shorten procurement cycles and reduce specification disputes, improving vendor responsiveness and reducing project delays.
-
M&A and partnership screening: Apply the deal framework to identify tuck‑ins that accelerate certification, expand aftermarket service capabilities, or secure manufacturing scale in key materials (cast metals, stainless steel).
-
Supply chain resilience: Implement the report’s supplier stress test to quantify single‑source and geopolitical risk, and deploy nearshoring or dual‑sourcing strategies where necessary.
-
Commercial tactics: Introduce bundled offerings combining certified hardware with lifecycle services and remote monitoring to increase share of wallet and convert one‑off sales into annuity revenue.
Closing note — the purpose of this preview
This briefing demonstrates the type of strategic clarity PW Consulting’s Explosion‑Proof Equipment Market study provides for 2026 planning: validated top‑line forecasts, scenario logic, supplier diagnostics, and executable playbooks. To preserve the practical commercial value of the dataset — including granular regional, type, and application splits, unit‑price curves, and the vendor scorecards that inform procurement and M&A decisions — those detailed tables and models are available in the full report. For executives who must convert market insight into decisive action in 2026, the full analysis is purpose‑built to be operational from day one.
For detailed analysis of this topic, please visit the official page: Explosion Proof Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com