

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Defibrillator Market to hit USD 19,372M by 2032 at 7.35% CAGR

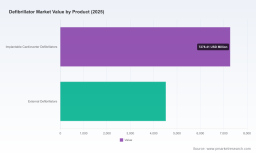
Defibrillator Market 2026: Strategic Intelligence for Decisive Corporate Action
As healthcare systems and device manufacturers confront accelerating demand for cardiac rhythm management, the defibrillator market is entering a decisive phase in 2026. This briefing previews the strategic value of PW Consulting’s full Defibrillator Market report for executives, corporate development teams, and commercial leaders who must translate macro momentum into competitive advantage. It demonstrates the type of analysis you can expect from the full study while preserving the granular segmentation and proprietary tables that are reserved for subscribers.
Defibrillator Market
Market trajectory and the 2026 inflection
At the macro level, the market has shown sustained expansion through the first half of the decade and remains on a robust growth trajectory. From a base year of 2025, when the global defibrillator market reached approximately USD 11.8 billion, our forecast model projects a compound annual growth rate (CAGR) of about 7.35% over the 2026–2032 horizon. By the end of the forecast period the market is expected to approach the high single-digit billions in incremental scale, reflecting continued demand across clinical, pre-hospital, and consumer-oriented channels.
Defibrillator Market
For decision-makers, that growth profile signals two immediate implications for 2026 strategy: first, structural demand is sufficient to support both organic investment and targeted M&A; second, timing matters — investments made in 2026 will compound into meaningful share and revenue gains across the forecast window.
Defibrillator Market
Drivers shaping near-term opportunities
- Technology convergence: Wearable cardioverter-defibrillators (WCDs) and advanced AEDs increasingly embed software, AI signal processing, and remote monitoring — shifting value from hardware alone to integrated clinical workflows and data services.
- Shifting care settings: Growth in public-access programs, expanding home-care adoption, and more sophisticated EMS/hospital interfaces create differentiated commercial channels and demand for interoperable devices.
- Regulatory and reimbursement tailwinds: Recent regulatory approvals and reimbursement changes are materially altering economics and market access pathways in 2026 (examples summarized below), making regulatory strategy and payer engagement essential components of go-to-market planning.
- Clinical innovation: Advances in miniaturized implantable leads and alternate defibrillation form factors are widening patient cohorts eligible for device therapy, thus enlarging the addressable market.
Regulatory and reimbursement dynamics that will matter in 2026
- Reimbursement updates: Effective January 1, 2026, Medicare physician payment rates for cardiac rhythm management procedures increased by 3.8%. This change improves procedure-level economics and can accelerate adoption curves where reimbursement sensitivity has been a barrier.
- Regulatory requirements: The FDA continues to demand PMA pathways for many classes of defibrillator products, and PMA expectations for next-generation WCDs and AEDs remain a gating factor for commercialization plans. Companies should incorporate PMA timelines and data requirements into 2026 R&D and regulatory budgets.
- Notable approvals: The approval of smaller implantable leads for pediatric use and the arrival of commercially cleared wearable and patch defibrillators have immediate clinical and market implications — expanding indications, enabling new channels, and intensifying competitive dynamics.
Competitive landscape — what to watch from leading players
The market exhibits moderate concentration: the top three players control more than half of the market, and the top five capture roughly two-thirds. That constellation creates both advantages for incumbents (scale, distribution) and windows for disruptors (innovation-led disintermediation).
- ZOLL Medical Corporation (Chelmsford, MA): ZOLL’s strategy emphasizes end-to-end emergency care — AEDs, wearable solutions, and advanced EMS/hospital monitors. Their recent FDA clearance of the Zenix monitor/defibrillator for EMS and hospital use reinforces their position in integrated acute-care systems and will inform competitive procurement dynamics in 2026.
- Stryker Corporation (Kalamazoo, MI) & Physio‑Control (Redmond, WA): With established LIFEPAK product families and an integrated emergency care approach, these entities compete on robustness and OEM integration. Their focus on monitor/defibrillator platforms makes them primary vendors for EMS and hospital purchasers evaluating reliability and lifecycle service economics.
- Medtronic plc (Minneapolis, MN): As a leader in implantable defibrillators (ICDs and CRT‑D systems), Medtronic’s product and reimbursement guidance shapes clinical adoption pathways. Updates to coding and claims processing that Medtronic published for 2026 will reduce administrative friction for implant centers and influence hospital procurement timing.
- Kestra Medical Technologies (Kirkland, WA) and Element Science (San Francisco, CA): These newer entrants are advancing wearable and patch-based WCDs, incorporating patient comfort and software differentiation. Element Science’s Jewel Patch WCD received FDA approval for U.S. commercial distribution in mid‑2025 and was subsequently recognized for innovation in 2026 — signaling that device form factor innovation is a credible challenger to incumbent product portfolios.
Recent events that reset competition and access
- Mid‑2025 to early‑2026 approvals and recognitions have increased competitive intensity: a commercially cleared patch WCD and new monitor/defibrillator clearances expand options for EMS and outpatient care.
- Pediatric device innovation — approval of the smallest implantable defibrillator lead — opens previously constrained patient segments and will require tailored commercialization and clinical training programs.
- Industry recognition of AI-enabled products is accelerating investor and hospital interest in devices that promise improved specificity and lower false alarm rates; this will influence R&D allocation decisions in 2026.
Strategic implications for 2026 — four prioritized plays
- Invest selectively in software and data services: With device commoditization risk rising, software-enabled differentiation (remote monitoring subscriptions, AI analytics, predictive maintenance) offers higher-margin revenue streams. Prioritize modular architectures that allow hardware-agnostic services to scale across installed bases.
- Align regulatory and reimbursement roadmaps: Integrate PMA timelines and 2026 reimbursement changes into product launch calendars. Early payer engagement and evidence generation targeting new CPT pathways will accelerate adoption post‑approval.
- Optimize channel strategy by care setting: EMS/hospital procurement differs materially from public-access and home-care channels. Design tailored commercial models — service bundles for hospitals, simplified logistics and training for public programs, and patient engagement tools for home care.
- Use M&A to fill capability gaps: Given moderate market concentration, targeted acquisitions (wearable tech, AI software, pediatric leads) can rapidly expand addressable markets and neutralize emerging competitive threats. Prioritize targets with validated clinical data and clear regulatory pathways.
What PW Consulting’s full report provides (practical, operational intelligence)
The full Defibrillator Market report is designed as an executable resource for 2026 planning cycles. Highlights include:
- Top‑down market model with annualized forecasts through 2032 and sensitivity scenarios tied to reimbursement shifts and regulatory timelines.
- Operational playbooks for product launch, market access, and EMS/hospital deployment that include go‑to‑market sequencing, training templates, and service economics.
- Competitive benchmarking that evaluates product portfolios, channel strength, R&D pipelines, and go‑to‑market execution across incumbent and emerging vendors.
- Regulatory and reimbursement mapping that identifies critical approval milestones, expected PMA requirements, and recommended payer engagement strategies for 2026.
- M&A and partnership target screening with acquisition rationale, integration risks, and valuation considerations tailored to strategic priorities.
- Scenario planning modules that allow executives to model outcomes under alternate regulatory, reimbursement, and technology adoption assumptions.
Note: To preserve the “trailer” value of this briefing, granular regional splits, product-level revenue tables, and the proprietary segmentation matrices are not included here; these items are available within the subscriber report and its downloadable datasets.
How to convert insight into action in Q1–Q2 2026
- Mobilize a cross‑functional 90‑day plan that aligns clinical affairs, regulatory, and commercial teams around the 2026 regulatory and reimbursement calendar.
- Begin rapid due diligence on small, high‑impact targets (software firms, niche wearable vendors, pediatric-lead specialists) whose capabilities can be integrated within 12–18 months.
- Run pilots that bundle devices with remote monitoring services in representative EMS and hospital environments to fast‑track procurement decisions during 2026 purchasing cycles.
- Commit to an evidence roadmap: define prospective registries and real‑world evidence studies that will support both PMA submissions and payer value dossiers.
Conclusion — why act now
The market outlook for defibrillators through 2032 is constructive and actionable. With a forecasted CAGR of roughly 7.35% and meaningful market expansion beginning in 2026, companies that integrate regulatory foresight, payer strategy, and software-enabled product planning will capture disproportionate value. The competitive landscape rewards both scale and nimble innovation; the next 12 months are a window to reset positioning through targeted investments, partnerships, and launch sequencing.
PW Consulting’s full report supplies the granular inputs, scenario tools, and commercial playbooks required to convert projection into profitable execution. Contact PW Consulting or visit our research portal to access the comprehensive datasets, segmentation tables, and action templates that will underpin your 2026 strategy.
For detailed analysis of this topic, please visit the official page: Defibrillator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com