

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Ceramic Tiles Market to Reach USD 363.32B by 2032 at 6.92% CAGR

Ceramic Tiles Market 2026: A Strategic Preview for Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a high‑level strategic preview of our Ceramic Tiles Market research — a targeted briefing designed to crystallize the decisions that will matter in 2026. This is a “trailer”: it conveys the analytical frame, the operative themes, and the implications that senior leaders must act on today while intentionally reserving detailed segment tables and granular country splits for the full report.
Ceramic Tiles Market
Market at a glance — headline macro trajectory
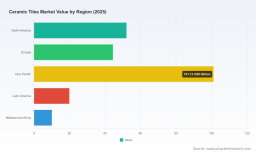
Using 2025 as the report base year, the ceramic tiles market has shown steady expansion through the historical window (2020–2025) and is forecast on a multi‑scenario basis across 2026–2032. The total market expanded from roughly USD 163.2 Billion in 2020 to about USD 227.8 Billion in 2025, and at an underlying compound annual growth rate of 6.92% our central forecast projects continued growth to an approximate USD 363.3 Billion by 2032. These headline numbers frame the strategic choices for manufacturers, distributors, specification firms and investors heading into 2026.
Ceramic Tiles Market
Why this briefing matters for 2026 decisions
- Capital allocation: where incremental capacity or retrofit spending is most likely to generate above‑market returns.
- Trade & sourcing strategy: how evolving trade remedies and regional policy are reshaping cost curves and supply routes.
- Product and channel playbooks: which product attributes, formats and go‑to‑market models will unlock specification and premium pricing.
- Sustainability and compliance: how new standards and customer expectations are redefining product lifecycles and procurement criteria.
Core market dynamics shaping 2026
The near‑term environment is the product of demand momentum and evolving supply‑side constraints. Residential renovation cycles and infrastructure‑driven public construction continue to underpin volume growth, while buoyant commercial finishes and architectural trends sustain premiumization in selected segments. On the supply side, the sector is wrestling with three structural pressures:
Ceramic Tiles Market
- Input volatility: clay remains the primary raw material, and exposure to energy prices, freight dislocations and regional logistics continues to create cost swings that translate rapidly through margins and contract pricing.
- Labor and capacity: in several advanced markets, notably the U.S., labor shortages reported in 2025 are constraining the ability to scale output without productivity investment or automation.
- Trade and regulation: 2025–2026 has seen renewed policy activity — safeguard and antidumping investigations and the entry into force of standardized environmental product rules — which together are altering cross‑border flows and the cost of compliance.
Two regulatory developments deserve immediate board‑level attention. First, several jurisdictions have initiated investigations and measures targeting imported tiles to protect local producers; these are altering supply routes and creating short‑term arbitrage opportunities for geographically diversified producers. Second, the new EN 17160:2026 Product Category Rules establish harmonized expectations for environmental product declarations and life‑cycle assessment in the EU and markets that benchmark European standards — a clear accelerant for product differentiation based on verified sustainability claims.
Competitive landscape — strategic positions and implications
The competitive map is populated by a mix of global conglomerates, regional champions and specialized premium players. The market is moderately consolidated: large multinational manufacturers exert scale advantages while a wide set of regional producers remain influential in local channels. Below I summarize the strategic posture of several firms featured in our competitive audit and what it means for competitors and partners.
- Mohawk Industries — A vertically integrated global leader with broad manufacturing footprint and deep downstream distribution. Strengths lie in scale, integrated raw‑material access and channel control; threats are exposure to cyclical North American construction and the need to keep productivity investment on pace with volume growth.
- RAK Ceramics — A capacity‑heavy global manufacturer notable for rapid production upgrades and a focus on large‑format production. The company’s investments in format flexibility position it well where large‑format aesthetic trends and architectural applications are expanding.
- Daltile — A US‑centric manufacturer‑distributor with strong domestic sourcing credentials. Their high domestic content proposition is defensible in light of import scrutiny but requires ongoing investment in labor productivity and local logistics to preserve margins.
- Grupo Lamosa and other regional champions — These companies leverage tight regional distribution and cost‑competitive manufacturing to defend scale in Latin America and similar markets. Expect continued emphasis on cost efficiency and tailored product mixes to serve heterogenous local demand.
- SCG Ceramics , Kajaria Ceramics — Asian manufacturers with strong domestic leadership and export capabilities. Their proximity to growing regional demand and cost‑competitive manufacturing base supports aggressive channel expansion outside mature markets.
- Porcelanosa Grupo , GranitiFiandre , Atlas Concorde , Pamesa and the Tile of Spain / ASCER collective — These players define the premium and design‑led end of the market, leveraging innovation, large‑format technologies and sustainability positioning to command specification share in architectural and high‑end residential projects.
Collectively, these players illustrate three enduring strategic levers: (1) scale and vertical integration to manage cost and raw‑material exposure, (2) manufacturing flexibility to capture format and product trends, and (3) brand and specification capability to extract premium margins in design‑led segments.
Recent developments to watch (implications for 2026)
- Safeguard measures and continuing antidumping investigations are reshaping sourcing economics and channel strategies. Firms should model immediate supply re‑routing and medium‑term localization options.
- Targeted production upgrades by major manufacturers (notably to produce larger formats) signal where product demand is migrating. Manufacturers that delay format flexibility risk obsolescence in specification channels.
- New harmonized environmental PDRs and life‑cycle rules increase the cost of non‑compliance while creating premium opportunities for early movers who can substantiate lower carbon footprints.
What the PW Consulting full report delivers (practical, actionable content)
Our full Ceramic Tiles Market report is structured to move leaders from insight to action. Highlights include:
- Transparent market sizing and scenario modeling (historical 2020–2025 and forward projections to 2032) with sensitivity analysis for energy, freight and policy shocks.
- Supply chain heat maps and capacity overlays identifying pinch points and optional nearshoring partners.
- Competitor scorecards and capability matrices assessing manufacturing technology, format flexibility, sustainability credentials and distribution reach.
- Commercial playbooks for pricing, channel segmentation (trade, retail, specification), and product portfolio optimization aligned to value pools.
- Regulatory & trade matrix covering antidumping, safeguard actions and compliance frameworks — and the tactical responses that mitigate risk.
- Investment decision support: CapEx prioritization, expected payback ranges under alternative demand scenarios and M&A target screening criteria.
- Actionable templates for sustainability reporting aligned to EN 17160 and practical steps to lower embodied carbon across the value chain.
Note: detailed regional and application-level splits, plus company‑level volume and revenue tables, are intentionally reserved for the full report and data annexes — this preview is designed to communicate direction and strategic choices without disclosing the discrete segmentation cells.
Strategic imperatives for 2026
- Hedge input and logistics risk. Scenario‑proof procurement through diversified suppliers, indexed contracts for energy, and contracted freight capacity will materially reduce margin volatility.
- Invest in format and finishing flexibility. Large‑format and advanced glazing options are accelerating specification wins. Prioritize retrofit lines that allow rapid SKU pivoting and lower changeover times.
- Embed verified sustainability. Compliance with EN 17160 and credible EPDs move from “nice‑to‑have” to procurement table stakes for major construction and institutional buyers.
- Optimize channel mix. Strengthen specification sales teams, digital tools for architects and designers, and capability in direct‑to‑consumer channels where margin capture is highest.
- Scenario‑driven capacity strategy. Balance near‑term spot arbitrage against long‑term regional localization; use contract manufacturing or JV structures to limit upfront capital while securing supply.
- Augment workforce and automation. Address labor shortages by combining selective automation with targeted skills programs to preserve quality and throughput.
How to use this research
Executives in manufacturing, distribution, private equity, and infrastructure procurement will find the full report useful for capital planning, commercial strategy and risk mitigation. Use the report to:
- Validate your 2026 investment roadmap against market scenarios and competitor moves.
- Prioritize product development and capacity upgrades that unlock the largest near‑term margin uplift.
- Design contingency playbooks for trade disruptions or regulatory shifts.
If your objective is to move from strategic intent to prioritized action in 2026, the full PW Consulting Ceramic Tiles Market report provides the data annex, granular segmentation and executable playbooks senior teams need. This preview has outlined the trajectory and the levers — the complete dataset and tactical guidance are available through our report portal and advisory services.
For boards and executive teams, the essential takeaway is simple: the ceramic tiles market is expanding on a healthy macro trajectory, but 2026 is a tactical inflection point. Companies that act now to de‑risk supply chains, certify sustainability credentials, and align manufacturing flexibility to evolving product formats will capture outsized returns in the decade ahead.
For detailed analysis of this topic, please visit the official page: Ceramic Tiles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com